Credit-note turnover adjustments preserve inverted-duty refunds, while ministerial re-computation does not constitute an impermissible appellate reman...
Revisional jurisdiction over export quota premium deductions requires both error and Revenue prejudice; a permissible assessment view cannot be displa...
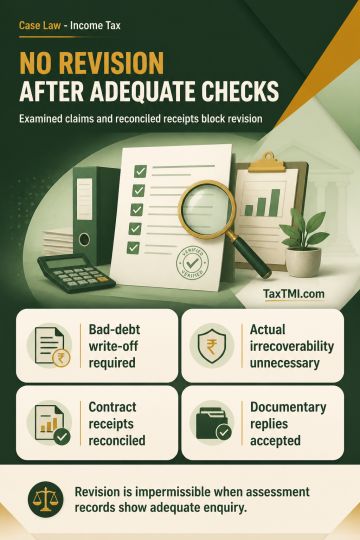
Bad-debt deduction after 1 April 1989 requires write-off in the accounts and satisfaction of the condition that the debt was considered in computing income; actual irrecoverability need not be established. The notes state that revision under section 263 is impermissible where the assessment record shows that the Assessing Officer examined the claim and supporting evidence. They also explain that reconciled contract receipts cannot be treated as understated merely because bank credits include mobilisation, material or other non-revenue advances. A reasoned assessment order is not required where documentary replies have been examined and accepted.
Bad-debt deduction after 1 April 1989 requires write-off in the accounts and satisfaction of the condition that the debt was considered in computing income; actual irrecoverability need not be established. The notes state that revision under section 263 is impermissible where the assessment record shows that the Assessing Officer examined the claim and supporting evidence. They also explain that reconciled contract receipts cannot be treated as understated merely because bank credits include mobilisation, material or other non-revenue advances. A reasoned assessment order is not required where documentary replies have been examined and accepted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI