Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
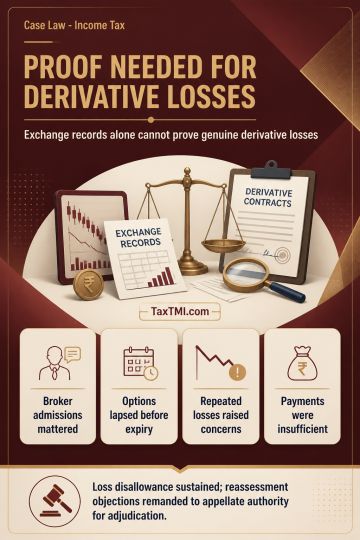
Derivative option losses claimed through a recognised exchange and registered broker require independent proof of genuineness where investigation material indicates manipulated transactions. Contract notes and banking-channel payments alone were insufficient in light of broker admissions, options acquired shortly before expiry and allowed to lapse, and repeated losses; the taxpayer did not rebut this material, so the loss disallowance was sustained. Jurisdictional objections to reassessment, raised specifically before the Tribunal and requiring factual verification, were admitted but remanded to the appellate authority for detailed adjudication. The appeal was partly allowed for statistical purposes.
Derivative option losses claimed through a recognised exchange and registered broker require independent proof of genuineness where investigation material indicates manipulated transactions. Contract notes and banking-channel payments alone were insufficient in light of broker admissions, options acquired shortly before expiry and allowed to lapse, and repeated losses; the taxpayer did not rebut this material, so the loss disallowance was sustained. Jurisdictional objections to reassessment, raised specifically before the Tribunal and requiring factual verification, were admitted but remanded to the appellate authority for detailed adjudication. The appeal was partly allowed for statistical purposes.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918