Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
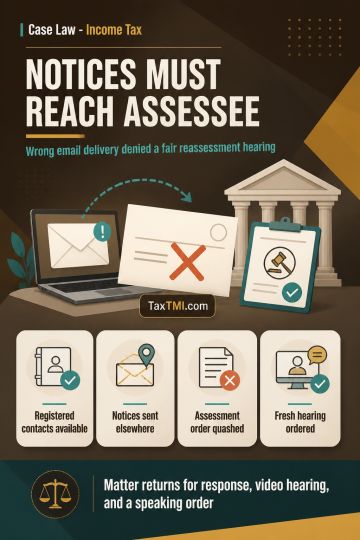
Fair and effective opportunity of hearing in faceless reassessment requires communications to reach the assessee through its notified or registered contact details. The High Court noted that the assessee had provided an email address in its return and had another registered on the income-tax portal and MCA database, but subsequent notices were sent only to a resigned auditor's email address. As this prevented an adequate response with supporting material, the assessment order and demand notice were quashed and remanded for fresh proceedings, including a response opportunity, video-conference hearing and speaking order. The merits and validity of service under Rule 127 were left open.
Fair and effective opportunity of hearing in faceless reassessment requires communications to reach the assessee through its notified or registered contact details. The High Court noted that the assessee had provided an email address in its return and had another registered on the income-tax portal and MCA database, but subsequent notices were sent only to a resigned auditor's email address. As this prevented an adequate response with supporting material, the assessment order and demand notice were quashed and remanded for fresh proceedings, including a response opportunity, video-conference hearing and speaking order. The merits and validity of service under Rule 127 were left open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI