Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
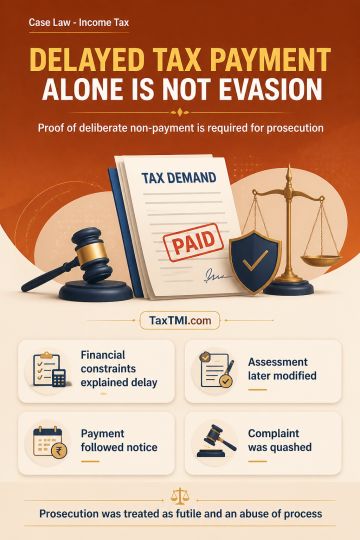
Wilful evasion of tax payment requires material showing circumstances and conduct from which a deliberate attempt to avoid payment can be inferred. Although culpable mental state may be presumed, delayed payment within the stipulated period alone does not establish the offence. Where the original assessment was acknowledged as erroneous and later modified, the delay was explained by financial constraints, and payment was made after receipt of a show-cause notice, the material indicates delayed payment rather than a wilful attempt to evade tax. On those facts, prosecution was treated as futile and an abuse of process, and the complaint was quashed.
Wilful evasion of tax payment requires material showing circumstances and conduct from which a deliberate attempt to avoid payment can be inferred. Although culpable mental state may be presumed, delayed payment within the stipulated period alone does not establish the offence. Where the original assessment was acknowledged as erroneous and later modified, the delay was explained by financial constraints, and payment was made after receipt of a show-cause notice, the material indicates delayed payment rather than a wilful attempt to evade tax. On those facts, prosecution was treated as futile and an abuse of process, and the complaint was quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI