Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
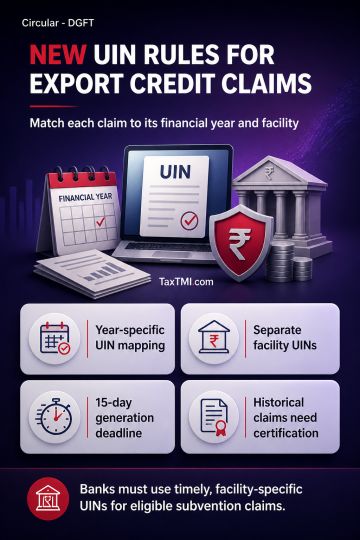
Interest subvention claims under the Export Promotion Mission are clarified for export credit disbursed from 2 January 2026. Banks may file additional eligible claims by 31 July 2026 where the UIN was generated by 31 May 2026. From FY 2026-27, UINs must be generated within 15 days of original disbursal, and claims may be filed up to the end of the following month. Separate UINs are required for pre-shipment and post-shipment facilities. For running credit extending across financial years, subvention claims must be mapped to the UIN for the financial year in which the benefit accrues. Historical additional claims must be filed separately with the required external auditor's certificate.
Interest subvention claims under the Export Promotion Mission are clarified for export credit disbursed from 2 January 2026. Banks may file additional eligible claims by 31 July 2026 where the UIN was generated by 31 May 2026. From FY 2026-27, UINs must be generated within 15 days of original disbursal, and claims may be filed up to the end of the following month. Separate UINs are required for pre-shipment and post-shipment facilities. For running credit extending across financial years, subvention claims must be mapped to the UIN for the financial year in which the benefit accrues. Historical additional claims must be filed separately with the required external auditor's certificate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI