Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
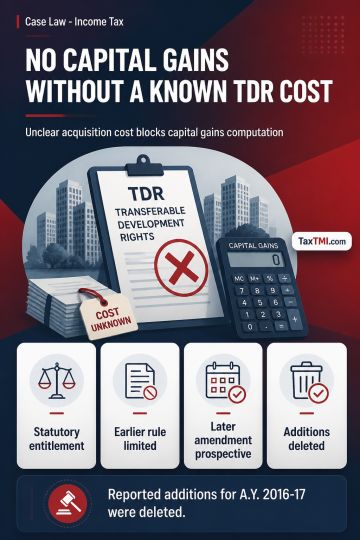
Capital gains on transfer of TDR/FSI credit may not arise where the applicable law provides no ascertainable cost of acquisition and the computation mechanism therefore fails. The charging and computation provisions operate as an integrated code, consistent with the principle in CIT v. B.C. Srinivasa Setty. TDR/DRC granted under development regulations in lieu of compensation was treated as a statutory entitlement acquired without monetary expenditure, whose value remained indeterminate until utilisation. The pre-amendment deeming provision did not cover such rights, while the later inclusion of other intangible assets and rights applied only from A.Y. 2024-25 and could not retrospectively cure the gap. The land and TDR were distinct assets, so the land's value could not be treated as the TDR's cost. The reported additions for A.Y. 2016-17 were deleted.
Capital gains on transfer of TDR/FSI credit may not arise where the applicable law provides no ascertainable cost of acquisition and the computation mechanism therefore fails. The charging and computation provisions operate as an integrated code, consistent with the principle in CIT v. B.C. Srinivasa Setty. TDR/DRC granted under development regulations in lieu of compensation was treated as a statutory entitlement acquired without monetary expenditure, whose value remained indeterminate until utilisation. The pre-amendment deeming provision did not cover such rights, while the later inclusion of other intangible assets and rights applied only from A.Y. 2024-25 and could not retrospectively cure the gap. The land and TDR were distinct assets, so the land's value could not be treated as the TDR's cost. The reported additions for A.Y. 2016-17 were deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI