Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
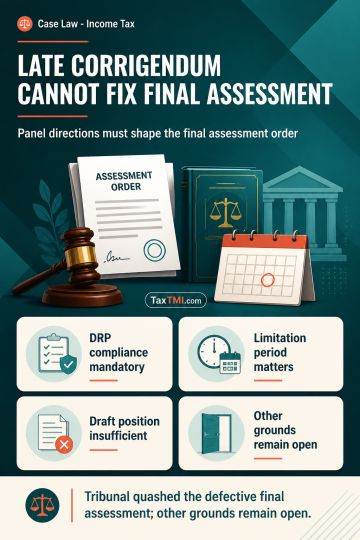
Compliance with Dispute Resolution Panel directions under section 144C is mandatory when issuing the final assessment order. The text explains that where the Transfer Pricing Officer has given effect to those directions within the applicable limitation period, the Assessing Officer cannot issue a final order repeating the draft assessment position without incorporating them. A corrigendum issued after limitation cannot retrospectively cure that statutory defect or supply required findings, and is beyond jurisdiction. The described Tribunal decision therefore quashed the defective final assessment order, while leaving other grounds open.
Compliance with Dispute Resolution Panel directions under section 144C is mandatory when issuing the final assessment order. The text explains that where the Transfer Pricing Officer has given effect to those directions within the applicable limitation period, the Assessing Officer cannot issue a final order repeating the draft assessment position without incorporating them. A corrigendum issued after limitation cannot retrospectively cure that statutory defect or supply required findings, and is beyond jurisdiction. The described Tribunal decision therefore quashed the defective final assessment order, while leaving other grounds open.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI