Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
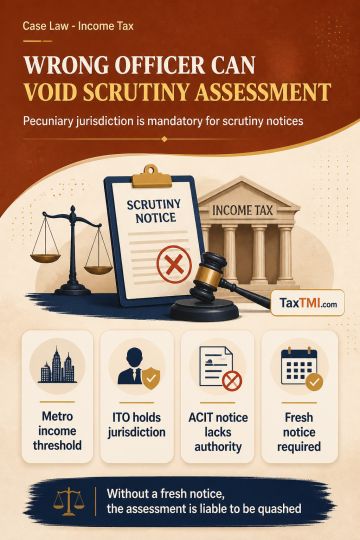
Allocation of pecuniary jurisdiction under CBDT Instruction No. 01/2011 is described as a jurisdictional requirement for issuing a scrutiny notice under section 143(2), rather than a mere procedural formality. For a non-corporate assessee in a metro city whose returned income is below the prescribed limit, jurisdiction lies with the ITO, while a notice issued by the ACIT is treated as lacking legal authority. The notes further state that such an additional legal ground may be admitted when it goes to the root of the matter and requires no further factual verification. Without a fresh notice from the competent officer, the assessment is described as vitiated and liable to be quashed.
Allocation of pecuniary jurisdiction under CBDT Instruction No. 01/2011 is described as a jurisdictional requirement for issuing a scrutiny notice under section 143(2), rather than a mere procedural formality. For a non-corporate assessee in a metro city whose returned income is below the prescribed limit, jurisdiction lies with the ITO, while a notice issued by the ACIT is treated as lacking legal authority. The notes further state that such an additional legal ground may be admitted when it goes to the root of the matter and requires no further factual verification. Without a fresh notice from the competent officer, the assessment is described as vitiated and liable to be quashed.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI