Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
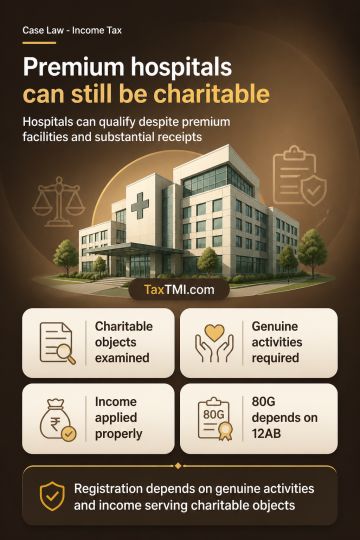
Charitable registration under section 12AB requires examination of whether an institution's objects are charitable, its activities are genuine, and its income is applied to those objects. For hospitals providing medical relief, premium facilities, substantial receipts, advanced infrastructure, organised administration, and higher treatment costs are not, by themselves, statutory indicators of commerciality. Alleged non-compliance with other laws is relevant only where established by the competent authority and material to achieving the charitable objects. The discussion also distinguishes renewal proceedings from retrospective cancellation, noting that cancellation from the original grant date requires a foundational defect such as fraud, suppression, misrepresentation, or abandonment of charitable purposes. Consequential section 80G approval is addressed as dependent on the validity of section 12AB registration.
Charitable registration under section 12AB requires examination of whether an institution's objects are charitable, its activities are genuine, and its income is applied to those objects. For hospitals providing medical relief, premium facilities, substantial receipts, advanced infrastructure, organised administration, and higher treatment costs are not, by themselves, statutory indicators of commerciality. Alleged non-compliance with other laws is relevant only where established by the competent authority and material to achieving the charitable objects. The discussion also distinguishes renewal proceedings from retrospective cancellation, noting that cancellation from the original grant date requires a foundational defect such as fraud, suppression, misrepresentation, or abandonment of charitable purposes. Consequential section 80G approval is addressed as dependent on the validity of section 12AB registration.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI