Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
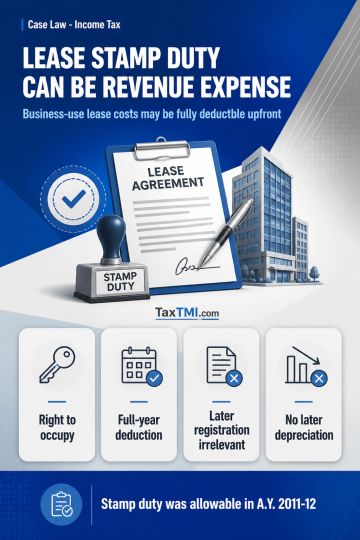
Stamp duty and registration charges incurred for executing a lease deed may constitute revenue expenditure where the arrangement grants only a right to occupy, use, and commercially exploit property during the lease term, rather than ownership or an independent capital asset. The expenditure is deductible in full in the year when the lease rights and obligations crystallise; later registration does not change its character or timing. On the stated facts, the stamp duty was therefore allowable in A.Y. 2011-12. Because the full amount was deductible in that year, it could not subsequently be capitalised, amortised over the lease term, or subjected to depreciation, making later-year depreciation claims unsustainable.
Stamp duty and registration charges incurred for executing a lease deed may constitute revenue expenditure where the arrangement grants only a right to occupy, use, and commercially exploit property during the lease term, rather than ownership or an independent capital asset. The expenditure is deductible in full in the year when the lease rights and obligations crystallise; later registration does not change its character or timing. On the stated facts, the stamp duty was therefore allowable in A.Y. 2011-12. Because the full amount was deductible in that year, it could not subsequently be capitalised, amortised over the lease term, or subjected to depreciation, making later-year depreciation claims unsustainable.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI