Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
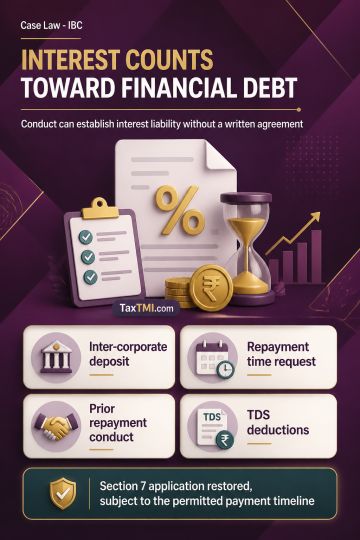
At the Section 7 admission stage, financial debt must be assessed by including interest payable under the underlying financial arrangement where the surrounding evidence supports that liability. Inter corporate deposit transactions, demand letters specifying principal and interest, the corporate debtor's request for time to repay the entire amount, prior repayment conduct, and TDS deductions may cumulatively establish acknowledgment of the interest component. A written agreement is not indispensable if subsequent conduct corroborates the arrangement. Excluding interest and considering only principal can therefore understate the debt for applying the statutory threshold, resulting in restoration of the Section 7 application subject to the permitted payment timeline.
At the Section 7 admission stage, financial debt must be assessed by including interest payable under the underlying financial arrangement where the surrounding evidence supports that liability. Inter corporate deposit transactions, demand letters specifying principal and interest, the corporate debtor's request for time to repay the entire amount, prior repayment conduct, and TDS deductions may cumulatively establish acknowledgment of the interest component. A written agreement is not indispensable if subsequent conduct corroborates the arrangement. Excluding interest and considering only principal can therefore understate the debt for applying the statutory threshold, resulting in restoration of the Section 7 application subject to the permitted payment timeline.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918