Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
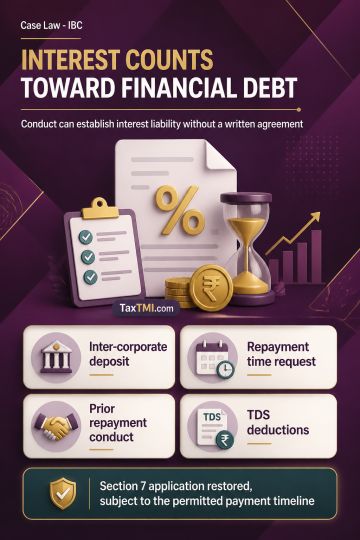
At the Section 7 admission stage, financial debt must be assessed by including interest payable under the underlying financial arrangement where the surrounding evidence supports that liability. Inter corporate deposit transactions, demand letters specifying principal and interest, the corporate debtor's request for time to repay the entire amount, prior repayment conduct, and TDS deductions may cumulatively establish acknowledgment of the interest component. A written agreement is not indispensable if subsequent conduct corroborates the arrangement. Excluding interest and considering only principal can therefore understate the debt for applying the statutory threshold, resulting in restoration of the Section 7 application subject to the permitted payment timeline.
At the Section 7 admission stage, financial debt must be assessed by including interest payable under the underlying financial arrangement where the surrounding evidence supports that liability. Inter corporate deposit transactions, demand letters specifying principal and interest, the corporate debtor's request for time to repay the entire amount, prior repayment conduct, and TDS deductions may cumulatively establish acknowledgment of the interest component. A written agreement is not indispensable if subsequent conduct corroborates the arrangement. Excluding interest and considering only principal can therefore understate the debt for applying the statutory threshold, resulting in restoration of the Section 7 application subject to the permitted payment timeline.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI