Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
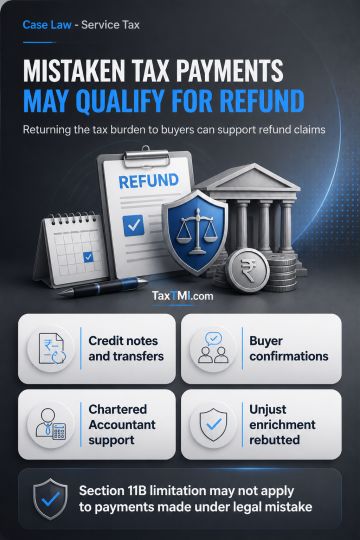
Refund claims involving tax paid under a mistaken understanding of service-tax liability turn on unjust enrichment and the character of the payment. Where the amount collected from a buyer is reversed through credit notes, supported by fund transfers and confirmations from the buyer and Chartered Accountant, the presumption that the tax burden was passed on may be rebutted, permitting refund. Amounts paid under a mistake of law may remain deposits rather than duty; consequential interest may likewise lack the character of duty. On that basis, limitation and the refund mechanism under Section 11B may not apply to such payments, while unjust enrichment does not bar refund after the incidence has been returned to the buyer.
Refund claims involving tax paid under a mistaken understanding of service-tax liability turn on unjust enrichment and the character of the payment. Where the amount collected from a buyer is reversed through credit notes, supported by fund transfers and confirmations from the buyer and Chartered Accountant, the presumption that the tax burden was passed on may be rebutted, permitting refund. Amounts paid under a mistake of law may remain deposits rather than duty; consequential interest may likewise lack the character of duty. On that basis, limitation and the refund mechanism under Section 11B may not apply to such payments, while unjust enrichment does not bar refund after the incidence has been returned to the buyer.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI