Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
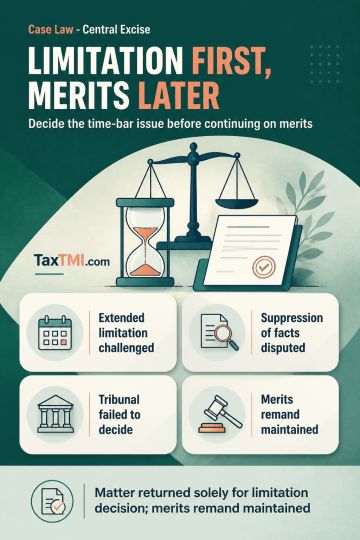
A limitation objection to a demand raised under the extended limitation period must be decided before the matter proceeds on merits where success on limitation could make remand unnecessary. The notes state that the Tribunal had recorded the contention that the demand was time-barred and that extended limitation was unavailable without suppression of facts, but failed to determine it. The matter was therefore sent back to the Tribunal solely to decide limitation, while the remand on merits was maintained subject to the outcome of that determination.
A limitation objection to a demand raised under the extended limitation period must be decided before the matter proceeds on merits where success on limitation could make remand unnecessary. The notes state that the Tribunal had recorded the contention that the demand was time-barred and that extended limitation was unavailable without suppression of facts, but failed to determine it. The matter was therefore sent back to the Tribunal solely to decide limitation, while the remand on merits was maintained subject to the outcome of that determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI