Opportunity to furnish unsecured-loan confirmations is required before reassessment initiation; proceedings require fresh consideration after taxpayer...
Under-reporting on a first reassessment return attracts penalty, while enhanced misreporting penalty requires proof of a statutory misreporting catego...
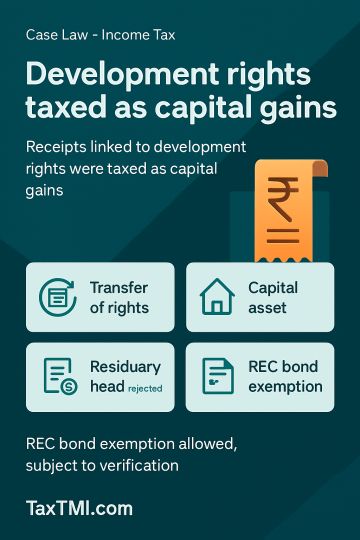
Consideration received for granting development rights under a redevelopment agreement was treated as capital gains because the payment was directly linked to transfer of valuable development rights, which are capital assets; mere retention of rights in the redeveloped premises did not negate the transfer, and the developer's accounting treatment was irrelevant. As the receipt was referable to transfer of a capital asset, it could not be assessed under the residuary head of income. On that basis, the related exemption for investment in REC bonds was allowed, subject to verification of the statutory conditions.
Consideration received for granting development rights under a redevelopment agreement was treated as capital gains because the payment was directly linked to transfer of valuable development rights, which are capital assets; mere retention of rights in the redeveloped premises did not negate the transfer, and the developer's accounting treatment was irrelevant. As the receipt was referable to transfer of a capital asset, it could not be assessed under the residuary head of income. On that basis, the related exemption for investment in REC bonds was allowed, subject to verification of the statutory conditions.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916