Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
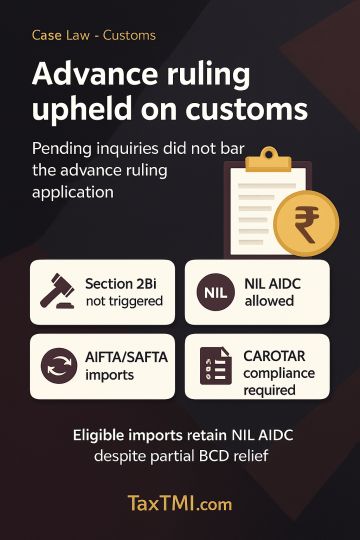
Pending inquiry, audit verification, query letters and DRI investigation did not amount to a formal proceeding raising the same question, so the Section 28I bar on an advance ruling application was not triggered and the application was maintainable. On merits, Serial No. 19 of Notification No. 11/2021-Customs was construed with Section 25(1) to mean that NIL AIDC is available where exemption from basic customs duty is claimed and allowed, whether the BCD relief is full or partial. The benefit was held applicable to eligible AIFTA and SAFTA imports, subject to the relevant notification conditions, including a valid certificate of origin and compliance with CAROTAR.
Pending inquiry, audit verification, query letters and DRI investigation did not amount to a formal proceeding raising the same question, so the Section 28I bar on an advance ruling application was not triggered and the application was maintainable. On merits, Serial No. 19 of Notification No. 11/2021-Customs was construed with Section 25(1) to mean that NIL AIDC is available where exemption from basic customs duty is claimed and allowed, whether the BCD relief is full or partial. The benefit was held applicable to eligible AIFTA and SAFTA imports, subject to the relevant notification conditions, including a valid certificate of origin and compliance with CAROTAR.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918