Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
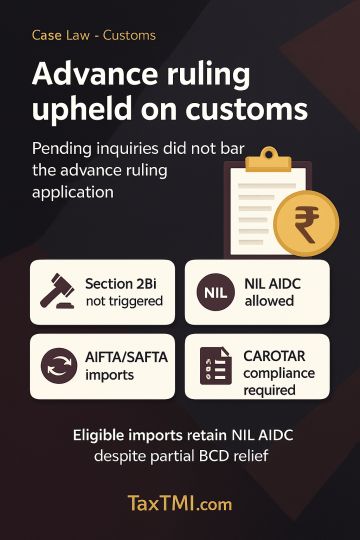
Pending inquiry, audit verification, query letters and DRI investigation did not amount to a formal proceeding raising the same question, so the Section 28I bar on an advance ruling application was not triggered and the application was maintainable. On merits, Serial No. 19 of Notification No. 11/2021-Customs was construed with Section 25(1) to mean that NIL AIDC is available where exemption from basic customs duty is claimed and allowed, whether the BCD relief is full or partial. The benefit was held applicable to eligible AIFTA and SAFTA imports, subject to the relevant notification conditions, including a valid certificate of origin and compliance with CAROTAR.
Pending inquiry, audit verification, query letters and DRI investigation did not amount to a formal proceeding raising the same question, so the Section 28I bar on an advance ruling application was not triggered and the application was maintainable. On merits, Serial No. 19 of Notification No. 11/2021-Customs was construed with Section 25(1) to mean that NIL AIDC is available where exemption from basic customs duty is claimed and allowed, whether the BCD relief is full or partial. The benefit was held applicable to eligible AIFTA and SAFTA imports, subject to the relevant notification conditions, including a valid certificate of origin and compliance with CAROTAR.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI