Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
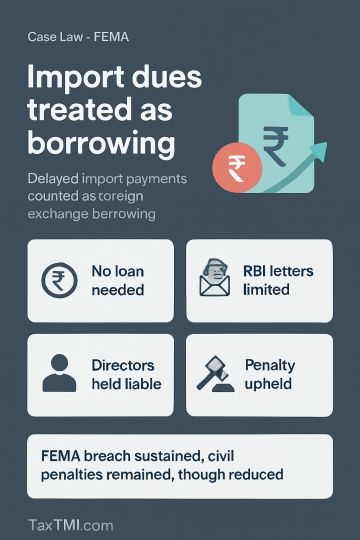
Prolonged non-payment of import dues was treated as a deferred payment arrangement and external commercial borrowing under the RBI circulars and the Borrowing or Lending in Foreign Exchange Regulations; the absence of a formal loan agreement did not alter that character, so FEMA contravention was sustained. Post-facto RBI remittance letters were limited to foreign-exchange permission and did not condone the breach. The Tribunal also upheld liability of the directors for the company's contravention, finding no due diligence defence. It rejected the argument that absence of mens rea barred civil penalty under FEMA, though it reduced the penalties.
Prolonged non-payment of import dues was treated as a deferred payment arrangement and external commercial borrowing under the RBI circulars and the Borrowing or Lending in Foreign Exchange Regulations; the absence of a formal loan agreement did not alter that character, so FEMA contravention was sustained. Post-facto RBI remittance letters were limited to foreign-exchange permission and did not condone the breach. The Tribunal also upheld liability of the directors for the company's contravention, finding no due diligence defence. It rejected the argument that absence of mens rea barred civil penalty under FEMA, though it reduced the penalties.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI