Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
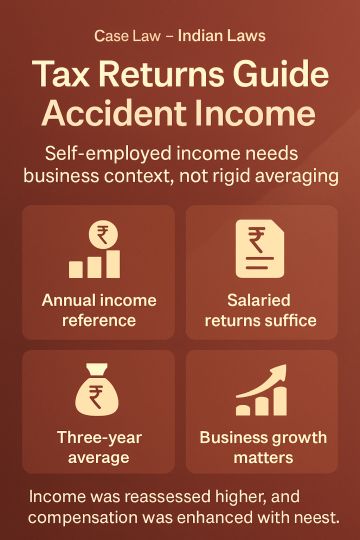
Income tax returns are an important reference point for assessing annual income under the Motor Vehicles Act, but no rigid formula applies. For salaried claimants, the immediately preceding return will ordinarily suffice. For self-employed persons, the proper basis is the average of up to the previous three years' returns, read with the nature, growth and future potential of the business, initial losses or negative income, and other surrounding circumstances. Applying that approach, the deceased's construction business income could not be fixed by a mechanical average alone, so the annual income was reassessed at a higher figure and compensation enhanced with interest as awarded.
Income tax returns are an important reference point for assessing annual income under the Motor Vehicles Act, but no rigid formula applies. For salaried claimants, the immediately preceding return will ordinarily suffice. For self-employed persons, the proper basis is the average of up to the previous three years' returns, read with the nature, growth and future potential of the business, initial losses or negative income, and other surrounding circumstances. Applying that approach, the deceased's construction business income could not be fixed by a mechanical average alone, so the annual income was reassessed at a higher figure and compensation enhanced with interest as awarded.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI