Constitutional personal-liberty safeguards limit PMLA twin bail conditions where completed investigations lead to prolonged incarceration before trial...
Automated airline software subscriptions without human intervention fail technical-services characterisation and do not make available underlying tech...
Business support recruitment and training receipts qualify for presumptive business taxation, not professional taxation under technical consultancy ru...
Treaty exemption for foreign permanent-establishment management fees prevailed, while dividend expense disallowance remained limited to an accepted al...
Centralised assessment transfers: participation after requesting centralisation can bar technical jurisdictional challenges, while assessment disputes...
Binding precedent remains operative despite pending challenge, supporting deletion of interest disallowance when debt is converted into preference sha...
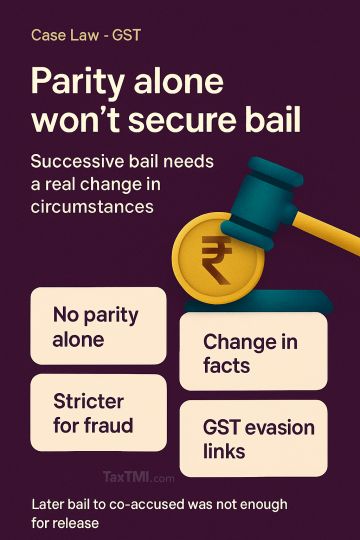
Successive bail applications require a substantial change in facts or circumstances directly affecting the merits; parity with a co-accused alone does not justify release because the court must assess the accused's individual role, the gravity of the allegations and the investigation material. Economic offences are treated as a distinct class for bail and attract a stricter approach because they may involve deliberate conspiracies and broader financial harm. On the stated facts, the accused was prima facie linked to fictitious firms, fake invoices, e-way bills and alleged GST evasion through documentary, electronic and recorded statement material, so later bail to a co-accused did not amount to a sufficient change in circumstances.
Successive bail applications require a substantial change in facts or circumstances directly affecting the merits; parity with a co-accused alone does not justify release because the court must assess the accused's individual role, the gravity of the allegations and the investigation material. Economic offences are treated as a distinct class for bail and attract a stricter approach because they may involve deliberate conspiracies and broader financial harm. On the stated facts, the accused was prima facie linked to fictitious firms, fake invoices, e-way bills and alleged GST evasion through documentary, electronic and recorded statement material, so later bail to a co-accused did not amount to a sufficient change in circumstances.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4907