Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
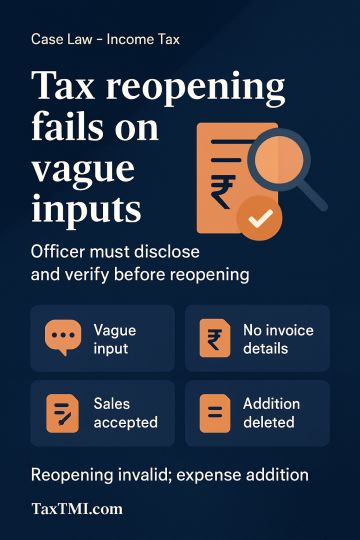
Reassessment under section 148A requires the AO to verify the information, disclose the material and inquiry results to the assessee, consider the reply, and record a reasoned view before reopening. Where the notice was based on vague Investigation Wing inputs alleging bogus purchases, without identifying the disputed invoices or supplying supporting material, the Tribunal found no independent application of mind and held the reopening bad in law. On the merits, the assessee produced GST returns, bills, e-way bills, lorry receipts, ledger and bank evidence, while corresponding sales were accepted; in the absence of any defect or proof of grey-market sourcing, the addition for unexplained expenditure was deleted.
Reassessment under section 148A requires the AO to verify the information, disclose the material and inquiry results to the assessee, consider the reply, and record a reasoned view before reopening. Where the notice was based on vague Investigation Wing inputs alleging bogus purchases, without identifying the disputed invoices or supplying supporting material, the Tribunal found no independent application of mind and held the reopening bad in law. On the merits, the assessee produced GST returns, bills, e-way bills, lorry receipts, ledger and bank evidence, while corresponding sales were accepted; in the absence of any defect or proof of grey-market sourcing, the addition for unexplained expenditure was deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI