Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
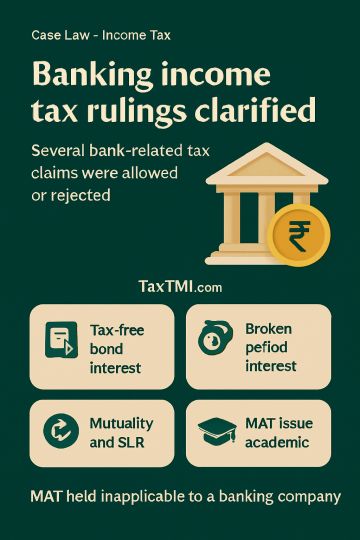
Exempt tax-free bond interest was not met with proportional disallowance where the bonds were earlier-year investments and sufficient own interest-free funds were available; the deletion of disallowance was sustained. Broken period interest on securities held as stock-in-trade was allowed as revenue expenditure. Foreign-currency loan interest from Indian borrowers was taxable on gross basis under the concessional regime. Interest between a foreign bank's head office and Indian branch was treated as self-dealing, so no taxable income or deductible expense arose. Section 14A did not apply to mutuality receipts, SLR default interest was compensatory and deductible, and a fresh expatriate salary claim was not admitted for want of foundational facts. The book-profit issue for standard assets became academic because MAT was held inapplicable to a banking company; interest on overseas placements was remanded only on actual accrual.
Exempt tax-free bond interest was not met with proportional disallowance where the bonds were earlier-year investments and sufficient own interest-free funds were available; the deletion of disallowance was sustained. Broken period interest on securities held as stock-in-trade was allowed as revenue expenditure. Foreign-currency loan interest from Indian borrowers was taxable on gross basis under the concessional regime. Interest between a foreign bank's head office and Indian branch was treated as self-dealing, so no taxable income or deductible expense arose. Section 14A did not apply to mutuality receipts, SLR default interest was compensatory and deductible, and a fresh expatriate salary claim was not admitted for want of foundational facts. The book-profit issue for standard assets became academic because MAT was held inapplicable to a banking company; interest on overseas placements was remanded only on actual accrual.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI