Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
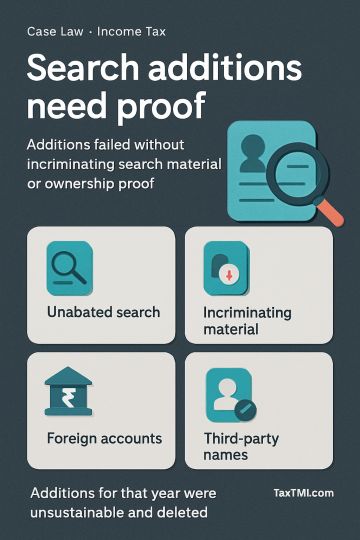
In completed or unabated assessments under section 153A, additions are confined to incriminating material found during the search; material already available with the Revenue, such as the HSBC Geneva Base Note, cannot by itself support an addition. Applying that rule, the article notes that the additions for the relevant year were unsustainable because no incriminating search material linked to them was found. On section 69A, the threshold requirement is proof that the assessee owned the money or asset; where the foreign accounts stood in third-party names and the Revenue could not prove ownership, the additions were properly deleted.
In completed or unabated assessments under section 153A, additions are confined to incriminating material found during the search; material already available with the Revenue, such as the HSBC Geneva Base Note, cannot by itself support an addition. Applying that rule, the article notes that the additions for the relevant year were unsustainable because no incriminating search material linked to them was found. On section 69A, the threshold requirement is proof that the assessee owned the money or asset; where the foreign accounts stood in third-party names and the Revenue could not prove ownership, the additions were properly deleted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI