Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
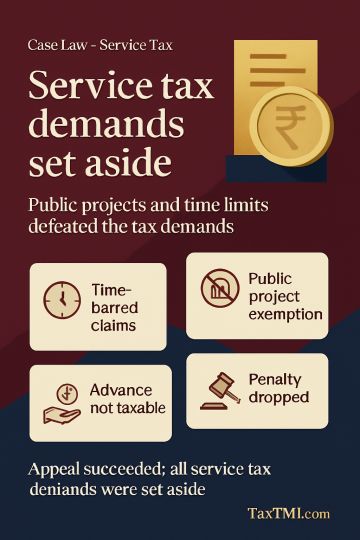
Extended limitation was unavailable because the disputes arose from interpretational issues, the contracts were public projects reflected in the records, and there was no cogent material showing suppression or intent to evade; demands beyond the normal period were therefore time-barred. Works contract exemption was allowed for construction of the FCI food grain godown and the Integrated Farmers' Market Complex, as both were public infrastructure projects falling within the relevant exemption entries and not shown to be predominantly commercial. The mobilization advance demand failed because it was a recoverable, interest-bearing contractual accommodation and was also time-barred. Statutory trade licence fees were treated as a regulatory levy, not taxable consideration, and the penalty for suppression was set aside. The appeal succeeded in full.
Extended limitation was unavailable because the disputes arose from interpretational issues, the contracts were public projects reflected in the records, and there was no cogent material showing suppression or intent to evade; demands beyond the normal period were therefore time-barred. Works contract exemption was allowed for construction of the FCI food grain godown and the Integrated Farmers' Market Complex, as both were public infrastructure projects falling within the relevant exemption entries and not shown to be predominantly commercial. The mobilization advance demand failed because it was a recoverable, interest-bearing contractual accommodation and was also time-barred. Statutory trade licence fees were treated as a regulatory levy, not taxable consideration, and the penalty for suppression was set aside. The appeal succeeded in full.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI