Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
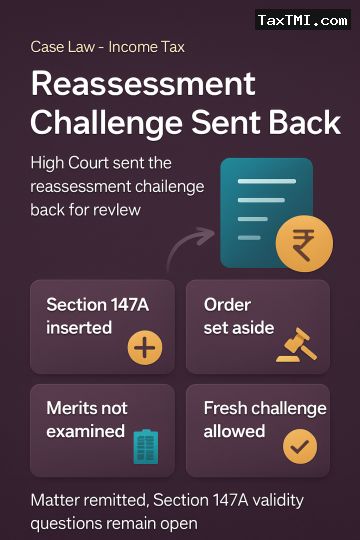
Retrospective insertion of Section 147A altered the foundation of the earlier order quashing reassessment notices, so the HC set aside that order and remitted the matter for fresh consideration. Relying on the Supreme Court's subsequent orders in identical matters, the Court declined to examine the merits and kept open all questions on validity, scope, effect, retrospectivity and applicability of the amended provision. Liberty was granted to the assessee to challenge Section 147A and connected or consequential provisions within the permitted time as part of the remand arrangement.
Retrospective insertion of Section 147A altered the foundation of the earlier order quashing reassessment notices, so the HC set aside that order and remitted the matter for fresh consideration. Relying on the Supreme Court's subsequent orders in identical matters, the Court declined to examine the merits and kept open all questions on validity, scope, effect, retrospectivity and applicability of the amended provision. Liberty was granted to the assessee to challenge Section 147A and connected or consequential provisions within the permitted time as part of the remand arrangement.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI