Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
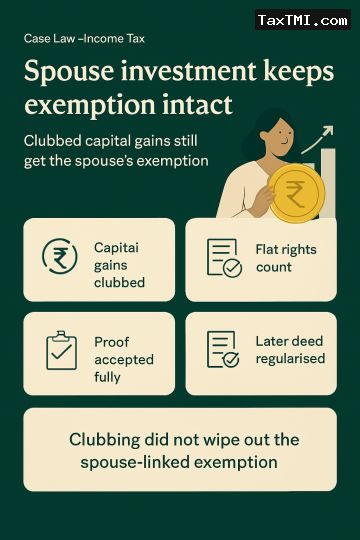
Enforceable rights in a specific residential flat can satisfy the requirement of purchase for beneficial exemption relief, so long as the investment is made within the prescribed period and the later conveyance only regularises an earlier arrangement. Capital gains arising from an asset gifted to a spouse can be clubbed in the transferor's hands because "income" in the clubbing provision includes capital gains; once clubbed, the corresponding exemption attached to the spouse's residential investment must also be allowed to avoid distorted computation. Transfer expenses actually incurred and proved by invoices and bank records were allowed in full under the computation provisions, and were not to be reduced merely by reference to ownership share.
Enforceable rights in a specific residential flat can satisfy the requirement of purchase for beneficial exemption relief, so long as the investment is made within the prescribed period and the later conveyance only regularises an earlier arrangement. Capital gains arising from an asset gifted to a spouse can be clubbed in the transferor's hands because "income" in the clubbing provision includes capital gains; once clubbed, the corresponding exemption attached to the spouse's residential investment must also be allowed to avoid distorted computation. Transfer expenses actually incurred and proved by invoices and bank records were allowed in full under the computation provisions, and were not to be reduced merely by reference to ownership share.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI