Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
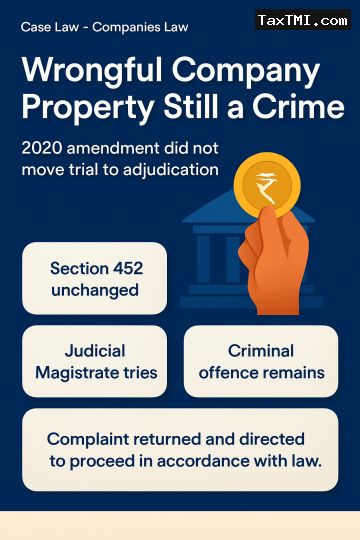
The 2020 amendment to Section 452 did not decriminalise wrongful withholding of company property or transfer trial jurisdiction to the Adjudicating Officer under Section 454. Section 452 still contemplates a criminal offence, with the court trying the offence empowered to order delivery of the property or refund and, on default, impose imprisonment; that punitive function cannot be exercised administratively under Section 454. Read with Sections 435 and 436, the offence remains triable by the competent Judicial Magistrate. The order returning the complaint was set aside and the complaint was directed to be received and proceeded with in accordance with law.
The 2020 amendment to Section 452 did not decriminalise wrongful withholding of company property or transfer trial jurisdiction to the Adjudicating Officer under Section 454. Section 452 still contemplates a criminal offence, with the court trying the offence empowered to order delivery of the property or refund and, on default, impose imprisonment; that punitive function cannot be exercised administratively under Section 454. Read with Sections 435 and 436, the offence remains triable by the competent Judicial Magistrate. The order returning the complaint was set aside and the complaint was directed to be received and proceeded with in accordance with law.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI