Pre-amendment reassessment limitation bars late notices under the preserved regime, invalidating consequential reassessment for affected earlier asses...
Cash-sales explanations for bank deposits require documentary reconciliation; reassessment notice survived where effective response time was available...
Functional comparability in transfer pricing prevents ad hoc arm's length adjustments where functions, assets, risks and reliable comparables are unes...
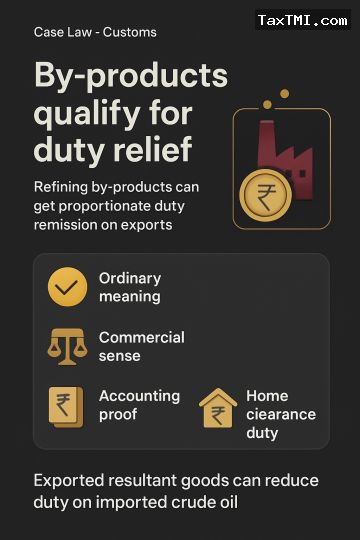
By-products emerging from crude oil refining were treated as "resultant goods" under the MOOWR framework because the expression is to be understood in its ordinary and commercial sense, covering all goods produced in the manufacturing process and not only the principal output. The advance ruling also accepted that export of such resultant goods permits proportionate remission of duty on the imported crude oils attributable to the exported output, with correlation to be shown through proper accounting, yield ratios and material balance. Goods cleared for home consumption remain liable only to the corresponding attributable duty. The application was held maintainable as it concerned duty liability and remission under the warehousing scheme.
By-products emerging from crude oil refining were treated as "resultant goods" under the MOOWR framework because the expression is to be understood in its ordinary and commercial sense, covering all goods produced in the manufacturing process and not only the principal output. The advance ruling also accepted that export of such resultant goods permits proportionate remission of duty on the imported crude oils attributable to the exported output, with correlation to be shown through proper accounting, yield ratios and material balance. Goods cleared for home consumption remain liable only to the corresponding attributable duty. The application was held maintainable as it concerned duty liability and remission under the warehousing scheme.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918