Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
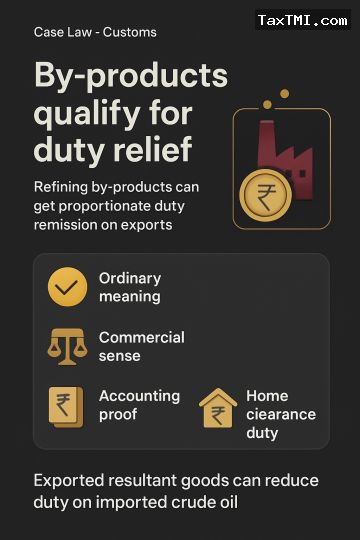
By-products emerging from crude oil refining were treated as "resultant goods" under the MOOWR framework because the expression is to be understood in its ordinary and commercial sense, covering all goods produced in the manufacturing process and not only the principal output. The advance ruling also accepted that export of such resultant goods permits proportionate remission of duty on the imported crude oils attributable to the exported output, with correlation to be shown through proper accounting, yield ratios and material balance. Goods cleared for home consumption remain liable only to the corresponding attributable duty. The application was held maintainable as it concerned duty liability and remission under the warehousing scheme.
By-products emerging from crude oil refining were treated as "resultant goods" under the MOOWR framework because the expression is to be understood in its ordinary and commercial sense, covering all goods produced in the manufacturing process and not only the principal output. The advance ruling also accepted that export of such resultant goods permits proportionate remission of duty on the imported crude oils attributable to the exported output, with correlation to be shown through proper accounting, yield ratios and material balance. Goods cleared for home consumption remain liable only to the corresponding attributable duty. The application was held maintainable as it concerned duty liability and remission under the warehousing scheme.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI