Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
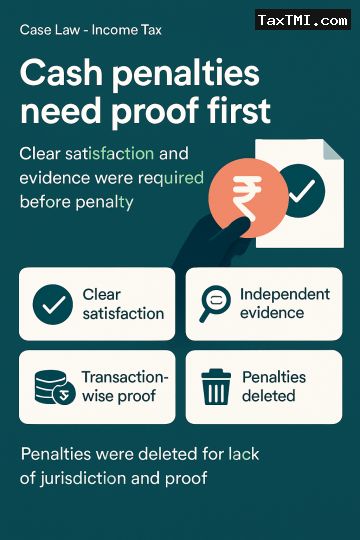
Recording clear satisfaction in the assessment order was treated as a jurisdictional requirement before penalty for alleged cash receipts could be initiated; a bare reference to penalty proceedings was insufficient. The alleged contravention also had to be proved transaction-wise with cogent independent evidence identifying the payer, payee, amount, date and threshold breach, and seized data or estimated income alone were not enough in quasi-criminal penalty proceedings. The levy was further found unreasonable where the assessee had disclosed additional income and tax was already paid, so the penalties were deleted for want of jurisdiction and proof.
Recording clear satisfaction in the assessment order was treated as a jurisdictional requirement before penalty for alleged cash receipts could be initiated; a bare reference to penalty proceedings was insufficient. The alleged contravention also had to be proved transaction-wise with cogent independent evidence identifying the payer, payee, amount, date and threshold breach, and seized data or estimated income alone were not enough in quasi-criminal penalty proceedings. The levy was further found unreasonable where the assessee had disclosed additional income and tax was already paid, so the penalties were deleted for want of jurisdiction and proof.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI