Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
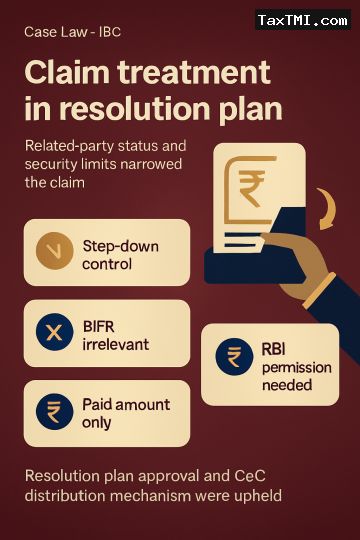
Related party status, guarantee claim limits and security-interest restrictions determined the treatment of the appellant's CIRP claim. The tribunal found related party status on the basis of step-down subsidiary control, and treated prior BIFR status as irrelevant. It upheld rejection of the HSBC-related secured claim because the payer/guarantor had no assignable debt. A non-resident could not acquire security in the corporate debtor's immovable property without RBI permission under FERA, so secured-creditor status was denied for that asset class. The admitted guarantee claim was confined to the amount actually paid, and post-facto RBI approval could not enlarge it. Approval of the resolution plan and CoC distribution mechanism was sustained.
Related party status, guarantee claim limits and security-interest restrictions determined the treatment of the appellant's CIRP claim. The tribunal found related party status on the basis of step-down subsidiary control, and treated prior BIFR status as irrelevant. It upheld rejection of the HSBC-related secured claim because the payer/guarantor had no assignable debt. A non-resident could not acquire security in the corporate debtor's immovable property without RBI permission under FERA, so secured-creditor status was denied for that asset class. The admitted guarantee claim was confined to the amount actually paid, and post-facto RBI approval could not enlarge it. Approval of the resolution plan and CoC distribution mechanism was sustained.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI