Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
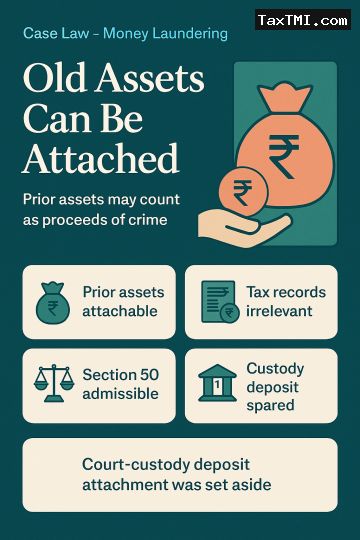
Properties acquired before the scheduled offence could still be attached as value of proceeds of crime where tainted funds were used to repay loans or the direct proceeds were unavailable; disclosure of the assets in income-tax records did not alter the alleged tainted character of the funds. The Tribunal also held that statements recorded under Section 50 of PMLA are admissible in proceedings under the Act and may be relied on even if later disputed, where supporting material exists. However, provisional attachment of a security deposit already in Judicial Magistrate custody failed because reasons to believe under Section 5(1) must include a real apprehension of concealment, transfer, or frustration of confiscation; that attachment was set aside.
Properties acquired before the scheduled offence could still be attached as value of proceeds of crime where tainted funds were used to repay loans or the direct proceeds were unavailable; disclosure of the assets in income-tax records did not alter the alleged tainted character of the funds. The Tribunal also held that statements recorded under Section 50 of PMLA are admissible in proceedings under the Act and may be relied on even if later disputed, where supporting material exists. However, provisional attachment of a security deposit already in Judicial Magistrate custody failed because reasons to believe under Section 5(1) must include a real apprehension of concealment, transfer, or frustration of confiscation; that attachment was set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI