Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
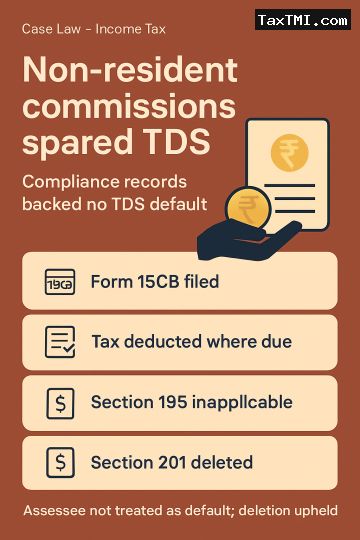
Payments to non-residents for travel-agent and hotel-booking commissions did not attract TDS on the facts found, because the assessee had furnished Form 15CB for each transaction, deducted and deposited tax wherever applicable, and filed the TDS returns. The HC accepted the Tribunal's finding that the commission payments to banks, credit card companies, travel agents and related service providers were not sums liable for deduction under section 195 in those circumstances. Since the assessee had complied with the TDS requirements and there was no adverse reporting in Form 3CD on non-deduction, it could not be treated as an assessee in default under section 201, and the deletion of section 201(1) and 201(1A) action was upheld.
Payments to non-residents for travel-agent and hotel-booking commissions did not attract TDS on the facts found, because the assessee had furnished Form 15CB for each transaction, deducted and deposited tax wherever applicable, and filed the TDS returns. The HC accepted the Tribunal's finding that the commission payments to banks, credit card companies, travel agents and related service providers were not sums liable for deduction under section 195 in those circumstances. Since the assessee had complied with the TDS requirements and there was no adverse reporting in Form 3CD on non-deduction, it could not be treated as an assessee in default under section 201, and the deletion of section 201(1) and 201(1A) action was upheld.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI