Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
Foreign exchange loss arising from External Commercial...
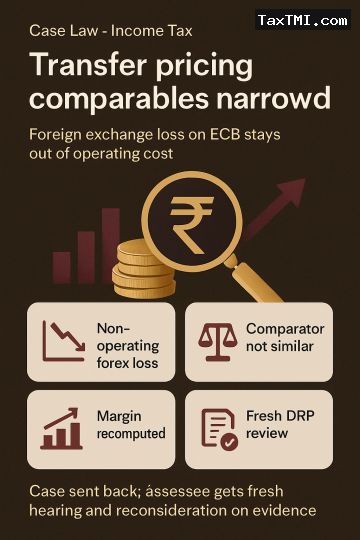
Transfer pricing comparability under TNMM: foreign exchange loss on ECB excluded from operating cost, and a functionally dissimilar comparator removed.
Contents
Summary
Note
Bookmark
Share
✓ Copied successfully !
Print
Print Options
For full text, please login
Login to TaxTMI
Verification Pending
The Email Id has not been verified. Click on the link we have sent on
Foreign exchange loss arising from External Commercial Borrowings and capital expenditure is treated as non-operating for TNMM PLI computation, because the loss is linked to financing and capital account items rather than ordinary business operations; the margin must therefore be recomputed after excluding that item. A comparable engaged in auto components and renewable energy was found functionally dissimilar to an assessee manufacturing hydraulic motors and motor components, so it was excluded from the comparables set. Disallowances based on additional evidence were remitted for fresh examination because the evidentiary material filed before the DRP was not properly considered, and the assessee must be given a reasonable opportunity.
Foreign exchange loss arising from External Commercial Borrowings and capital expenditure is treated as non-operating for TNMM PLI computation, because the loss is linked to financing and capital account items rather than ordinary business operations; the margin must therefore be recomputed after excluding that item. A comparable engaged in auto components and renewable energy was found functionally dissimilar to an assessee manufacturing hydraulic motors and motor components, so it was excluded from the comparables set. Disallowances based on additional evidence were remitted for fresh examination because the evidentiary material filed before the DRP was not properly considered, and the assessee must be given a reasonable opportunity.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI