Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
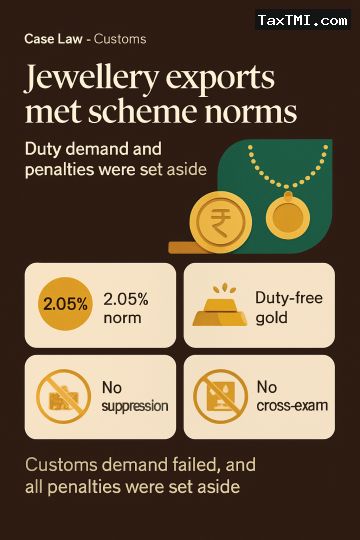
Jewellery exported under the Replenishment Scheme was treated as manufactured through a fully mechanised process, so the applicable value addition norm was 2.05% rather than 3.5%. On that basis, the exporter was eligible to procure duty-free gold and the customs duty demand on the nominated agency failed. The Tribunal also held that the extended limitation period was unavailable because the shipping bills and provisional invoices disclosed the relevant particulars, including value addition, weights and rate, so suppression of facts and intent to evade duty were not proved. Penalties on the nominated agency, exporter and partner were set aside, including because the job worker's statement could not be relied on without cross-examination.
Jewellery exported under the Replenishment Scheme was treated as manufactured through a fully mechanised process, so the applicable value addition norm was 2.05% rather than 3.5%. On that basis, the exporter was eligible to procure duty-free gold and the customs duty demand on the nominated agency failed. The Tribunal also held that the extended limitation period was unavailable because the shipping bills and provisional invoices disclosed the relevant particulars, including value addition, weights and rate, so suppression of facts and intent to evade duty were not proved. Penalties on the nominated agency, exporter and partner were set aside, including because the job worker's statement could not be relied on without cross-examination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI