Political contribution deductions require genuine transactions; banking records and party registration alone cannot defeat evidence of accommodation e...
Post-death GST liability permits fresh proceedings against legal representatives, while discontinued-business recovery remains limited to the inherite...
Non-confirmation of FEMA seizure prevents adjudicators from overriding pending appellate findings on recorded reasons and suspected foreign asset hold...
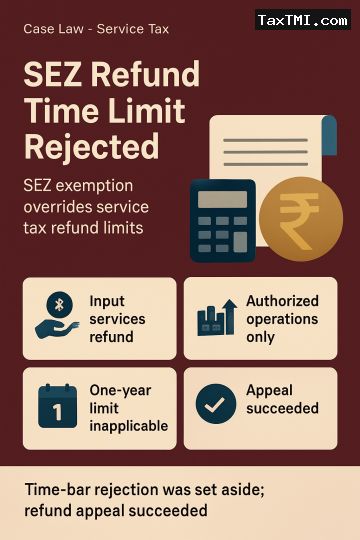
For an SEZ unit claiming refund of service tax on input services used for authorised operations, the SEZ Act's exemption scheme prevails over service tax notifications issued under the Finance Act, 1994. The Tribunal applied the settled position that section 26 of the SEZ Act and the SEZ Rules govern the exemption, and that inconsistent notification-based restrictions cannot be imposed on SEZ refunds. Accordingly, the one-year limitation in the service tax notifications was held inapplicable, the rejection as time-barred was set aside, and the refund appeal succeeded with consequential relief.
For an SEZ unit claiming refund of service tax on input services used for authorised operations, the SEZ Act's exemption scheme prevails over service tax notifications issued under the Finance Act, 1994. The Tribunal applied the settled position that section 26 of the SEZ Act and the SEZ Rules govern the exemption, and that inconsistent notification-based restrictions cannot be imposed on SEZ refunds. Accordingly, the one-year limitation in the service tax notifications was held inapplicable, the rejection as time-barred was set aside, and the refund appeal succeeded with consequential relief.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI