Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
    Case Laws Income Tax
    TNMM Comparability: Operating Items, Search Matrix and Functional Analysis under Rule 10B
    Case Laws Customs
    Validity of Gold Seizure under Section 110 and the Conditional Reverse Burden under Section 123 of t...
    Case Laws Income Tax
    Deduction under Section 80GGC: Genuineness of Political Contributions and Evidentiary Burden
    Post-Death Determination of GST Liability and Estate-Limited Recovery from Legal Heirs
    Non-Confirmation of Seizure under Section 37A of FEMA and the Requirement of Recorded Reasons to Bel...
    Case Laws Companies Law
    Oppression and Mismanagement Proceedings under Sections 241 and 242: Corporate Authority During Pend...
    Case Laws Benami Property
    Benami Claims in Self-Acquired Property: Rejection of Plaint and the Limits of the Fiduciary-Capacit...
    Case Laws Income Tax
    Reopening of Assessment under Sections 147 and 148: Reason to Believe, Tangible Material and Change ...
    Case Laws Income Tax
    Penalty under Section 270A on Disallowance of Political Donation Deduction under Section 80GGC
    Case Laws Income Tax
    Conditional Registration under Section 12AB and the Limits of Commissioner's Statutory Powers
    Case Laws Customs
    Transaction Value, Rule 12 and Enhancement Based on Consent Letters in Customs Valuation: Limits of ...
    GST on Assignment of Leasehold Rights: Distinguishing Transfer of Immovable Property from Supply of ...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.
Case Laws Income Tax
Show AI Summary
TNMM comparability requires consistent operating-cost treatment and FAR-based selection, while search matrices cannot replace evidence-led functional analysis.
TNMM requires consistent computation of operating profit and operating cost for the tested party and comparables. A provision for doubtful debts connected with sales and trade receivables may be an operating expense, as may routine business levies; income-tax on profits remains excluded. A search matrix is a disciplined evidentiary tool, not a statutory bar to an out-of-matrix comparable. Inclusion requires proof of functional fit, filter satisfaction and reasons for its absence, while rejection cannot rest solely on matrix absence. FAR analysis, segmental reliability and material scale differences govern comparability.
Case Laws Customs
Show AI Summary
Reasonable belief in gold seizure requires recorded objective grounds before the reverse burden for smuggling can arise.
Gold seizure under Section 110 requires the proper officer to hold, before seizure, objectively supportable reasons to believe that goods are liable to confiscation. For gold, Section 123 shifts the burden of disproving smuggling only after a lawful seizure made in reasonable belief that the gold is smuggled. A general panchnama recital, foreign markings, high purity, or an uncorroborated retracted statement cannot alone establish that foundation. Reasons must exist contemporaneously and cannot be supplied retrospectively through later investigation.
Case Laws Income Tax
Show AI Summary
Political contribution deductions require proof that payments are genuine, not merely bank transfers, receipts, and recipient registration.
Registration of the recipient political party, non-cash remittance, banking records and donation receipts are necessary evidentiary facts for a political-contribution deduction, but do not conclusively prove a genuine contribution. Where credible material indicates an accommodation-entry arrangement involving return of funds through intermediaries, the claimant must substantiate the transaction and address taxpayer-specific circumstances. General allegations about a recipient cannot alone displace a claim without a sufficient nexus to the taxpayer's own payment. Penalty initiation requires separate determination of under-reporting or misreporting and a reasonable opportunity of hearing.
Case Laws GST
Show AI Summary
Estate-limited GST recovery permits post-death assessment of legal representatives while protecting heirs' independent assets after business discontinuance.
Section 93 permits post-death GST determination against a legal representative where a liable person dies. If the business is discontinued, tax, interest and penalty may be recovered only from the deceased's inherited estate and only within its capacity; the heir's independent assets remain outside that limit. Proceedings may be initiated without a pre-death notice, but must be addressed to the legal representative in that capacity, follow the applicable adjudication process, and provide hearing and a reasoned order.
Case Laws FEMA
Show AI Summary
Recorded reasons to believe govern foreign-asset seizure; non-confirmation requires appellate resolution before contradictory adjudication proceeds.
Section 37A permits seizure of equivalent domestic assets only where the authorised officer records written reasons to believe that foreign assets are held in contravention of FEMA. The competent authority must examine the material after hearing both sides and either confirm or set aside seizure. A reasoned non-confirmation based on an absent statutory threshold is substantive on seizure, though it does not finally decide the underlying contravention. Pending appeal, the adjudicating authority cannot displace that finding or adopt a contrary premise; Section 37A(4) applies only to confirmed seizure.
Case Laws Companies Law
Show AI Summary
Unstayed tribunal dismissal leaves former directors without corporate authority while banks follow valid company instructions amid management disputes.
Where an oppression and mismanagement petition has been dismissed, a pending appeal without an appellate stay does not itself restore a former director's authority or suspend the dismissal's operative effect. Sections 241 and 242 require statutory prejudice and prescribed Tribunal findings; procedural irregularities in director removal may be relevant but do not alone establish oppression. Banks should ordinarily follow formally authorised company instructions rather than decide unresolved management disputes, unless a binding judicial or statutory restraint applies.
Case Laws Benami Property
Show AI Summary
Benami property claims cannot be recast through wills or employment-based trust when pleadings assert beneficial ownership.
Benami-property claims based on a claimant's payment for property titled in another person's name may fall within the statutory definition when the property is alleged to be held for that claimant's benefit. A Will, succession claim, or other later instrument does not provide an independent basis of title where the pleaded foundation is restoration of beneficial ownership. The statutory scheme prohibits benami arrangements, bars enforcement of claimed beneficial ownership, and treats prohibited re-transfers as invalid; self-acquired title in the named holder's name does not displace the pleaded funding arrangement.
Case Laws Income Tax
Show AI Summary
Reason to believe in reassessment requires tangible material, a live nexus, and recorded reasons; review of examined issues is barred.
Income-tax reassessment under Sections 147 and 148 is permissible only where recorded reasons, assessed at the time of notice, disclose a bona fide reason to believe that chargeable income escaped assessment. Final proof is unnecessary at that stage, but relevant tangible material must have a rational, live link to escapement. Reopening cannot be used to review an issue consciously examined and decided in the original scrutiny; nor can later or extraneous material supplement the recorded reasons. The taxpayer may seek the reasons, file focused objections, and receive a speaking order before reassessment continues.
Case Laws Income Tax
Show AI Summary
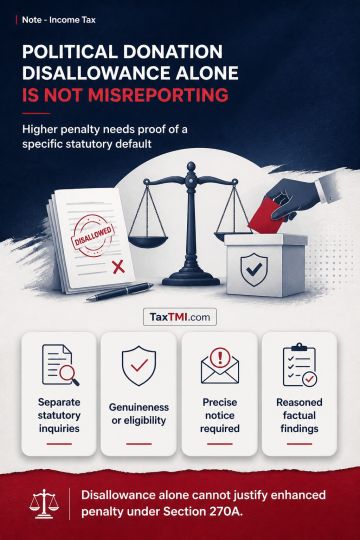
Political-donation deduction disallowance does not itself establish misreporting; enhanced penalty requires proof of a specific statutory default.
Disallowance of a political-contribution deduction under Section 80GGC and imposition of penalty under Section 270A are separate statutory inquiries. An adverse finding on genuineness or eligibility may raise assessed or reassessed income, but cannot alone establish misreporting. Enhanced penalty requires proof that the taxpayer's conduct falls within a specific Section 270A(9) category, supported by a precise notice and reasoned factual findings.
Case Laws Income Tax
Show AI Summary
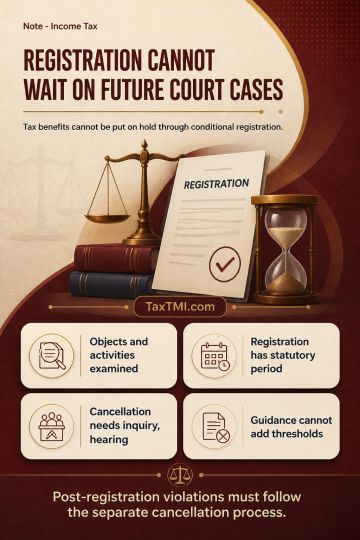
Conditional charitable registration cannot suspend tax benefits pending litigation outside the statutory grant and cancellation framework.
Section 12AB permits the authority, after inquiry into objects, genuine activities and material legal compliance, to grant registration for the statutory period or reject the application. It does not create a contingent form of registration whose tax consequences await future litigation. Post-registration violations must be addressed through the separate cancellation process, requiring inquiry and hearing. Conditions in prescribed forms or administrative guidance may operationalise statutory duties but cannot create extra-statutory eligibility thresholds, future-conduct obligations or anticipatory cancellation consequences. Binding jurisdictional rulings remain applicable unless stayed, modified or reversed.
Case Laws Customs
Show AI Summary
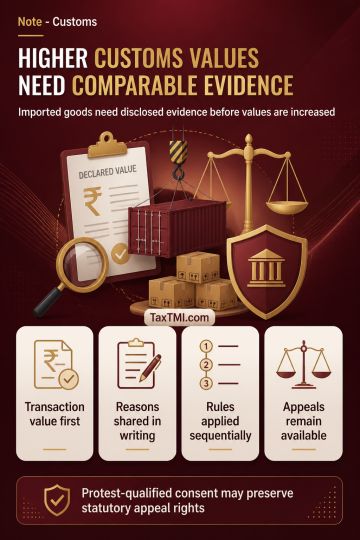
Transaction value reassessment requires disclosed comparable evidence, while protest-qualified consent preserves appellate rights against enhanced customs valuation.
Transaction value under Section 14 and Rule 3 is the primary basis for valuing imported goods. Rule 12 permits rejection only where an objectively sustainable reasonable doubt persists after considering further information; on request, the grounds must be disclosed in writing and a hearing afforded. Redetermination must follow Rules 4 to 9 sequentially and rely on demonstrably comparable import data. Written acceptance of reassessment may dispense with a speaking order under Section 17(5), but protest-qualified or provisional-clearance correspondence may preserve the statutory right to appeal.
Case Laws GST
Show AI Summary
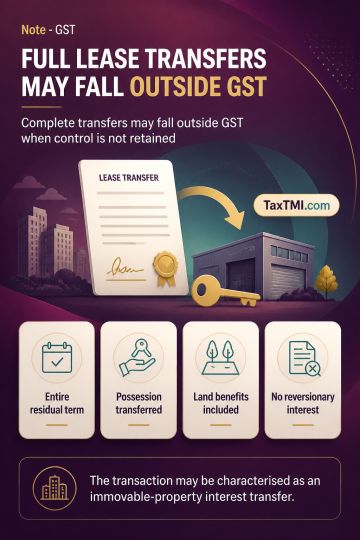
Leasehold rights assignment may fall outside GST when the lessee permanently transfers the entire proprietary estate.
GST treatment of assignment of leasehold rights turns on whether the lessee has made a complete transfer of its existing estate or continues to provide occupation or enjoyment. Where the assignor transfers the whole residual term, possession, building and associated rights, retains no reversionary or controlling interest, and the assignee succeeds directly to obligations towards the original lessor, the transaction may be characterised as transfer of benefits arising out of land rather than a supply of services. Labels such as premium, salami or transfer fee are not conclusive.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Back

All TMI Notes

Alleged Re-use of E-Way Bills under Section 129: Evidentiary Burden in Detention Proceedings

29 October, 2026

Contents
Circulars
Acts
Rules & Regulations
Plus +
Summary
Note

Note

-

Bookmark

Print

Print

This is a neutral professional article. The judgment is analysed in the context of its factual background, issues framed, and conclusions reached by the Court.

2026 (9) TMI 1491 - GSTAT LUCKNOW

At a Glance

The central question in 2026 (9) TMI 1491 - GSTAT LUCKNOW was whether toll-plaza movement data and photographs, when read with a later movement of the same vehicle under the same invoices and e-way bills, were sufficient to establish re-use of those documents and an attempted evasion of tax.

  • Section 129 is attracted where goods are transported in contravention of the Act or the Rules; it does not permit a demand to rest on an unproved factual assumption.
  • In an alleged e-way bill re-use case, the revenue authority must establish, by cogent material, that the intercepted goods were the same goods that had already been transported under the disputed documents.
  • Toll records, vehicle-location data and photographs can be relevant evidence. Their probative value, however, depends upon whether they establish the identity of the goods and a completed earlier movement, rather than merely repeated movement of a vehicle carrying outwardly similar goods.
  • Valid invoices and e-way bills do not conclusively disprove re-use. Conversely, their existence, coupled with matching goods and absence of discrepancies, requires the authority to investigate and prove the alleged contravention rather than presume it.
  • The decision is fact-specific. It does not lay down that every documentary lapse is immaterial, particularly where prescribed documents were not available at interception or the e-way bill had expired.

Background & Context

The taxpayer's goods were intercepted while being carried under invoices and e-way bills. The department relied on toll-plaza records and photographs to infer that the same vehicle had made an earlier outward journey carrying the same goods, returned empty, and later again transported goods under the same invoices and e-way bills. On that basis, it treated the later movement as a re-transportation of goods already moved and imposed tax and penalty under Section 129.

The taxpayer's case was that the earlier journey concerned a different consignment. It relied on a driver's explanation and documents relating to an earlier movement of cotton cuttings. It also contended that the physical verification disclosed no discrepancy in the description, quantity, value or ownership of the intercepted goods and that the invoices and e-way bills were valid.

The Tribunal allowed the appeal and set aside the appellate order. Its decisive reasoning was evidentiary: the allegation that the goods had been re-transported rested principally on an inference from the vehicle's prior location and photographs. There was no independent, cogent proof that the very goods covered by the disputed invoices and e-way bills had completed an earlier journey or had been delivered. The Tribunal further noted that the taxpayer's explanation regarding a different earlier consignment had not been verified by the revenue authority.

The result was not founded simply on the existence of valid transport documents. Rather, it followed from the failure to establish the factual premise necessary for treating those documents as having been used earlier for the same goods. Any amount deposited in consequence of the detention and penalty proceedings was directed to be refunded in accordance with law.

Key Issues / Provisions

Statutory trigger for inspection and detention

Section 68 of the Central Goods and Services Tax Act, 2017 permits the Government to require the person in charge of a conveyance to carry prescribed documents and devices. Under Section 68(3), where a conveyance is intercepted, the proper officer may require production of those documents and devices for verification, and the person in charge must produce them and permit inspection of the goods.

Section 129 of the Central Goods and Services Tax Act, 2017 employs the operative condition that goods are transported or stored in transit "in contravention of the provisions of this Act or the rules made thereunder." Thus, detention or seizure must be anchored in an identifiable contravention. Section 129(3), in the text reproduced here, requires the proper officer to issue a notice within seven days of detention or seizure, specifying the penalty payable, and thereafter pass an order within seven days from service of that notice. Section 129(4) prohibits determination of penalty without an opportunity of being heard.

The exact statutory version applied to the disputed movement is not reproduced in the decision. The evidentiary reasoning of the Tribunal nevertheless remains directed to the foundational question whether a contravention, namely re-use of the transport documents for the same goods, had been established.

E-way bill and carriage requirements

Rule 138 of the Central Goods and Services Tax Rules, 2017 requires a registered person causing movement of goods of consignment value exceeding the stated threshold to furnish prescribed information in Part A of FORM GST EWB-01 "before commencement of such movement." For movement by road, Rule 138(2) requires furnishing Part B, while Explanation 2 to Rule 138(3) states that an e-way bill is not valid for road movement unless Part B information has been furnished, subject to the stated exceptions.

Rule 138A complements Rule 138. The person in charge of the conveyance must carry the invoice, bill of supply or delivery challan, as applicable, and a physical or electronic copy or number of the e-way bill. The statutory scheme therefore treats the invoice and e-way bill as material tools of verification; it does not dispense with an inquiry into whether the documents actually correspond to the goods and movement in question.

Verification and recording safeguards

Rule 138B authorises interception to verify the e-way bill and permits physical verification by the authorised proper officer. Its proviso permits physical verification by another officer only upon specific information of tax evasion and necessary approval. Under Rule 138C, a summary inspection report must be recorded in Part A of FORM GST EWB-03 within twenty-four hours, with the final report ordinarily recorded in Part B within three days. These requirements reinforce that inspection must produce a documented factual basis for further coercive action.

Circular No. 41/15/2018-GST similarly contemplates verification before detention. Where no prima facie discrepancy is found, the conveyance is to be allowed to proceed. Where inspection is undertaken, the process contemplates a statement in FORM GST MOV-01, an inspection order in FORM GST MOV-02, a physical-verification report in FORM GST MOV-04, and release in FORM GST MOV-05 if no discrepancy is found. Detention under Section 129 is contemplated through FORM GST MOV-06 and notice in FORM GST MOV-07; objections require a speaking order in FORM GST MOV-09.

Detailed Analysis

Re-use is an allegation of fact requiring a complete evidentiary link

The Tribunal distinguished suspicion arising from vehicle movement from proof of re-use of an e-way bill. Repeated movement of a vehicle, even with a visually similar load, does not by itself prove that the same consignment was first transported, delivered, returned and then carried again under the same documents. The evidentiary gap becomes material where the taxpayer offers a competing explanation that the earlier movement concerned different goods.

In the facts examined, the departmental case was built upon toll timings, movement records and photographs. The Tribunal accepted that this material was relevant, but found it insufficient to establish that the disputed goods had already completed an earlier journey. It also found that the revenue authority had not verified the taxpayer's explanation that the earlier journey involved cotton cuttings under different documentation. The appellate conclusion that intention to evade tax was "automatically proved" by the asserted re-transportation was therefore unsustainable, because the asserted re-transportation itself had not been proved.

The practical distinction is important. Toll data may prove that a vehicle passed a particular point at a particular time. A photograph may indicate the presence of a load. Neither item automatically proves the identity of a particular taxable consignment, prior delivery to the named recipient, or re-use of a particular invoice and e-way bill. Those additional propositions require corroboration.

Positive evidence and the initial evidentiary burden

2023 (9) TMI 267 - ALLAHABAD HIGH COURT directly addresses alleged re-use of an e-way bill. It holds that, where re-use is alleged, the initial burden lies upon the seizing authority to lead positive evidence that the goods had been transported earlier using the same e-way bill. The existence of an e-way bill does not by itself permit a presumption of an earlier transaction. The authority must undertake or rely upon corroborative inquiry or material; a bare conclusion in the seizure order cannot sustain tax and penalty.

This authority closely supports the Tribunal's approach. Both decisions reject the substitution of assertion for proof in a re-use allegation. The Tribunal's reasoning adds an important factual dimension: where the taxpayer provides an alternate account of the vehicle's prior movement, the authority must test that account through appropriate verification rather than treat the unexplored explanation as proof of evasion.

Vehicle movement may justify inquiry, but not mechanical detention

2019 (11) TMI 473 - KERALA HIGH COURT concerned a different route taken by a vehicle carrying goods under a valid e-way bill. It held that detention cannot be automatic merely because the driver chose an alternate route to the declared destination. A presumption may arise only where the vehicle is found on a road stretch or travelling in a direction inconsistent with reaching the stated destination. The authority is relevant because it insists that vehicle-location facts must be read in their actual commercial and geographical context.

Applied to a re-use allegation, this reasoning means that toll movement data is not self-explanatory. The officer must establish why the route, direction, timing and loading pattern reasonably point to an unlawful movement of the particular consignment, rather than another lawful journey by the same vehicle.

Validity of documents and the limits of inference

2024 (8) TMI 772 - ALLAHABAD HIGH COURT held that where an e-way bill was produced after detention but before the seizure order, and no discrepancy in that document was identified, the documentary defect stood cured on the facts. The authority also noted that the department could verify the transaction through other available investigatory measures. Its relevance here lies in the proposition that a presumption of evasion should not survive unexamined where subsequently available material supports the claimed transaction and no discrepancy is demonstrated.

Conversely, 2024 (2) TMI 1128 - ALLAHABAD HIGH COURT illustrates the boundary of this principle. There, neither invoice nor e-way bill accompanied the goods at interception. The Court held that the absence of both documents was not merely technical, raised a presumption of intent to evade tax, and shifted the evidentiary burden to the owner or transporter. Later production of documents did not by itself remove liability where that presumption remained unrebutted.

The two authorities show why the Tribunal's decision should not be understood as a general immunity from Section 129. In the present case, the goods were accompanied by invoices and e-way bills, and no discrepancy in description, quantity, value or ownership was established. The controversy was not an admitted absence of documents at interception; it was the department's affirmative allegation that validly produced documents had been re-used. That allegation required proof.

Minor documentary errors are distinct from alleged re-use

Circular No. 64/38/2018-GST draws a statutory-administrative distinction between no valid e-way bill and specified minor errors where an invoice and e-way bill do accompany the goods. It states that Section 129 proceedings may not be initiated for stated errors, including an error in one or two digits or characters of the vehicle number; the prescribed response in those situations is the specified token penalty under Section 125.

2024 (7) TMI 370 - GUJARAT HIGH COURT applied that distinction where the invoice and e-way bill otherwise corresponded to the goods and a vehicle-number mismatch resulted from a bona fide replacement vehicle. It held that Section 129 detention was not justified on those facts. Although a vehicle-number mismatch is not the same as alleged re-use, the decision confirms the need to differentiate a genuine contravention from a circumstance that is compatible with a documented, bona fide movement.

No uniform rule on every e-way bill irregularity

2024 (2) TMI 189 - Supreme Court concerned movement after expiry of an e-way bill. The Court accepted that there was no live e-way bill and that a fresh bill ought to have been generated if transportation did not occur within the original validity period. The tax demand was upheld, while the penalty was reduced on the particular facts through an order expressly stated not to be a precedent. This outcome is materially different from an unproved allegation of re-use, but it demonstrates that a clear and admitted documentary non-compliance may attract consequences even where the goods belong to the taxpayer.

The supplied authorities therefore reveal a fact-sensitive framework. A valid document does not foreclose inquiry. Equally, a suspicion born from vehicle data, route variation or document appearance cannot replace proof of the precise contravention alleged. The Tribunal's ruling rests on the latter proposition.

Practical Implications

For revenue authorities, a sustainable re-use case should establish more than a sequence of vehicle movements. The material should identify the earlier consignment, connect it to the disputed invoice and e-way bill, and show why the intercepted goods are the same goods already transported. Independent verification from the alleged purchaser, consignor, transporter, loading or unloading records, or other contemporaneous material may be significant. If the taxpayer claims a different prior consignment, the claim should be investigated and the outcome recorded in the order.

For taxpayers and transporters, the immediate response to interception should preserve the evidentiary trail. This includes invoices, e-way bills, consignment notes, loading records, delivery acknowledgements, toll records, driver statements, records of other consignments carried by the same vehicle, and material explaining timing or route. An explanation resting only on a driver's assertion may be vulnerable; contemporaneous, independent documents make the explanation capable of verification.

Procedurally, objections to a notice under Section 129 should address each alleged link in the departmental inference: identity of goods, timing, prior delivery, route, vehicle loading, and document linkage. The objection should also require a reasoned response to the taxpayer's evidence. Under Rule 142 of the Central Goods and Services Tax Rules, 2017, a summary of a notice under Section 129 is to be served electronically in FORM GST DRC-01, and a summary of the order is to be uploaded in FORM GST DRC-07. These electronic steps operate alongside the inspection and detention record contemplated by the MOV forms.

Failure to respond at the earliest stage carries practical risk, particularly because an officer may decide on available material. Yet, as this decision demonstrates, an ex parte or inadequately contested proceeding does not dispense with the revenue authority's obligation to establish the factual basis of an allegation of re-use before tax and penalty are confirmed.

Key Takeaways

  • An allegation that invoices and e-way bills were used more than once is not proved merely because the same vehicle made multiple movements or carried apparently similar goods.
  • The core evidentiary question is whether the department can establish that the intercepted consignment is the very consignment previously transported under the disputed documents.
  • Toll-plaza data and photographs are relevant leads, but require corroboration capable of proving identity of goods and an earlier completed transaction.
  • Where documents accompany the goods and physical verification shows no mismatch, the authority must give a reasoned account of why those documents are nevertheless treated as re-used.
  • Cases involving complete absence of invoices and e-way bills, or an admittedly expired e-way bill, stand on a different footing and may support statutory action depending on their facts.
  • The legal discipline emerging from the decision is not that suspicion is irrelevant, but that suspicion must mature into proof before it can sustain detention, tax and penalty for alleged tax evasion.


Full Text:

2026 (9) TMI 1491 - GSTAT LUCKNOW

Topics

Acts Income Tax