Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
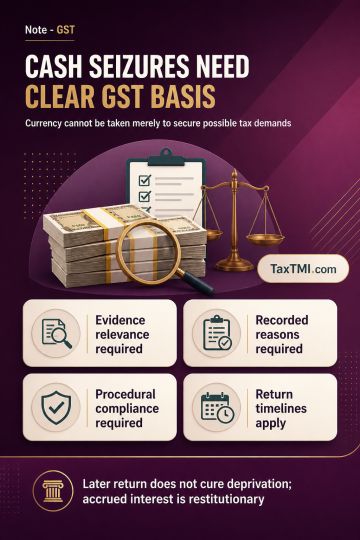
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
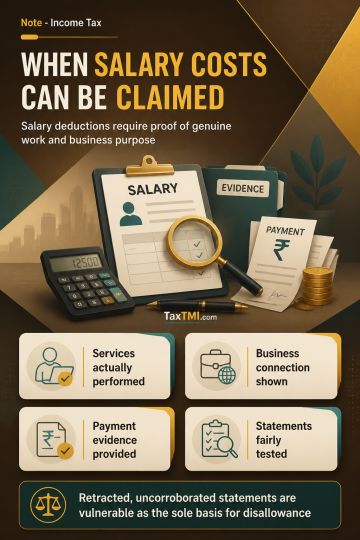
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
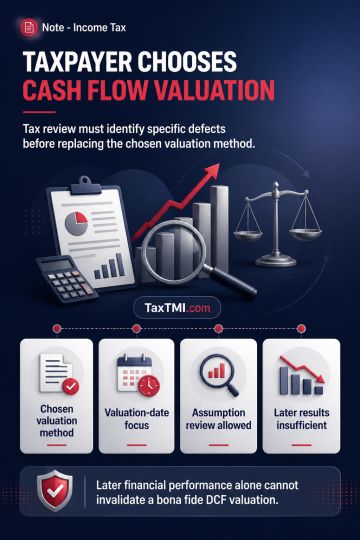
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
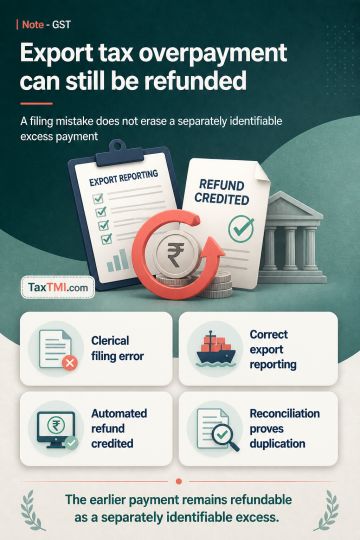
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
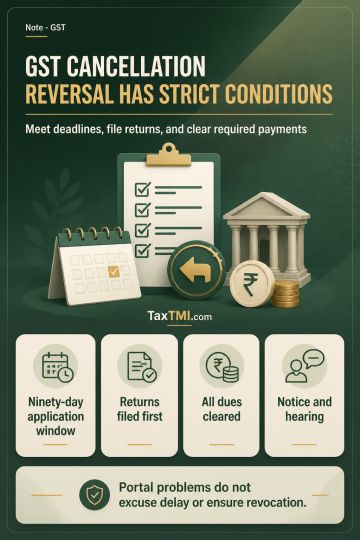
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
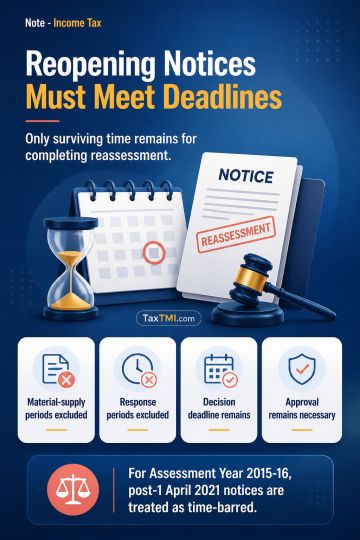
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
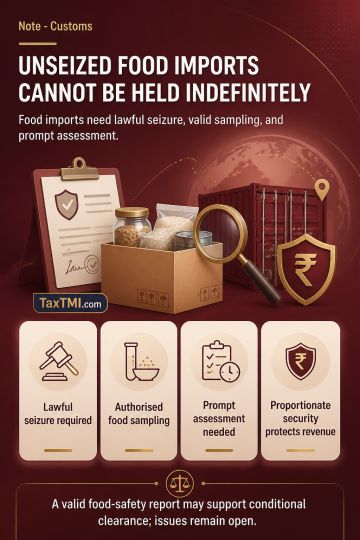
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
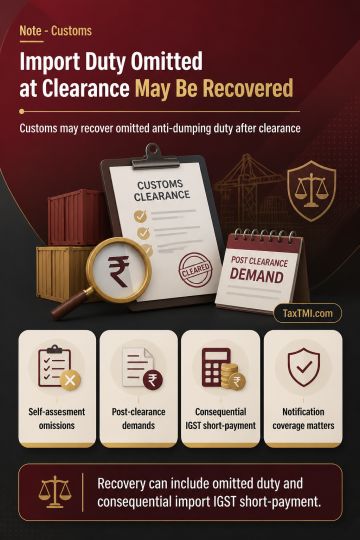
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Section 68, Loan Credits, and the Limits of Suspicion: Evidentiary Discipline in Search-Linked Assessments

29 December, 2025

Contents
Acts
Rules & Regulations
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Deciphering Legal Judgments: A Comprehensive Analysis of Judgment

Reported as:

2025 (12) TMI 780 - ITAT DELHI

Introduction

The decision of the Income Tax Appellate Tribunal, Delhi  concerns a cluster of Revenue appeals arising from appellate orders u/s 250 of the Income-tax Act, 1961 ("the Act"). The core controversy across years and entities was uniform: whether unsecured loans received from a non-banking financial company ("NBFC lender") could be treated as unexplained cash credits u/s 68 (with consequential tax implications u/s 115BBE), largely on the basis of (i) statements recorded in earlier search proceedings involving alleged entry providers, and (ii) a Ministry of Finance press release allegedly "red-flagging" the lender as a shell entity.

The Tribunal treated one year as the "lead" matter and disposed the remaining appeals by applying the same reasoning, also extending the consequence to associated interest disallowances. The ruling is significant within the broader legal framework governing section 68 because it revisits three recurring fault-lines in search-linked assessments and reassessments: (a) the evidentiary standard for branding bank-routed loans as accommodation entries, (b) the limits of the "source of source" enquiry for loan credits in years prior to the Finance Act, 2022 amendments, and (c) procedural fairness when the first appellate authority conducts independent enquiries u/s 250(4) vis-`a-vis Rule 46A.

Key Legal Issues

  • Section 68 test for unsecured loans: Whether the assessee companies discharged the burden of proving identity, genuineness, and creditworthiness of the lender, and whether the Assessing Officer ("AO") had legally sustainable grounds to reject that explanation.

  • Reliance on statements without corroboration: Whether additions could rest substantially on third-party statements (including statements recorded years earlier) without contemporaneous incriminating material or transaction-specific evidence.

  • "Source of source" for loan credits: Whether the AO was entitled (for the relevant assessment years) to insist on proof of the lender's upstream sources, and whether treating repayments of earlier advances as "fresh borrowings" was legally and factually correct.

  • Use of administrative press release as substantive evidence: Whether a press release branding entities as shell/high-risk could, by itself, justify section 68 additions absent regulatory or investigative confirmation.

  • Rule 46A and section 250(4): Whether the first appellate authority violated Rule 46A by considering material obtained during appellate proceedings, and whether the AO was afforded adequate opportunity to respond.

  • Effect of loan repayment and double taxation concerns: Whether repayment in later years and/or alleged taxation of the same credits in the lender's hands undermined additions in the borrowers' hands.

Detailed Issue-wise Analysis

1) Section 68: Identity, genuineness, and creditworthiness

The Tribunal reaffirmed the orthodox section 68 framework: where a credit appears in the books, the assessee must provide a satisfactory explanation of its nature and source. In loan cases, courts consistently require demonstration of (i) identity of creditor, (ii) genuineness of transaction, and (iii) creditor's creditworthiness.

On facts, the Tribunal recorded that the assessee companies had furnished the standard documentary set: confirmations, bank statements of the lender, audited financials, and income-tax return acknowledgements. Importantly, the lender was an RBI-registered NBFC, and the transactions were through banking channels. The Tribunal emphasized that the AO's inference of non-creditworthiness could not override documentary evidence unless the AO brought cogent contrary material establishing that the funds were assessee's own money routed back, or that the lender lacked capacity despite apparent bank balances.

The Tribunal also noted an internal inconsistency: the AO accepted part of the funding chain as genuine (including certain funds traced to large, credible sources) but treated other portions as unexplained without demonstrating a transaction-specific defect. The Tribunal treated this "partial acceptance on identical facts" as weakening the AO's conclusion that the entire lender was merely an accommodation conduit.

2) Statements as sole basis: corroboration and "cherry-picking"

A major plank of the Revenue case was reliance on statements of persons alleged to be involved in accommodation entries, including older statements recorded in prior search actions. The Tribunal accepted the appellate finding that "standalone statements without corroborative evidence" cannot, by themselves, sustain section 68 additions when documentary loan evidence exists.

The Tribunal reproduced and approved the appellate reasoning that the AO selectively relied on statements supporting the Revenue narrative while ignoring other statements that were adverse to that narrative. It treated such selective reliance as a defect in appreciation of evidence, aligning with the principle that statements must be evaluated holistically and, where disputed, supported by independent material.

In this context, the Tribunal leaned on higher judicial authority for the proposition that additions made "solely based on statements" without deeper probing into documentary records are unsustainable. It expressly relied on the Supreme Court's approach in Principal Commissioner of Income-tax v. Dwarka Prasad Aggarwal [2024 (4) TMI 607 - SC ORDER] (cited in the order) to reject statement-only additions, as well as the broader rule that suspicion cannot substitute proof (Umacharan Shaw & Bros. [1959 (5) TMI 11 - SUPREME COURT]; Dhakeswari Cotton Mills [1954 (10) TMI 12 - SUPREME COURT (LB)]).

3) Incriminating material and search-era jurisprudence

Although the additions arose through reassessment proceedings, the factual background involved search actions and reliance on search statements. The Tribunal therefore invoked the jurisprudence that additions should not be made "dehors incriminating material" and that seized material must be assessment-year-specific and transaction-linked in search regimes.

The Tribunal cited CIT v. Singhad Education Society [2017 (8) TMI 1298 - SUPREME COURT] to emphasize the need for correlation of incriminating material with the relevant year, and PCIT v. Abhisar Buildwell (P.) Ltd. [2023 (4) TMI 1056 - SUPREME COURT] for the principle that additions cannot be made absent incriminating material. While strictly these rulings arise in the section 153A/153C context, the Tribunal used them to reinforce the evidentiary discipline required when the Revenue narrative is search-driven but the assessment record lacks seized, transaction-specific proof implicating the impugned loan.

4) "Source of source" for loans and the Finance Act, 2022 amendment

The AO's approach substantially examined the lender's upstream credits and treated the alleged weak credentials of entities upstream as destroying the lender's creditworthiness. The Tribunal accepted the appellate finding that many immediate credits in the lender's bank were repayments of earlier advances, not fresh loans. As a result, the AO's criticism of the upstream entities' creditworthiness was treated as misplaced: repayment of an advance is conceptually different from a fresh extension of credit to the lender that would require a separate capacity analysis for the relevant year.

On law, the Tribunal held that the specific "source of source" obligation for loan/borrowing credits (as introduced via Finance Act, 2022 by adding a proviso expanding explanation requirements) applies from assessment year 2023-24 onwards. For the years under consideration, the Tribunal treated insistence on proving upstream sources for non-share-capital loans as not mandated by statute, though it also noted that the assessees had, in fact, furnished a detailed explanation of credits in the lender's bank account.

The Tribunal referred to coordinate bench reasoning (including decisions cited in the order) that earlier section 68 amendments empowering deeper enquiries were historically focused on share capital/share premium contexts and not a general "source of source" rule for all loans for pre-amendment years.

5) Press release "shell company" allegation and independent verification

The Revenue argued that the lender was a "confirmed shell company" as per a Ministry of Finance press release and was categorized "high risk" by a financial intelligence authority for compliance failures. The appellate authority, exercising section 250(4), made an independent enquiry from the Serious Fraud Investigation Office (SFIO) and received a written confirmation that no investigation was initiated/pending/disposed against the lender. This was treated as undermining the AO's reliance on the press release as determinative evidence.

The Tribunal endorsed this approach. It treated the press release as, at best, an administrative flag, insufficient to displace documentary proof of real banking transactions and statutory compliance-particularly when the designated nodal authority did not confirm any proceedings.

6) Rule 46A versus section 250(4): appellate powers and opportunity to AO

Revenue also challenged the deletion on the ground that additional evidence was admitted in violation of Rule 46A. The Tribunal rejected this objection by affirming the distinction between:

  • Assessee-led additional evidence tendered u/r 46A; and

  • Evidence gathered by the appellate authority through independent enquiry u/s 250(4).

The Tribunal relied upon the principle (citing the Delhi High Court decision in CIT v. Manish Buildwell (P.) Ltd. [2011 (11) TMI 35 - DELHI HIGH COURT]) that where the appellate authority invokes section 250(4) suo motu, the strict Rule 46A conditions do not apply in the same manner. Crucially, the Tribunal noted repeated opportunities were provided to the AO (multiple reminders) to comment on enquiry results and materials, but the AO did not respond. This factual finding was decisive in negating procedural prejudice.

7) Repayment of loans and "double taxation" considerations

The appellate authority also relied on loan repayment in subsequent years and the contention that similar credits had already been subjected to tax in the lender's hands, making borrower-side additions duplicative. The Tribunal accepted repayment as a relevant corroborative factor supporting genuineness (especially where repayments are through banking channels and not questioned in later years). It also accepted the inequity of taxing the same stream multiple times, observing that once the underlying bank credits are already brought to tax in the lender's assessments, borrower-side taxation without fresh incriminating proof risks impermissible duplication.

While repayment alone is not a statutory exemption u/s 68, the Tribunal treated it as strengthening the inference that the transaction was not a sham entry-particularly when paired with confirmations, bank trail, and lack of cash-deposit evidence at the point of lending.

Key Holdings and Reasoning

Ratio (Operative principles)

  • Section 68 additions for bank-routed unsecured loans cannot be sustained where the assessee furnishes confirmations, bank statements, audited financials and tax particulars of the lender, and the AO relies primarily on uncorroborated statements/press releases without transaction-specific incriminating material.

  • For years prior to AY 2023-24, "source of source" for loan/borrowing credits is not a statutory requirement in the manner introduced by the Finance Act, 2022; in any event, where upstream credits are repayments of earlier advances, treating them as fresh borrowings is erroneous.

  • Material obtained by the appellate authority via section 250(4) enquiry is not to be equated with Rule 46A additional evidence, particularly when the AO is given opportunity to respond and fails to do so.

Obiter (Persuasive observations)

  • The Tribunal's broader reliance on "no addition dehors incriminating material" search jurisprudence, while persuasive in the search ecosystem, may be viewed as context-enhancing rather than strictly necessary in a reassessment setting; it serves to reinforce the evidentiary threshold when the Revenue case is search-statement driven.

  • Observations on "partial acceptance" of lender capacity by the AO suggest an expectation of consistent treatment of identical evidentiary patterns; while fact-sensitive, it signals a judicial intolerance for selective acceptance absent principled differentiation.

The Tribunal consequently dismissed all Revenue appeals, and-since the principal loans were held genuine-also upheld deletion of interest disallowances linked to those loans.

Conclusion

This decision consolidates a practical, evidence-centric approach to section 68 in loan cases: documentary proof and bank trail cannot be displaced by generalized allegations of "entry provider" behaviour unless the Revenue demonstrates a direct nexus between the impugned loan and an accommodation cash trail or other incriminating material. The ruling also clarifies procedural robustness of appellate fact-finding u/s 250(4), particularly when the AO is afforded opportunities but remains non-responsive.

For future disputes, the case underscores that administrative "shell entity" lists or press releases, without confirmation from competent investigative/regulatory outcomes and without transaction-specific evidence, are weak foundations for section 68 additions. It further anticipates a sharper litigation divide post-AY 2023-24, where the amended section 68 framework will likely expand legitimate "source of source" enquiries for loan credits; however, even under the amended regime, the Revenue's conclusions will still need to be evidence-led rather than inference-led.

A likely future development is the evolution of standards on when taxation in the lender's hands should restrain borrower-side additions to prevent duplicative taxation. Clear administrative guidance or statutory coordination mechanisms (especially where the Department simultaneously taxes bank credits in the lender and the corresponding receipts in borrowers) could reduce inconsistent outcomes and repetitive litigation.


Full Text:

2025 (12) TMI 780 - ITAT DELHI

Topics

Acts Income Tax