Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Consolidated Show Cause Notices under Sections 73 and 74 and Taxability of School Affiliation Servic...
    Fraudulent Input Tax Credit from Non-Existent Suppliers: Application of Sections 16, 74 and 155 of t...
    Case Laws Money Laundering
    Prolonged Pre-Trial Incarceration and Bail under Section 45 of the Prevention of Money-Laundering Ac...
    Case Laws Income Tax
    Prospective Operation of Section 56(2)(x)(b) in Stamp-Value Difference Cases Involving Immovable Pro...
    Seizure of Cash under Section 67 of the CGST Act and Interest on Illegal Retention
    Case Laws Income Tax
    Disallowance of Salary Expenditure for Allegedly Non-Genuine Services under Section 37
    Case Laws Income Tax
    Fair Market Value of Unquoted Equity Shares Under Section 56(2)(viib) and Rule 11UA
    Refund of Excess IGST Paid on Exports Following Clerical Error in FORM GSTR-3B
    Revocation of Cancellation of GST Registration for Non-Filing of Returns under Section 30 and Rule 2...
    Case Laws Income Tax
    TOLA, Section 149 and the Surviving-Time Test for Reassessment Proceedings
    Case Laws Customs
    Provisional Release of Unseized Imported Food Consignments under the Customs Act, 1962
    Case Laws Customs
    Recovery of Unpaid Anti-Dumping Duty After Self-Assessment Under Section 28 of the Customs Act, 1962
    Project-Wise Anti-Profiteering Methodology in Real Estate under Section 171 of the Central Goods and...
    Case Laws Income Tax
    Retirement Leave Encashment Exemption under Section 10(10AA)(ii) and Retrospective Application of No...
    Transit-State Jurisdiction under GST: Limits on Detention and Penalty in External Inter-State Suppli...
    Post-Facto Shareholder Ratification of Diversion of Preferential Issue Proceeds under the PFUTP Regu...
    Case Laws Income Tax
    Section 195 Withholding on Payments to Non-Residents: Royalty, Fees for Technical Services and Busin...
    Penalty: Scope of "Any Person" under Section 122(1A) of the Central Goods and Services Tax Act, 2017
    Recovery of Corporate Debtor Premises and Proof of Tenancy, Lease or Licence Rights under the Insolv...
    Service of GST Notices through the Common Portal: Statutory Validity and Practical Accessibility
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws GST
Show AI Summary
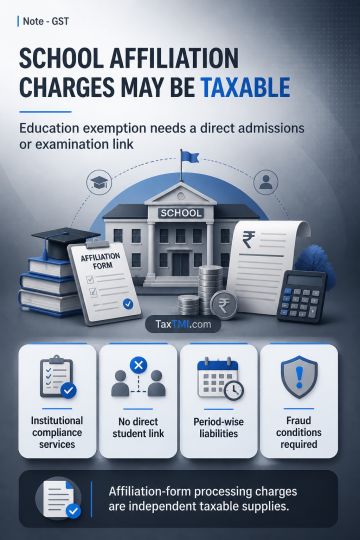
School affiliation services fall outside educational exemption without a direct nexus to admissions or examination conduct.
Consolidated show cause notices may combine financial years governed by Sections 73 and 74 where liabilities are segregated period-wise, each component independently meets limitation and notice requirements, the additional ingredients for fraud-based proceedings are satisfied, and no actual prejudice arises. School affiliation and affiliation-form processing charges are independent taxable supplies where they concern institutional eligibility and compliance, rather than directly and immediately relating to student admission or the conduct of examinations. A broad connection with education does not satisfy the educational-services exemption.
Case Laws GST
Show AI Summary
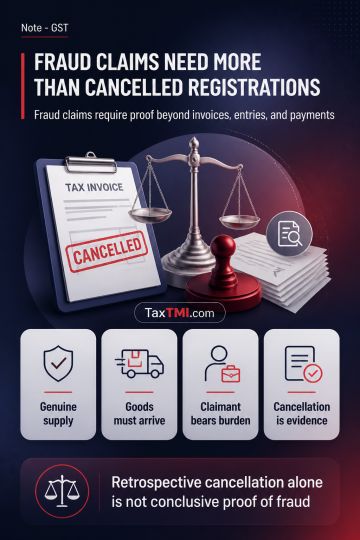
Fraudulent input tax credit requires proof of fictitious supplies, absent goods receipt, and fraud-linked self-assessment, not cancellation alone.
Input tax credit from allegedly non-existent suppliers depends on proof of genuine supply and actual receipt of goods or services, not merely invoices, accounting entries, or banking-channel payments. Section 155 places the burden of establishing ITC eligibility on the claimant. Section 74 requires more than ineligible credit: the wrongful availment must be linked to fraud, wilful misstatement, or suppression to evade tax. Retrospective supplier-registration cancellation is relevant evidence but is not conclusive. A fraud-based notice must disclose facts showing fictitious suppliers, absence of supply, and a basis for inferring the recipient's knowledge or participation.
Case Laws Money Laundering
Show AI Summary
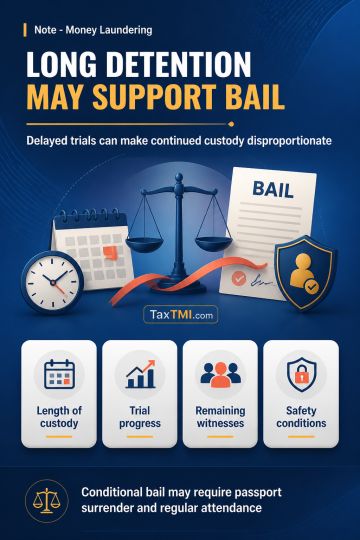
Prolonged pre-trial incarceration may justify conditional PMLA bail when delayed trials make continued detention constitutionally disproportionate.
Section 45 of the Prevention of Money-Laundering Act remains the stringent ordinary bail threshold, requiring prosecutorial opportunity and, on opposition, reasonable grounds to believe that the accused is not guilty and unlikely to offend while on bail. Article 21 nevertheless requires a separate, fact-sensitive inquiry where prolonged pre-trial detention and an unrealistic trial timetable make custody disproportionate. Relevant factors include custody length, trial progress, remaining witnesses, secured documentary evidence, source of delay, predicate-case status, and risks of absconding or witness interference. Conditions such as passport surrender, attendance, non-contact directions, and residence disclosure may safeguard the trial.
Case Laws Income Tax
Show AI Summary
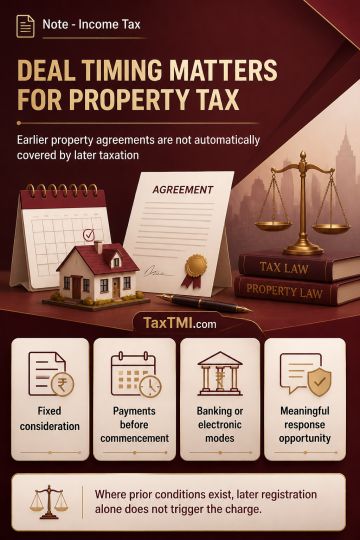
Prospective operation of stamp-value taxation prevents retrospective application where property agreements and substantial payments predate the charging provision.
Section 56(2)(x)(b) applies to immovable property received for inadequate consideration only where its temporal and valuation conditions are satisfied. A stamp-value difference alone does not establish taxability. Where consideration was fixed and substantial payments or contractual performance occurred before the charging provision commenced, later conveyance or registration does not by itself attract the later charge. Agreement-date valuation is available only for covered transactions where consideration was fixed and paid, wholly or partly, through prescribed banking or electronic modes on or before the agreement date. The tax authority must identify the correct statutory basis and provide a meaningful opportunity to respond.
Case Laws GST
Show AI Summary
GST cash seizure limits require statutory relevance and restitutionary interest for unlawfully retained currency following searches.
GST seizure powers cannot be used to take cash as a general investigative measure or security for a possible tax demand. Currency is excluded from goods, and "things" is confined contextually to articles useful or relevant as evidence in GST proceedings. Valid seizure and retention require recorded statutory reasons, procedural compliance and observance of return timelines. Unauthorised retention engages property protections; later return does not cure the deprivation, and accrued interest is restitutionary rather than delayed-refund interest.
Case Laws Income Tax
Show AI Summary
Salary expense genuineness requires proof of actual services, business purpose, and fair testing of adverse third-party statements.
Under Section 37(1), salary expenditure is deductible only where it is actually incurred wholly and exclusively for business purposes and is supported by proof of genuine employment, services rendered, business nexus, and payment. Bank transfers and accounting entries alone are not conclusive. Where a third-party statement is central to an allegation of non-genuine salary, the taxpayer should receive disclosure and a meaningful opportunity to rebut it, including cross-examination where appropriate. A retracted and uncorroborated statement is vulnerable as the sole basis for disallowance.
Case Laws Income Tax
Show AI Summary
Discounted cash flow valuation remains taxpayer-selected under prescribed rules, while tax scrutiny must identify specific valuation-date defects.
The taxpayer may elect a prescribed DCF valuation for unquoted equity shares, and scrutiny of that method does not permit substitution with Net Asset Value merely because it produces a lower fair market value. The Assessing Officer may examine projections, discount rates, terminal assumptions, computations and source data, but rejection requires demonstrably wrong facts, material errors, a wholly erroneous basis or objectively unsupported assumptions. Subsequent financial performance cannot alone invalidate a bona fide DCF valuation; the relevant inquiry remains the reasonableness of valuation-date information.
Case Laws GST
Show AI Summary
Excess IGST on exports remains refundable when later correction triggers automated refund and reconciliation proves duplicate payment.
Refund of excess IGST paid on zero-rated exports may arise where turnover and tax are mistakenly entered under non-zero-rated supplies in FORM GSTR-3B while export invoices and shipping bills are correctly reported in FORM GSTR-1. If the exporter then pays the same IGST in the correct zero-rated field and the automated refund is credited against that later payment, the earlier payment remains a separately identifiable potential excess; its claim is not a repeat request for the same export-tax refund.
Case Laws GST
Show AI Summary
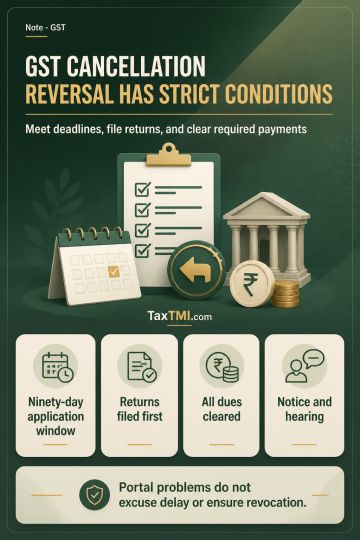
GST registration revocation requires timely application, return compliance, payment of dues, and a reasoned statutory decision.
GST registration revocation after cancellation for return default is a conditional, time-bound process. An application under Section 30 and Rule 23 must ordinarily be filed within ninety days, subject to prescribed extension, and cannot be made until pending returns are filed and tax, interest, penalty and late fee are paid. Portal non-acceptance may permit online or physical submission where technically unavailable, but does not condone delay or ensure revocation. The competent authority must assess statutory eligibility, sufficient grounds and compliance while following notice and hearing requirements before rejection.
Case Laws Income Tax
Show AI Summary
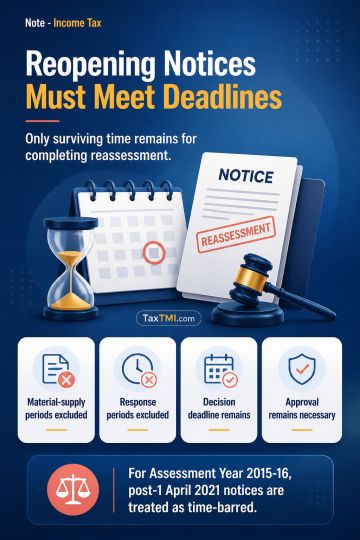
Reassessment limitation under TOLA requires final notices to issue within surviving time and satisfy statutory safeguards.
Reassessment limitation under TOLA is a jurisdictional restraint. Transitional notices issued between 1 April 2021 and 30 June 2021 are treated as Section 148A(b) show-cause notices, but only the surviving time remaining until 30 June 2021 is available for completing the reassessment process. Periods for supply of material and the assessee's response are excluded, but the Section 148A(d) decision, statutory approval and final Section 148 notice must issue within the remaining period. For Assessment Year 2015-16, post-1 April 2021 notices are treated as time-barred.
Case Laws Customs
Show AI Summary
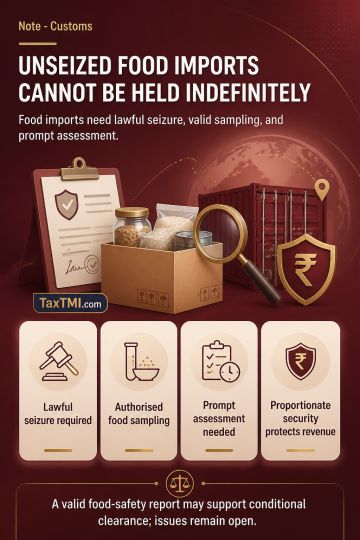
Unseized food consignments cannot face indefinite detention without lawful seizure, valid sampling, and prompt assessment.
Provisional release of an unseized imported food consignment is not mechanically governed by Section 110A, which applies to goods seized under Section 110. Customs may examine, test, verify and reassess imports, but indefinite retention without a seizure memorandum or disclosed reasons connecting the goods with confiscation is not justified. Food sampling should follow the specialised food-safety process through an authorised officer. A valid food-safety report may support conditional clearance, while classification, duty liability, confiscation and adjudication remain open. Revenue may be protected through proportionate security.
Case Laws Customs
Show AI Summary
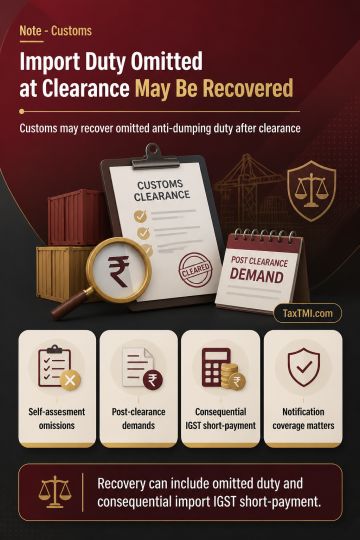
Anti-dumping duty recovery permits post-clearance demands and consequential import IGST where self-assessment omitted an applicable levy.
Unpaid anti-dumping duty omitted during self-assessment may be pursued through the customs recovery procedure without prior appellate modification of the self-assessment. The recovery framework applies to anti-dumping duty through statutory incorporation of provisions concerning assessment, non-levy, short-levy, interest and recovery. Where anti-dumping duty is chargeable, it forms part of the aggregate value used to compute IGST on imports, potentially creating a consequential IGST short-payment. Recovery requires accurate assessment of notification coverage, product, origin, rate, valuation, limitation and procedural safeguards.
Case Laws GST
Show AI Summary
Project-wise anti-profiteering requires actual input tax credit measurement and area-based allocation of benefits to real-estate purchasers.
Real-estate anti-profiteering under Section 171 requires project-level identification of additional input tax credit and allocation of the saving across total project area on a per-square-foot basis. Purchase value may quantify credit attributable to project expenditure, but turnover or collections cannot serve as the allocation basis. The comparison must use pre-GST credit actually availed rather than merely available credit. GST collected on consideration inflated by an undistributed benefit forms part of the amount not passed on and remains distinct from statutory interest.
Case Laws Income Tax
Show AI Summary
Retirement leave encashment exemption applies under the enhanced notified ceiling while preserving non-government employee classification and statutory conditions.
Section 10(10AA)(ii) governs retirement leave-encashment exemption for non-Government employees, subject to the ten-month earned-leave measure, average-salary computation, and the notified monetary ceiling. Notification No. 31/2023 specifies an enhanced ceiling of Rs. 25,00,000, is deemed effective from 1 April 2023, and certifies that retrospective effect causes no adverse effect. The enhanced ceiling is treated as a remedial rationalisation of an existing exemption and may govern pending earlier-period matters, while preserving the distinction between Government and non-Government employees.
Case Laws GST
Show AI Summary
Transit GST jurisdiction limits detention penalties for documented inter-State supplies lacking a local taxable nexus.
Transit-State jurisdiction under GST permits interception, document production, e-way bill verification and authorised physical inspection of goods moving through an intermediate State. It does not, in a pure transit movement, support detention-related penalty for an external inter-State supply where origin and destination lie outside the intercepting State, no tax is payable there, and there is no evidence of diversion, local supply, fictitious or mismatched documents, or mismatch of goods. Cross-empowerment is administrative and does not create an independent territorial taxable nexus.
Case Laws SEBI
Show AI Summary
Shareholder ratification cannot cure preferential-issue fund diversion when disclosed objectives are abandoned, triggering securities-market fraud and disclosure concerns.
Post-facto shareholder approval cannot retrospectively validate diversion of preferential-issue proceeds contrary to issue-specific objects disclosed to shareholders and the market. A special resolution authorises the issue but does not permit unrestricted use of proceeds. Periodic deviation reporting, audit-committee review and utilisation disclosures promote transparency; they do not enable diversion followed by later regularisation. Immediate diversion, inadequate commercial justification and missing documentation may indicate that disclosed objects were not genuinely intended to be performed. Later amendment of corporate objects or shareholder ratification cannot cure a completed securities-market disclosure breach.
Case Laws Income Tax
Show AI Summary
Cross-border software payments require copyright-right, technical-service, and permanent-establishment analysis before withholding obligations are determined under applicable treaties.
Section 195 requires withholding only from a remittance to a non-resident that includes income chargeable in India. For software, royalty depends on transfer of copyright rights, not merely the right to install, access, use, or distribute a copyrighted article under restrictive terms. Where a DTAA is more beneficial, its royalty and FTS definitions control; treaty FTS may require technology to be made available. Amounts that are neither royalty nor FTS require consideration as business profits, ordinarily taxable only where profits are attributable to a permanent establishment. Composite payments require component-wise allocation and analysis.
Case Laws GST
Show AI Summary
Personal GST penalty requires proof that the beneficiary retained benefit and directed a covered invoice or credit transaction.
Section 122(1A) may impose personal GST penalty on a registered or unregistered person only for a covered invoice or input tax credit transaction. Liability requires cumulative proof that the individual retained an identifiable personal benefit and that the transaction was conducted at that person's instance. Directorship, employment, registration, signature authority, or association with the taxable entity neither independently establishes nor excludes liability. Proceedings require transaction-specific and person-specific allegations and findings. The provision operates prospectively for underlying acts or transactions occurring on or after 01.01.2021.
Case Laws IBC
Show AI Summary
Proof of tenancy rights governs insolvency recovery of corporate-debtor premises from occupants lacking enforceable possessory interests.
Where premises form part of the corporate debtor's assets, Sections 18 and 25 of the Insolvency and Bankruptcy Code, 2016 require the resolution professional to take custody, control, preservation and protection measures. An occupant resisting recovery must prove a subsisting tenancy, leasehold interest or enforceable licence through reliable evidence of the parties' intended relationship and its essential terms. Permission to stock goods or conduct limited business activity, prolonged occupation, and business or utility records do not independently create rights in the premises. Section 60(5)(c) supports insolvency jurisdiction over asset-recovery measures connected with the insolvency estate.
Case Laws GST
Show AI Summary
GST portal service requires statutory validity and practical accessibility before ex parte adjudication can fairly proceed.
GST portal service is a statutory method under Section 169, but its use in an ex parte demand proceeding depends on effective accessibility and a meaningful opportunity to reply and be heard. Rule 142 requires electronic DRC-01 and DRC-07 summaries to operate alongside the underlying show-cause notice and reasoned order. Portal placement, complete communication, e-mail transmission, technical reliability and proof of actual access may determine whether service is effective, whether waiver applies, and whether appellate limitation begins.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

Evolution of Appellate Remedies in Indian Income Tax Law : Clause 356 of the Income Tax Bill, 2025 Vs. Section 246 of the Income-tax Act, 1961

4 July, 2025

Contents
Acts
Rules & Regulations
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Clause 356 Appealable orders before Joint Commissioner (Appeals).

Income Tax Bill, 2025

Introduction

The appellate framework within Indian income tax law has evolved to meet the demands of efficiency, transparency, and taxpayer rights. Clause 356 of the Income Tax Bill, 2025, represents a significant re-codification of the law relating to appeals before the Joint Commissioner (Appeals) (JCIT(A)), superseding and reimagining the regime previously governed by Section 246 of the Income-tax Act, 1961. This commentary provides a comprehensive analysis of Clause 356, exploring its scope, legislative intent, and practical implications, and undertakes a detailed comparative assessment with Section 246. The aim is to elucidate the continuities and departures in the legislative approach, highlight policy rationales, and anticipate the practical impact on taxpayers, revenue authorities, and the appellate system.

Objective and Purpose

The appellate structure under the Income Tax Act is designed to provide an effective and accessible remedy to taxpayers aggrieved by orders of the Assessing Officer (AO). The legislative intent behind Clause 356 is to streamline the process of appeals, clarify jurisdictional aspects, and enhance procedural efficiency-especially in light of technological advancements and the push for faceless proceedings. The provision seeks to balance the interests of taxpayers in securing expeditious justice with the administrative imperative of reducing litigation backlog and ensuring uniformity in appellate decisions.

Section 246, as it stood under the 1961 Act, was periodically amended to reflect changes in the tax administration, including the creation of new authorities and the expansion of appealable orders. Clause 356 represents the latest legislative effort to consolidate and modernize the appellate process, particularly in the context of the faceless and digital tax ecosystem envisaged by recent reforms.

Detailed Analysis of Clause 356 of the Income Tax Bill, 2025

1. Scope of Appealable Orders (Sub-section (1))

Clause 356(1) specifies the orders of an Assessing Officer (below the rank of Joint Commissioner) that are appealable before the JCIT(A). The clause is structured as an exhaustive list, with each item targeting a distinct category of order:

  • (a) Intimations u/s 270(1) or 399(1): This provision allows appeals against intimations involving adjustments, ensuring that taxpayers can challenge computational or procedural corrections made by the AO.
  • (b) Orders u/s 270(10) or 271: This covers substantive assessment orders, granting the right to appeal against the amount of income assessed, tax determined, loss computed, or the status of assessment. The inclusion of "status" is significant, as it affects the applicable tax rates and exemptions.
  • (c) Orders of assessment, reassessment, or recomputation u/s 279: This ensures that all forms of substantive tax computation-whether original, revised, or recomputed-are appealable, reflecting the principle of natural justice.
  • (d) Orders u/s 398: The specific reference to section 398 (the content of which is not detailed here) suggests inclusion of specialized orders, possibly relating to procedural or compliance aspects.
  • (e) Order imposing penalty under Chapter XXI: The right to appeal against penalties is a cornerstone of taxpayer protection, preventing arbitrary or excessive penal action.
  • (f) Orders u/s 287 or 288 amending any of the above orders: This ensures that amendments to the original orders, which may adversely affect the taxpayer, are also subject to appellate scrutiny.

The structure of Clause 356(1) reflects a deliberate effort to clarify and consolidate the categories of appealable orders, reducing ambiguity and ensuring that taxpayers have a clear understanding of their appellate rights.

2. Restrictions on Right to Appeal (Sub-section (2))

Clause 356(2) introduces a significant limitation: no appeal lies before the JCIT(A) if the impugned order is passed by, or with the prior approval of, an income-tax authority above the rank of Deputy Commissioner. This is a jurisdictional filter, designed to ensure that orders involving higher-level oversight are not subject to initial appellate review by the JCIT(A), but may instead be routed to the Commissioner (Appeals) or higher forums. This provision aims to maintain a hierarchical balance and prevent unnecessary duplication of appellate scrutiny.

3. Transfer of Appeals (Sub-section (3))

Clause 356(3) empowers the Board or an authorized income-tax authority to transfer appeals between the JCIT(A) and Commissioner (Appeals), regardless of the original jurisdiction. This flexibility is critical for efficient case management, workload balancing, and ensuring that appeals are adjudicated at the appropriate level. The provision recognizes the dynamic nature of tax litigation, where complexity, quantum, or policy considerations may warrant transfer of appellate jurisdiction.

  • (a) Appeals pending before the Commissioner (Appeals) can be transferred to the JCIT(A).
  • (b) Appeals pending before the JCIT(A) can be transferred to the Commissioner (Appeals).

This transfer mechanism is "notwithstanding" the earlier sub-sections, underlining its overriding effect and the legislative intent to prioritize administrative convenience and justice over rigid jurisdictional boundaries.

4. Opportunity of Rehearing (Sub-section (4))

To safeguard the principles of natural justice, Clause 356(4) mandates that where an appeal is transferred under sub-section (3), the appellant must be given an opportunity to be reheard. This is a critical procedural safeguard, ensuring that the transfer of jurisdiction does not prejudice the taxpayer's right to a fair hearing.

5. Faceless/Technological Scheme for Appeals (Sub-section (5))

A major innovation in Clause 356 is the explicit recognition of a government-notified scheme for the disposal of appeals. The provision allows for the disposal of appeals in an expedient, transparent, and accountable manner, with the elimination of physical interface between the JCIT(A) and the appellant to the extent technologically feasible. The Central Government is empowered to direct that the usual provisions relating to jurisdiction and procedure may not apply, or may apply with modifications, in the context of such a scheme.

This reflects the ongoing transition to a "faceless" or digital appellate system, aimed at reducing subjectivity, increasing efficiency, and minimizing opportunities for corruption or delay.

6. Exclusion of Certain Cases (Sub-section (6))

Clause 356(6) empowers the Board to specify, by notification, that the provisions of this section shall not apply to any case or class of cases. This carve-out allows the Board to exclude sensitive, complex, or high-stakes matters from the purview of the JCIT(A), thereby ensuring that only appropriate cases are handled at this level.

7. Definition of "Status" (Sub-section (7))

The term "status" is defined by reference to section 2(77), clarifying that it pertains to the category of person under which the assessee is assessed. The explicit definition eliminates interpretational disputes and aligns with the broader statutory lexicon.

Practical Implications

1. For Taxpayers

Clause 356 offers a structured and predictable appellate remedy for taxpayers aggrieved by specified orders. The inclusion of both substantive and procedural orders within its scope ensures comprehensive coverage. The provision for faceless appeals enhances taxpayer convenience and reduces the risk of arbitrary treatment. However, the restriction on appeals against orders passed with higher authority approval may limit remedies in certain high-stakes cases, necessitating recourse to higher appellate forums.

2. For Revenue Authorities

The transfer and exclusion provisions confer significant administrative flexibility, allowing the Board to allocate cases efficiently and focus resources on complex or high-value disputes. The faceless scheme aligns with the government's Digital India initiative and is likely to reduce litigation delays and administrative overhead.

3. For the Appellate System

By clarifying jurisdiction and streamlining procedures, Clause 356 is likely to enhance the overall efficiency of the appellate system. The opportunity for rehearing upon transfer ensures procedural fairness, while the exclusion power allows the Board to manage sensitive or precedent-setting cases appropriately.

Comparative Analysis with Section 246 of the Income-tax Act, 1961

1. Structure and Scope of Appealable Orders

Section 246 of the 1961 Act provided a detailed and somewhat expansive list of orders appealable to the JCIT(A), covering:

  • Intimations u/s 143(1) (adjustments)
  • Assessment orders u/s 143(3), 144, and 147
  • Various penalty orders (Chapter XXI)
  • Orders under TDS/TCS provisions (sections 200A, 201, 206CB, etc.)
  • Amendment orders u/ss 154 and 155

Clause 356, while similar in approach, reorganizes the categories and updates references to align with the proposed structure of the 2025 Bill. For instance, references to sections 270, 271, 279, 398, 287, and 288 in Clause 356 correspond to assessment, penalty, and amendment provisions in the new Bill. The consolidation of orders into broader categories, and the reliance on cross-references to other sections, streamlines the provision and reduces redundancy.

Notably, Clause 356 omits some specific TDS/TCS-related orders (such as those u/ss 200A, 201, 206CB, etc.) that were explicitly enumerated in Section 246. This may reflect a legislative intention to channel such disputes through alternative mechanisms or to the Commissioner (Appeals), or it may be an artifact of the restructured Bill where such matters are addressed elsewhere.

2. Jurisdictional Restrictions

Both provisions contain a similar restriction: no appeal to the JCIT(A) lies if the order is passed by, or with the prior approval of, an authority above the rank of Deputy Commissioner. This ensures that higher-level orders are subject to review at a more senior appellate forum, preserving administrative hierarchy.

3. Transfer of Appeals

Section 246 permitted the Board to transfer appeals between the Commissioner (Appeals) and JCIT(A), and vice versa, for reasons of administrative expediency. Clause 356 retains and clarifies this mechanism, allowing for transfer in both directions "notwithstanding" other provisions. The opportunity for rehearing is preserved in both statutes, reflecting a consistent commitment to procedural fairness.

4. Faceless/Technological Appeals

Section 246(5) authorized the Central Government to notify a scheme for faceless disposal of appeals, with the power to modify or exclude procedural provisions as necessary. Clause 356(5) builds on this framework, emphasizing transparency, accountability, and the elimination of physical interface. The language in Clause 356 is more forward-looking, explicitly referencing technological feasibility and the potential for broad procedural adaptation.

5. Exclusion of Cases

Section 246(6) and Clause 356(6) both empower the Board to exclude cases or classes of cases from the purview of the JCIT(A). This ensures that sensitive, complex, or high-stakes matters can be reserved for higher appellate forums, maintaining flexibility in the appellate process.

6. Definition of "Status"

Section 246 provided an explanation defining "status" as the category under which the assessee is assessed (individual, HUF, etc.). Clause 356 adopts a more precise approach, referencing section 2(77) of the new Bill, thereby integrating the definition into the broader statutory framework and reducing the risk of interpretational disputes.

7. Legislative Evolution and Policy Rationale

The changes from Section 246 to Clause 356 reflect a broader policy shift toward digitalization, administrative efficiency, and clarity in appellate rights. The move toward faceless appeals is a response to concerns over subjectivity, corruption, and delay. The consolidation and rationalization of appealable orders, as well as the enhanced transfer and exclusion powers, aim to optimize resource allocation and case management within the tax administration.

At the same time, the core principles of taxpayer protection-right to appeal, opportunity of hearing, and procedural fairness-are preserved and in some respects strengthened, particularly through explicit procedural safeguards.

Ambiguities and Potential Issues

  • Omission of Certain Orders: The apparent omission of some TDS/TCS-related orders in Clause 356 could create uncertainty regarding the appellate remedy for such disputes, unless addressed elsewhere in the Bill.
  • Scope of Exclusion Power: The broad exclusion power vested in the Board could, if exercised excessively, undermine the accessibility of the appellate remedy for certain classes of taxpayers.
  • Technological Challenges: The success of the faceless appellate scheme depends on robust digital infrastructure and user-friendly interfaces. Any deficiencies could impair access to justice, particularly for less tech-savvy taxpayers.
  • Procedural Adaptation: The power to modify or exclude procedural provisions in the context of the faceless scheme must be exercised judiciously to ensure that the core principles of natural justice are not compromised.

Comparative Features Table

Feature Section 246 of the Income-tax Act, 1961 Clause 356 of the Income Tax Bill, 2025
Appealable Orders Detailed, specific listing (including TDS/TCS, amendments, penalties) Consolidated, broader categories, updated cross-references
Jurisdictional Restriction No appeal if order by/higher authority approval Same restriction retained
Transfer of Appeals Permitted between JCIT(A) and Commissioner (Appeals) Permitted, with explicit "notwithstanding" clause
Rehearing on Transfer Opportunity to be reheard Opportunity to be reheard
Faceless/Technological Scheme Central Government may notify scheme Central Government may notify scheme; more emphasis on transparency, accountability, and technological feasibility
Exclusion of Cases Board may specify exclusions Board may specify exclusions
Definition of "Status" Explanation provided Reference to section 2(77)

Conclusion

Clause 356 of the Income Tax Bill, 2025, represents a thoughtful recalibration of the appellate framework for orders of the Assessing Officer. While preserving the essential safeguards and remedies embedded in Section 246 of the Income-tax Act, 1961, it introduces greater clarity, administrative flexibility, and technological innovation. The consolidation of appealable orders, the preservation of procedural fairness, and the embrace of faceless appeals are all positive developments.

Nonetheless, the practical success of the new regime will depend on the careful implementation of the faceless scheme, judicious exercise of exclusionary powers, and the provision of adequate guidance on the scope of appealable orders-especially where references to certain categories (such as TDS/TCS) are less explicit than in the past. The transition to the new regime will require sustained engagement between taxpayers, practitioners, and the tax administration to ensure that the appellate system remains accessible, efficient, and just.


Full Text:

Clause 356 Appealable orders before Joint Commissioner (Appeals).

Topics

Acts Income Tax