Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Law:
---- All Laws---- ❯
  • ---- All Laws----
  • Benami Property
  • Bill
  • Central Excise
  • Companies Law
  • Customs
  • DGFT
  • FEMA
  • GST
  • GST - States
  • IBC
  • Income Tax
  • Indian Laws
  • Money Laundering
  • SEBI
  • SEZ
  • Service Tax
  • VAT / Sales Tax
Types:
---- All Types ---- ❯
  • ---- All Types ----
  • Act Rules
  • Case Laws
  • Circulars
  • Manuals
  • News
  • Notifications
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    Case Laws Income Tax
    TNMM Comparability: Operating Items, Search Matrix and Functional Analysis under Rule 10B
    Case Laws Customs
    Validity of Gold Seizure under Section 110 and the Conditional Reverse Burden under Section 123 of t...
    Case Laws Income Tax
    Deduction under Section 80GGC: Genuineness of Political Contributions and Evidentiary Burden
    Post-Death Determination of GST Liability and Estate-Limited Recovery from Legal Heirs
    Non-Confirmation of Seizure under Section 37A of FEMA and the Requirement of Recorded Reasons to Bel...
    Case Laws Companies Law
    Oppression and Mismanagement Proceedings under Sections 241 and 242: Corporate Authority During Pend...
    Case Laws Benami Property
    Benami Claims in Self-Acquired Property: Rejection of Plaint and the Limits of the Fiduciary-Capacit...
    Case Laws Income Tax
    Reopening of Assessment under Sections 147 and 148: Reason to Believe, Tangible Material and Change ...
    Case Laws Income Tax
    Penalty under Section 270A on Disallowance of Political Donation Deduction under Section 80GGC
    Case Laws Income Tax
    Conditional Registration under Section 12AB and the Limits of Commissioner's Statutory Powers
    Case Laws Customs
    Transaction Value, Rule 12 and Enhancement Based on Consent Letters in Customs Valuation: Limits of ...
    GST on Assignment of Leasehold Rights: Distinguishing Transfer of Immovable Property from Supply of ...
    Case Laws Income Tax
    Leave Encashment Exemption for Non-Government Employees under Section 10(10AA)(ii) and the Enhanced ...
    Case Laws Income Tax
    Dependent Agent Permanent Establishment under Article 5(5) of the India-Switzerland DTAA: Authority,...
    Case Laws Customs
    Proper Officer Jurisdiction for Customs Show Cause Notices under Sections 2(34), 17, 28 and 124
    Case Laws Money Laundering
    Provisional Attachment of Pre-Offence Property as Proceeds of Crime or Equivalent Value under the PM...
    Disciplinary Suspension of Resolution Professionals Across Ongoing CIRPs: Proportionality, Hearing a...
    Electronic Authentication of GST Demand Proceedings: Rule 26(3), Sections 75, 160 and 169
    Large-Scale GST Evasion Prosecutions: Cognizable and Non-Bailable Classification under Section 132 a...
    Case Laws Customs
    Country of Origin Certificates and Preferential Customs Duty under Notification No. 46/2011-Customs ...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

Notes
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
Case Laws Income Tax
Show AI Summary
TNMM comparability requires consistent operating-cost treatment and FAR-based selection, while search matrices cannot replace evidence-led functional analysis.
TNMM requires consistent computation of operating profit and operating cost for the tested party and comparables. A provision for doubtful debts connected with sales and trade receivables may be an operating expense, as may routine business levies; income-tax on profits remains excluded. A search matrix is a disciplined evidentiary tool, not a statutory bar to an out-of-matrix comparable. Inclusion requires proof of functional fit, filter satisfaction and reasons for its absence, while rejection cannot rest solely on matrix absence. FAR analysis, segmental reliability and material scale differences govern comparability.
Case Laws Customs
Show AI Summary
Reasonable belief in gold seizure requires recorded objective grounds before the reverse burden for smuggling can arise.
Gold seizure under Section 110 requires the proper officer to hold, before seizure, objectively supportable reasons to believe that goods are liable to confiscation. For gold, Section 123 shifts the burden of disproving smuggling only after a lawful seizure made in reasonable belief that the gold is smuggled. A general panchnama recital, foreign markings, high purity, or an uncorroborated retracted statement cannot alone establish that foundation. Reasons must exist contemporaneously and cannot be supplied retrospectively through later investigation.
Case Laws Income Tax
Show AI Summary
Political contribution deductions require proof that payments are genuine, not merely bank transfers, receipts, and recipient registration.
Registration of the recipient political party, non-cash remittance, banking records and donation receipts are necessary evidentiary facts for a political-contribution deduction, but do not conclusively prove a genuine contribution. Where credible material indicates an accommodation-entry arrangement involving return of funds through intermediaries, the claimant must substantiate the transaction and address taxpayer-specific circumstances. General allegations about a recipient cannot alone displace a claim without a sufficient nexus to the taxpayer's own payment. Penalty initiation requires separate determination of under-reporting or misreporting and a reasonable opportunity of hearing.
Case Laws GST
Show AI Summary
Estate-limited GST recovery permits post-death assessment of legal representatives while protecting heirs' independent assets after business discontinuance.
Section 93 permits post-death GST determination against a legal representative where a liable person dies. If the business is discontinued, tax, interest and penalty may be recovered only from the deceased's inherited estate and only within its capacity; the heir's independent assets remain outside that limit. Proceedings may be initiated without a pre-death notice, but must be addressed to the legal representative in that capacity, follow the applicable adjudication process, and provide hearing and a reasoned order.
Case Laws FEMA
Show AI Summary
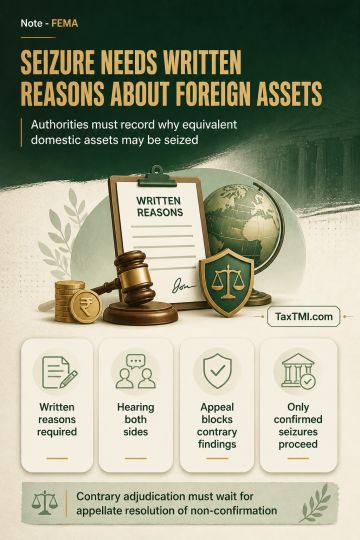
Recorded reasons to believe govern foreign-asset seizure; non-confirmation requires appellate resolution before contradictory adjudication proceeds.
Section 37A permits seizure of equivalent domestic assets only where the authorised officer records written reasons to believe that foreign assets are held in contravention of FEMA. The competent authority must examine the material after hearing both sides and either confirm or set aside seizure. A reasoned non-confirmation based on an absent statutory threshold is substantive on seizure, though it does not finally decide the underlying contravention. Pending appeal, the adjudicating authority cannot displace that finding or adopt a contrary premise; Section 37A(4) applies only to confirmed seizure.
Case Laws Companies Law
Show AI Summary
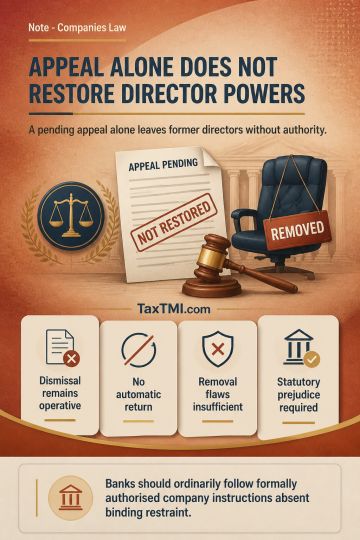
Unstayed tribunal dismissal leaves former directors without corporate authority while banks follow valid company instructions amid management disputes.
Where an oppression and mismanagement petition has been dismissed, a pending appeal without an appellate stay does not itself restore a former director's authority or suspend the dismissal's operative effect. Sections 241 and 242 require statutory prejudice and prescribed Tribunal findings; procedural irregularities in director removal may be relevant but do not alone establish oppression. Banks should ordinarily follow formally authorised company instructions rather than decide unresolved management disputes, unless a binding judicial or statutory restraint applies.
Case Laws Benami Property
Show AI Summary
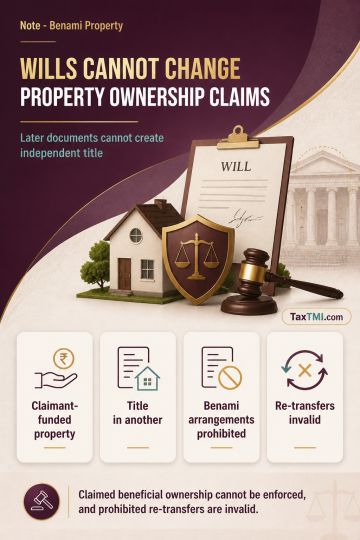
Benami property claims cannot be recast through wills or employment-based trust when pleadings assert beneficial ownership.
Benami-property claims based on a claimant's payment for property titled in another person's name may fall within the statutory definition when the property is alleged to be held for that claimant's benefit. A Will, succession claim, or other later instrument does not provide an independent basis of title where the pleaded foundation is restoration of beneficial ownership. The statutory scheme prohibits benami arrangements, bars enforcement of claimed beneficial ownership, and treats prohibited re-transfers as invalid; self-acquired title in the named holder's name does not displace the pleaded funding arrangement.
Case Laws Income Tax
Show AI Summary
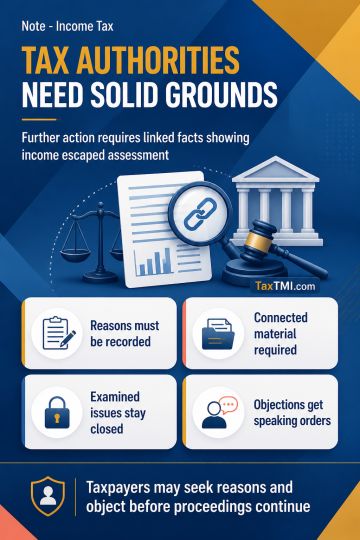
Reason to believe in reassessment requires tangible material, a live nexus, and recorded reasons; review of examined issues is barred.
Income-tax reassessment under Sections 147 and 148 is permissible only where recorded reasons, assessed at the time of notice, disclose a bona fide reason to believe that chargeable income escaped assessment. Final proof is unnecessary at that stage, but relevant tangible material must have a rational, live link to escapement. Reopening cannot be used to review an issue consciously examined and decided in the original scrutiny; nor can later or extraneous material supplement the recorded reasons. The taxpayer may seek the reasons, file focused objections, and receive a speaking order before reassessment continues.
Case Laws Income Tax
Show AI Summary
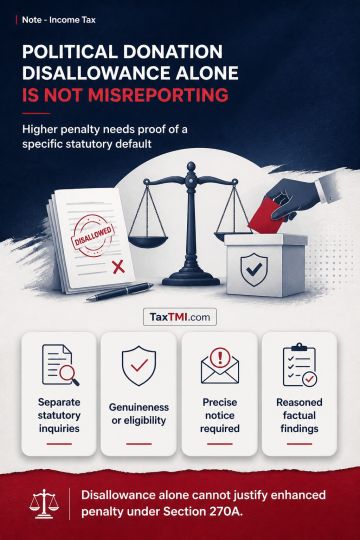
Political-donation deduction disallowance does not itself establish misreporting; enhanced penalty requires proof of a specific statutory default.
Disallowance of a political-contribution deduction under Section 80GGC and imposition of penalty under Section 270A are separate statutory inquiries. An adverse finding on genuineness or eligibility may raise assessed or reassessed income, but cannot alone establish misreporting. Enhanced penalty requires proof that the taxpayer's conduct falls within a specific Section 270A(9) category, supported by a precise notice and reasoned factual findings.
Case Laws Income Tax
Show AI Summary
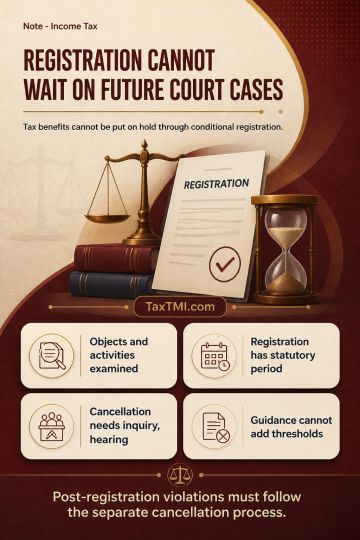
Conditional charitable registration cannot suspend tax benefits pending litigation outside the statutory grant and cancellation framework.
Section 12AB permits the authority, after inquiry into objects, genuine activities and material legal compliance, to grant registration for the statutory period or reject the application. It does not create a contingent form of registration whose tax consequences await future litigation. Post-registration violations must be addressed through the separate cancellation process, requiring inquiry and hearing. Conditions in prescribed forms or administrative guidance may operationalise statutory duties but cannot create extra-statutory eligibility thresholds, future-conduct obligations or anticipatory cancellation consequences. Binding jurisdictional rulings remain applicable unless stayed, modified or reversed.
Case Laws Customs
Show AI Summary
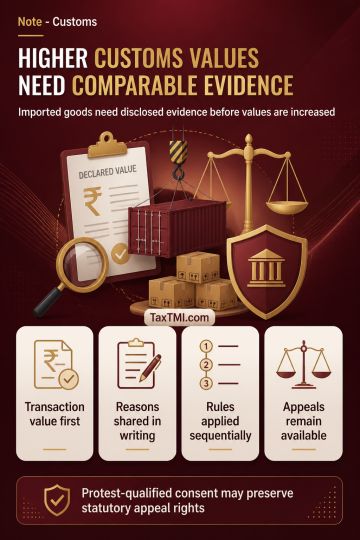
Transaction value reassessment requires disclosed comparable evidence, while protest-qualified consent preserves appellate rights against enhanced customs valuation.
Transaction value under Section 14 and Rule 3 is the primary basis for valuing imported goods. Rule 12 permits rejection only where an objectively sustainable reasonable doubt persists after considering further information; on request, the grounds must be disclosed in writing and a hearing afforded. Redetermination must follow Rules 4 to 9 sequentially and rely on demonstrably comparable import data. Written acceptance of reassessment may dispense with a speaking order under Section 17(5), but protest-qualified or provisional-clearance correspondence may preserve the statutory right to appeal.
Case Laws GST
Show AI Summary
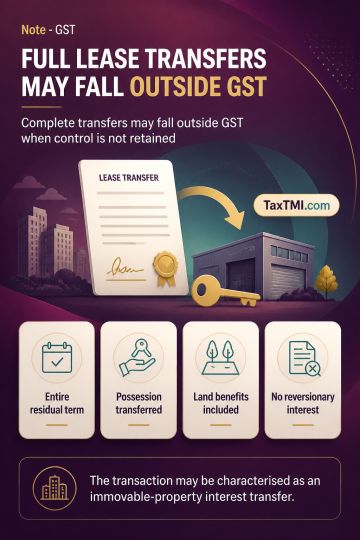
Leasehold rights assignment may fall outside GST when the lessee permanently transfers the entire proprietary estate.
GST treatment of assignment of leasehold rights turns on whether the lessee has made a complete transfer of its existing estate or continues to provide occupation or enjoyment. Where the assignor transfers the whole residual term, possession, building and associated rights, retains no reversionary or controlling interest, and the assignee succeeds directly to obligations towards the original lessor, the transaction may be characterised as transfer of benefits arising out of land rather than a supply of services. Labels such as premium, salami or transfer fee are not conclusive.
Case Laws Income Tax
Show AI Summary
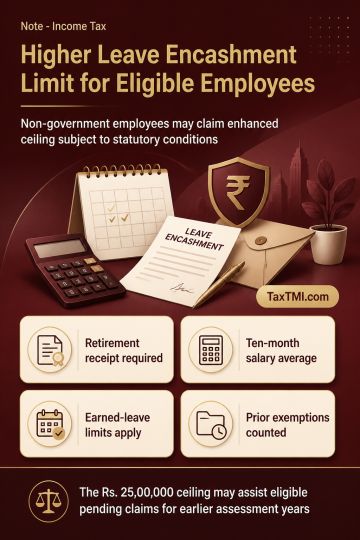
Leave encashment exemption: Non-government employees may claim the enhanced notified ceiling subject to statutory computation conditions.
Retirement leave encashment received by employees other than Central or State Government employees falls under Section 10(10AA)(ii). Exemption depends on retirement, the ten-month earned-leave limit, average salary for the preceding ten months, earned-leave entitlement restrictions, aggregate limits, and prior exempt receipts. The enhanced notified ceiling of Rs. 25,00,000, deemed to operate from 1 April 2023, is treated in the Tribunal approach discussed as a beneficial rationalisation available to eligible pending claims for earlier assessment years, without displacing the statutory computation conditions.
Case Laws Income Tax
Show AI Summary
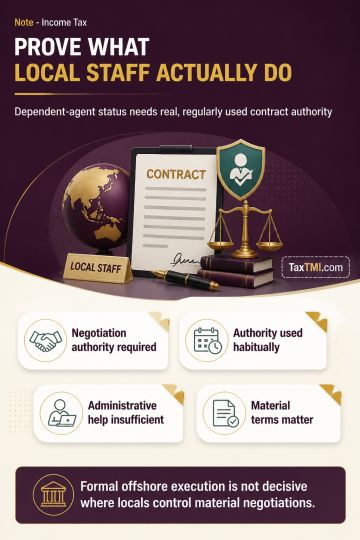
Dependent agent permanent establishment requires proven habitual contractual authority; liaison, administrative support, and customer contact alone remain insufficient.
Dependent agent permanent establishment under Article 5(5) requires proof that an Indian person has authority to negotiate and enter contracts for the foreign enterprise and habitually exercises that authority. Customer liaison, account management, administrative support, communication of pre-approved terms, document routing, and assistance with online standard-form contracting fall short unless Indian personnel substantively determine essential terms or routinely bring negotiations to a binding commercial conclusion. Formal offshore execution is not decisive where local personnel effectively control material negotiations. Corporate association, economic dependence, and independent-agent considerations cannot replace proof of the positive authority and habitual-exercise requirements.
Case Laws Customs
Show AI Summary
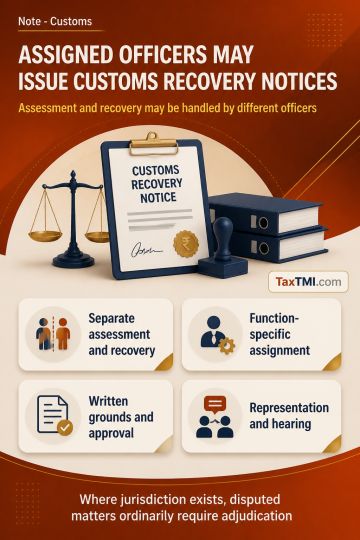
Proper-officer jurisdiction permits assigned customs officers to issue recovery notices without having performed the original assessment.
Customs show-cause jurisdiction requires both appointment as an officer of customs and function-specific assignment as the proper officer. Assessment under Section 17 and recovery under Section 28 are distinct functions; the original assessing officer need not alone issue a recovery notice. Retrospective validation of qualifying officers' proper-officer status applies independently of the preserved historical recovery regime. Confiscation and penalty proceedings require written grounds, prescribed prior approval, representation, and hearing. Where jurisdiction exists, disputed facts, evidence, limitation, and procedural compliance ordinarily require determination through adjudication.
Case Laws Money Laundering
Show AI Summary
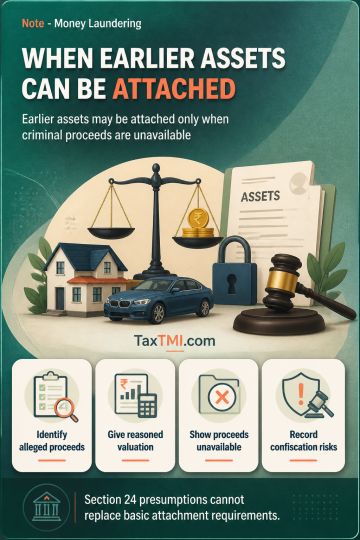
Equivalent-value attachment permits securing untainted pre-offence assets only when unavailable criminal proceeds, valuation, and statutory risk are established.
Pre-offence property is ordinarily not directly derived from later scheduled-offence activity, but may be provisionally attached as equivalent value where actual proceeds are unavailable. Such attachment requires identification and reasoned valuation of the alleged proceeds, material showing their unavailability, and recorded reasons to believe that non-attachment risks concealment, transfer, or other frustration of confiscation. A later use of illicit funds to repay loans, construction borrowing, or secured obligations may separately establish a direct or indirect nexus. Section 24 presumptions do not replace the foundational requirements for attachment.
Case Laws IBC
Show AI Summary
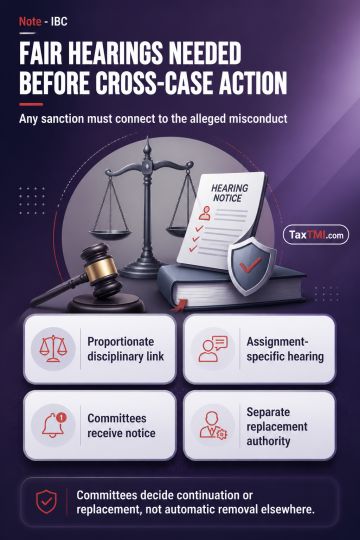
Cross-assignment disciplinary suspension requires proportionate, assignment-specific hearing while creditor committees retain statutory control over replacement decisions.
Where disciplinary misconduct concerns one CIRP, cross-assignment suspension requires a proportionate link to the pleaded charge, supporting material and hearing afforded. Section 220(2) permits disciplinary sanctions after hearing, while Regulation 13(7) requires intimation to Committees of Creditors and the Adjudicating Authority. On the prima facie construction applied, intimation informs each Committee's decision on continuation or replacement rather than automatically removing the professional from unrelated ongoing assignments. The Board's regulatory role and the Committee's replacement power remain distinct but connected.
Case Laws GST
Show AI Summary
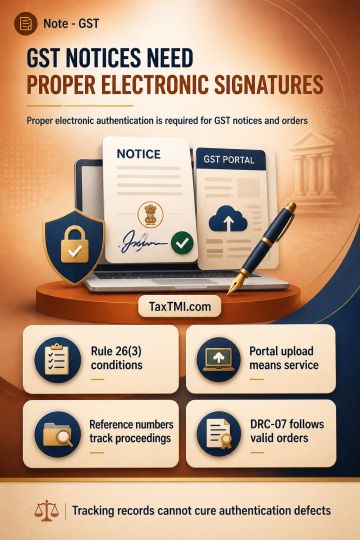
Electronic authentication of GST notices requires prescribed signatures; portal uploads, reference numbers, and DRC summaries cannot independently validate proceedings.
Rule 26(3) makes electronic issuance and authentication by digital signature, e-signature, or a notified verification mode cumulative conditions for GST notices and orders. A portal upload concerns service, while a system-generated reference number, DRC summary, or DIN performs tracking or procedural functions; none independently establishes the authorised officer's authentication. Section 169 governs service rather than validity, and Section 160 does not ordinarily cure a defect preventing attribution of the instrument to the competent officer. DRC-01 cannot replace the statutory notice, and DRC-07 supports recovery only upon a valid order.
Case Laws GST
Show AI Summary
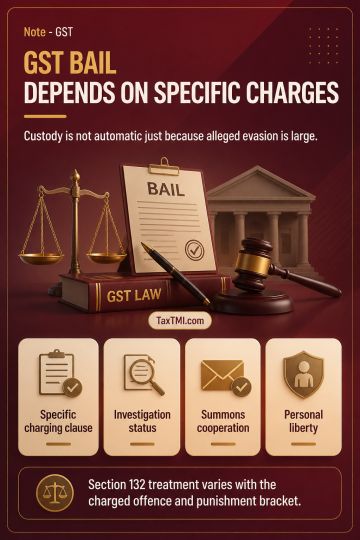
GST bail classification requires precise Section 132 charging clauses, with investigation status, cooperation and proportionality governing custodial necessity.
GST-evasion bail adjudication requires a case-specific assessment of custodial necessity rather than an automatic consequence of the alleged tax magnitude, Magistrate-triability, or a maximum five-year sentence. Section 132 classification depends on the precise offence clause and punishment bracket, not merely on the alleged quantum of evasion. Relevant considerations include the stage of investigation, cooperation with summons, security of evidence, individual role, risks of absconding or interference, proportionality, and personal liberty under Article 21.
Case Laws Customs
Show AI Summary
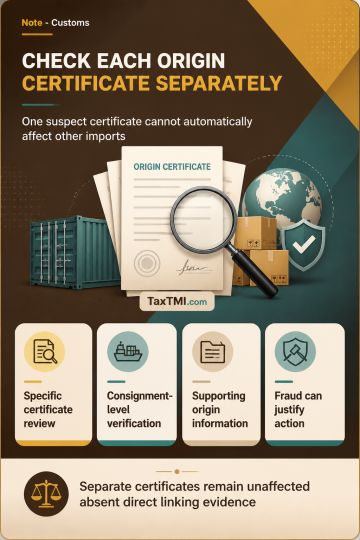
Certificate-specific origin verification prevents preferential-duty denial based solely on unrelated suspect certificates or supplier doubts.
Preferential customs-duty treatment requires compliance with applicable rules of origin and reliable proof that imported goods qualify as originating. A country-of-origin certificate is important evidence but does not remove the importer's duty to possess supporting origin information and exercise reasonable care. Challenges to preferential treatment must be certificate-specific and consignment-specific: an adverse finding concerning identified certificates cannot, without direct evidence, invalidate separate certificates. Customs verification should identify the particular proof of origin, alleged defect and material linking it to the import, while fraud, suppression or misrepresentation independently established may support substantive action.

TMI Notes

Back

All TMI Notes

Showing Results for :
Reset Filters
No Records Found

TMI Notes

The Arrest Protocol Under PMLA: Compliance with Constitutional Mandates

23 January, 2024

Contents
Acts
Plus +
Summary
Note

Note

-

Bookmark

(New) -

Download

Print

Print

Deciphering Legal Judgments: A Comprehensive Analysis of Case Law

Reported as:

2023 (12) TMI 785 - Supreme Court

I. Introduction

The appeal at hand challenges a High Court decision regarding the legality of an arrest made under the Prevention of Money Laundering Act, 2002 (PMLA). This case delves into the interpretation of Section 19 of PMLA and its compliance with the constitutional rights enshrined in Articles 14, 20, and 21 of the Indian Constitution.

II. Factual Background

The appellant, founder of M/s Supertech Limited, faced numerous FIRs leading to an investigation by the Enforcement Directorate (ED) under the PMLA. The contention revolves around the procedural aspects of his arrest, specifically whether the ED's practice of not providing a written copy of arrest grounds at the time of arrest conforms to the legal standards set by Section 19 of the PMLA.

III. Legal Issue

The central legal question is whether the ED's action in handing over the document containing the grounds of arrest to the appellant, obtaining his endorsement and signature, but not furnishing a physical copy at the time of arrest renders the arrest illegal under PMLA.

IV. Statutory and Judicial Framework

  • Section 19 of PMLA: This section empowers certain officers to arrest individuals believed to be involved in money laundering, with the requirement to inform them of the grounds for such arrest.
  • Article 22(1) of the Constitution: It mandates that an arrested individual must be informed of the grounds of arrest.

V. Analysis of Submissions and Legal Interpretations

  • Reliance on Precedents: The appellant's counsel, referencing decisions like Pankaj Bansal v. Union of India, argued for the necessity of a written copy of arrest grounds. The respondent countered, highlighting the precedent set in Vijay Madanlal Choudhary v. Union of India, asserting the sufficiency of oral communication of arrest grounds.
  • Interpretation of "as soon as may be": This phrase, critical in Section 19 of PMLA, was analyzed with reference to various judicial interpretations, emphasizing its meaning as "within a reasonably convenient or requisite time".

VI. The Court's Reasoning and Conclusion

  • The court found that the ED's practice of orally informing the arrestee of the grounds, followed by a later written communication, aligns with the requirements of Section 19 of PMLA and Article 22(1) of the Constitution.
  • The court also noted the inconsistency in the ED's practice but deemed it compliant with legal standards, particularly before the judicial clarification provided in the Pankaj Bansal case.
  • The court underscored the principle of judicial precedent, emphasizing that a two-judge bench cannot overlook the decisions of a larger bench, thus aligning its interpretation with the Vijay Madanlal Choudhary precedent.
  • Ultimately, the appeal was dismissed on the grounds that the arrest procedure adhered to the legal framework of PMLA and constitutional mandates.

VII. Implications and Significance

This judgment is significant for several reasons:

  • It clarifies the procedural requirements under PMLA concerning arrest procedures.
  • It upholds the principle of judicial precedent, ensuring consistency in legal interpretations.
  • The judgment balances the enforcement needs under PMLA against the constitutional rights of individuals.
  • It sets a precedent for future cases involving the interpretation of arrest procedures under special laws like PMLA.

VIII. Conclusion

The judgment meticulously interprets the legal provisions of PMLA in the context of constitutional mandates, offering clarity on the procedural aspects of arrests under this special legislation. It reinforces the principles of judicial precedent and legal consistency, ensuring that the rights of individuals are not overlooked in the enforcement of laws aimed at curbing money laundering.


Full Text:

2023 (12) TMI 785 - Supreme Court

Topics

Acts Income Tax