

Loading...

✕
Top
Help
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

E-mail: [email protected]

Call / WhatsApp at: +91 99117 96707

For more information, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
Default View
Expand ❯❯
Close ✕
🔎 News - Adv. Search
TEXT SEARCH:

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In:
Main Text + AI Text
  • Main Text
  • Main Text + AI Text
  • AI Text
Category: ?
Categorized by AI
---- All Categories ----
  • ---- All Categories ----
  • Income Tax
  • GST
  • Customs, DGFT & SEZ
  • FEMA & RBI
  • Corp. Laws, SEBI & IBC
  • PMLA, Black Money & ED
  • Budget
  • News and Press Release
  • PTI News
Month:
---- All Months ----
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ----
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
    FORM 9 - Frequently Asked Questions (FAQs)
    Guidance Note - Form 8
    How Energy Star Ratings Affect the Price of Window Air Conditioners
    FORM 8 - Frequently Asked Questions (FAQs)
    Guidance Note - Form 7
    FORM 7 - Frequently Asked Questions (FAQs)
    Rupee falls 18 paise to 93.94 against US dollar in early trade
    Guidance Note - Form 6
    Form 6 - Frequently Asked Questions (FAQs)
    Rs 117cr laundering: Court denies bail to Pune businessman, says economic crimes a 'serious threat'
    No bail to Pune businessman in Rs 117cr laundering case; court cites gravity of economic crimes
    Person loses Scheduled Caste status on converting from Hinduism, Sikhism, Buddhism: SC
    Delhi CM Rekha Gupta presents Rs 1.037 lakh cr budget; Rs 22,236 crore for 'green initiatives'
    Guidance Note - Form 5
    FAQ — FORM 5
    All India Workshop of Trainers for Rapid Survey of Functional Cooperatives (RSFC) on 25th March, 2026 at New Delhi
    Annual Survey of Unincorporated Sector Enterprises (ASUSE) Results for 2025 (Survey period: January 2025 to December 2025)
    Government Expands DEH Initiative to Boost District-Level Export Competitiveness
    India’s Total Exports Rise to USD 714.73 Billion in FY 2025–26 (Apr–Jan)
    DPIIT signs MoU with leading air conditioning company to strengthen manufacturing and startup ecosystem
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

News
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
March 25, 2026
Show AI Summary
Form 9 receipt for approved scientific research payments supports deduction claims and compliance tracking.
Form 9 is the prescribed receipt for payments received towards an approved scientific research programme under section 45(3)(c) read with Rule 30. It is issued to the sponsor by the executing institution, records the payment against the approved programme in FORM 8, and supports the sponsor's deduction claim subject to compliance with the Act and Rules. The form is programme-specific, may be issued for each payment or tranche including advance payments, and captures the sponsor details, payment particulars, approved cost, approved tax years, and cumulative receipts. It is not filed with the tax department but retained as supporting evidence.
March 25, 2026
Show AI Summary
Scientific research programme approval under tax law requires Form 8, with defined scope, cost, compliance and monitoring conditions.
Form 8 is the statutory approval order for a scientific research programme under section 45(3)(c) of the Income-tax Act, 2025 and Rule 30. It is issued after examination of a sponsor's Form 7 application, records the approved scope, duration, cost, tax years and conditions of the programme, and is signed by the designated authority. The approval is programme-specific, cost-specific and time-bound, while post-approval compliance includes separate books, audit, reporting, asset restrictions and final completion reporting.
March 25, 2026
Show AI Summary
Energy Star ratings shape window air conditioner pricing by raising upfront cost while lowering electricity bills and maintenance.
Energy Star ratings for window air conditioners reflect Bureau of Energy Efficiency standards and indicate how much cooling an AC delivers per unit of electricity consumed. Higher-rated units generally cost more upfront because they use advanced components, smarter controls, and more efficient motors and compressors, but they can lower electricity bills, reduce maintenance, and extend service life. Choosing the right star rating depends on usage patterns, room size, budget, and local electricity tariffs, with energy efficiency affecting both purchase price and long-term ownership cost.
March 25, 2026
Show AI Summary
Scientific research programme approval in FORM 8 governs tax deduction eligibility, compliance conditions, and programme-specific approval limits.
Approval in FORM 8 records the prescribed authority's sanction of a scientific research programme under section 45(3)(c) read with Rule 30, following an application in FORM 7. It is a statutory approval order, not a filing by the sponsor, and identifies the programme, approved tax years, approved total cost, and any attached conditions. FORM 8 is programme-specific and cost-specific, and deduction depends on compliance with the Act, the Rules, and post-approval obligations.
March 25, 2026
Show AI Summary
Scientific research approval through Form 7 creates a programme-specific gateway for deduction eligibility and post-approval compliance.
Prior approval for a sponsored scientific research programme is obtained through Form 7, which is the programme-specific application for approval of expenditure on scientific research carried out through a National Laboratory, University, Indian Institute of Technology or specified person. The prescribed authority examines the programme's feasibility and scientific merit, communicates approval or rejection in Form 8, and the approval is cost-specific and only a pre-condition for deduction. Post-approval compliance requires separate accounts, periodic reporting, restricted use of funds and completion reports.
March 25, 2026
Show AI Summary
Prior approval for scientific research deduction requires FORM 7 before commencement, with strict programme-specific compliance conditions.
A sponsor seeking deduction for expenditure on a scientific research programme must furnish FORM 7 as the prescribed application for prior approval before commencement. Separate applications are required for each programme, and the form calls for details of the sponsor, the proposed research programme, its duration and estimated cost, and the executing institution. Approval may be granted only for eligible programmes carried out through specified institutions, while market research, sales promotion, routine quality control, commercial production, and routine data collection are excluded.
March 25, 2026
Show AI Summary
Rupee weakness amid foreign fund outflows, lower crude prices and expectations of RBI dollar support.
The rupee weakened in early trade against the US dollar amid sustained foreign fund outflows and market uncertainty linked to the West Asia crisis. The decline was partly cushioned by lower global crude oil prices, a weaker dollar and a firm opening in domestic equity markets. Market participants also expected RBI intervention through dollar sales, while exporters were hedging and importers buying on dips.
March 25, 2026
Show AI Summary
Audit report compliance for deduction claims under income-tax law requires Form 6, UDIN, and electronic verification.
Form 6 is the prescribed income-tax audit report for an assessee claiming deduction under Section 44 or Section 51 of the Income-tax Act, 2025, and must be certified by an accountant. It is to be filed electronically through the Income-tax e-Filing Portal, verified by Digital Signature Certificate, and furnished one month before the due date for the return of income for the relevant Tax Year. The form requires audit confirmation, supporting records, UDIN generation, and assessee verification for claims under both deduction provisions.
March 25, 2026
Show AI Summary
Audit-certified deduction reporting requires electronic Form 6 filing, accountant certification, UDIN, and digital verification for qualifying expenditure claims.
Form 6 is the prescribed audit report for an eligible assessee claiming deductions under section 44 for preliminary or project-related expenditure or under section 51 for mineral prospecting and development expenditure. It must be certified by an accountant and furnished electronically through the Income-tax e-Filing Portal. The form is filed once in the first tax year in which the deduction is claimed, at least one month before the due date for furnishing the return of income, with UDIN generation and digital verification required.
March 25, 2026
Show AI Summary
Money laundering bail refusal highlights serious economic offences, sufficient PMLA material, and unresolved double mortgage allegations.
Bail was refused in a money laundering prosecution under the Prevention of Money Laundering Act where the court found sufficient material linking the accused to the offence and treated the recorded PMLA statements as forming a formidable case. The court observed that economic offences pose a serious threat to the financial health of the country and that the gravity, seriousness and magnitude of the alleged conduct, along with the accused's major role, weighed against release on bail. Partial repayment did not discharge criminal liability, and the absence of an explanation for the alleged double mortgage remained relevant at the bail stage.
March 24, 2026
Show AI Summary
Money laundering bail disputes hinge on fraudulent credit facilities, double mortgaging, and the gravity of economic offences.
Bail in a money laundering prosecution was opposed on the basis that the accused was linked to allegedly fraudulent borrowing and diversion of bank credit facilities, including mortgage and alleged double sale of secured properties. The prosecution relied on statements under the Prevention of Money Laundering Act and other material to contend that sufficient evidence connected the accused to the offence and that the matter involved a serious economic offence affecting the financial system.
March 24, 2026
Show AI Summary
Scheduled Caste status and religious conversion: membership ends immediately on conversion to a non-specified faith.
A person belonging to a Scheduled Caste loses that status on conversion to a religion other than Hinduism, Sikhism or Buddhism, and the loss is immediate and complete from the moment of conversion. The bar in the Scheduled Castes Order, 1950 is categorical, so a person who professes and practices a non-specified religion cannot claim Scheduled Caste membership for statutory benefits, protections, reservations or other entitlements flowing from that status.
March 24, 2026
Show AI Summary
Green budget drives welfare schemes, electric mobility, disaster readiness and sectoral infrastructure spending across Delhi.
Delhi's FY27 budget sets out a broad fiscal and welfare programme with major allocations for environmental protection, education, health, transport, urban development, social welfare and water supply. It introduces measures such as free diagnostic tests for newborn babies, bicycles for girl students, free LPG cylinders for ration card-holding families on Holi and Diwali, the Mahila Samriddhi Yojna, electric auto-rickshaw permits for women and transgender persons, and expanded Ayushman Bharat Health coverage. It also provides for electric buses, a semiconductor policy, disaster management infrastructure, firefighting upgrades and water and sewage projects.
March 24, 2026
Show AI Summary
Preliminary expense disclosure in Form 5 requires electronic filing, detailed reporting, and strict compliance for income-tax deduction claims.
Form 5 is a mandatory electronic statement for an assessee claiming deduction for preliminary expenses under the Income-tax Act, 2025, to be furnished in accordance with Rule 27 and one month prior to the due date for filing the return of income. It requires disclosure of assessee particulars and transaction-level details of qualifying preliminary expenses, including feasibility reports, project reports, market or business surveys, and engineering services, with related PAN, TDS, and payment particulars.
March 24, 2026
Show AI Summary
Preliminary expenses deduction reporting requires electronic Form 5, with item-wise disclosure, verification, and timely portal filing.
Electronic Form 5 is the prescribed statement for reporting preliminary expenses claimed as a deduction under Section 44 of the Income-tax Act, 2025. It applies to eligible expenditure connected with setting up or extension of a business, including feasibility reports, project reports, market or business surveys, and engineering services related to business, and must be filed for each tax year through the income-tax portal using digital signature or electronic verification. The form requires disclosure of assessee particulars, item-wise expense details, service-provider information, payment particulars, and TDS data where applicable.
March 24, 2026
Show AI Summary
Functional cooperatives survey training set to standardise nationwide data collection and measure economic contribution.
Preparatory training was organised for the Rapid Survey of Functional Cooperatives before six months of field work beginning in April 2026. The workshop brought together senior officers and field functionaries who will serve as Master Trainers for subsequent regional training, with the aim of standardising nationwide survey operations. The survey will assess the contribution of functional cooperatives to employment generation and economic activity across rural and urban areas, and will estimate indicators such as Gross Value Added, Gross Value of Output and employment generated by cooperatives.
March 24, 2026
Show AI Summary
Unincorporated sector survey shows stronger employment, higher value added, rising wages and wider internet adoption across establishments.
Annual Survey of Unincorporated Sector Enterprises (ASUSE) 2025 covers unincorporated non-agricultural establishments in manufacturing, trade and other services, and collects data on workers, Gross Value Added, emoluments, fixed assets, loans, ownership, registration status and use of information and communication technology for policymaking and national accounts. The survey reports growth in establishments, employment, Gross Value Added, labour productivity, female-owned proprietary establishments, emolument per hired worker and internet use, and notes a revised sampling design enabling quarterly selection and district-level annual estimates.
March 24, 2026
Show AI Summary
District-led export promotion expands through local committees, action plans, and market access support for MSMEs and farmers.
District-led export promotion under the Districts as Export Hubs initiative is implemented through State Export Promotion Committees and District Export Promotion Committees across all States and Union Territories. District Export Action Plans identify export potential in local products and sectors, while outreach events, public data portals, and district-level committees are used to build awareness, address bottlenecks, and support exporters, manufacturers, MSMEs, farmers, and small-scale industries.
March 24, 2026
Show AI Summary
Export policy and trade facilitation framework strengthens competitiveness, digital governance, and market access across India's export ecosystem.
India's export framework is being strengthened through policy support, financial incentives, digital trade facilitation, infrastructure development, and trade agreements to expand competitiveness and global market access. The Foreign Trade Policy 2023, RoDTEP, the Export Promotion Mission, export credit support, and export-linked infrastructure are described as core instruments for improving trade finance, logistics, market readiness, and MSME competitiveness. Digital governance tools and trade agreements are said to support faster compliance, transparency, market access, and investment flows.
March 24, 2026
Show AI Summary
Startup ecosystem collaboration advances industry-linked innovation support for HVAC, manufacturing, testing, and pilot deployment opportunities.
Industry-linked innovation support is being advanced through a Memorandum of Understanding to strengthen the manufacturing and startup ecosystem. The collaboration is directed at product startups working in HVAC technologies, digital solutions, advanced manufacturing processes, and supply chain innovation, with the aim of enabling scalable, industry-relevant solutions through structured engagement. Startups will receive mentorship, testing facilities, R&D infrastructure, pilot opportunities, market linkages, and structured Proof-of-Concept programmes.

News

Back

All News

Showing Results for :
Reset Filters
No Records Found

News

Back

All News

Showing Results for : Reset Filters
Customs, DGFT & SEZ

Directorate General of Commercial Intelligence and Statistics Revises Base Year of Merchandise Trade Indices to FY 2022–23 to Reflect Current Trade Structure and Global Patterns

February 21, 2026

Contents
Summary
Note

Note

-

Bookmark

Print

Print

Merchandise Trade Indices are compiled and published by the Directorate General of Commercial Intelligence and Statistics (DGCI&S), Ministry of Commerce & Industry, to measure changes in the unit values (prices) of India’s exports and imports over time. These indices serve as important indicators of external sector price movements and are widely used for economic analysis, including national accounts compilation and assessment of terms of trade. Over the years, the base year of the indices has been periodically revised to reflect structural changes in India’s trade composition and evolving global trade patterns. The most recent revision updates the base year to FY 2022–23 (2022–23 = 100), replacing the earlier base of FY 2012–13, thereby ensuring that the indices accurately represent the current structure of India’s merchandise trade.

Revision of Base Year of India’s Merchandise Trade Indices to FY 2022–23

The Directorate General of Commercial Intelligence and Statistics (DGCI&S), Ministry of Commerce & Industry, has revised the base year of India’s Merchandise Trade Indices from FY 2012–13 to FY 2022–23 (2022–23 = 100), in view of the structural changes in the economy, shifts in commodity composition, evolving trade patterns, and the need for improved alignment with contemporary macroeconomic indicators.

The revision has been undertaken on the recommendations of a committee constituted by DGCI&S under the Chairmanship of Prof. Nachiketa Chattopadhyay, Professor, Indian Statistical Institute, Kolkata. The Committee examined the existing methodology, data coverage, weighting structure, and compilation practices, and recommended suitable refinements in line with international best practices.

Key Features of the Revised Series (Base: FY 2022–23)

  1. Updated Base Year:
    The new base year FY 2022–23 makes the Indices reflect the current structure of India’s external trade more accurately.
  2. Revised Commodity Basket:
    The coverage and classification of commodities have been reviewed at the Principal Commodity level to better capture emerging and declining trade items.
  3. Revised Weighting Structure:
    Weights have been updated based on trade values of the new base year to reflect the latest value shares in exports and imports.
  4. Improved Methodology:
    Methodological refinements have been introduced in:
    1. Selection of common commodity basket for base year selection (procedure of selection for common commodity basket explained in detail report of the committee).
    2. Treatment of missing unit values (Imputation of missing unit values in base year selection have been explained in detail in the committee report).
  5. Indices Compiled:
    The revised series includes:
    1. Monthly, Quarterly and Annual Indices (Export Unit Value Index,Import Unit Value Index).
    2. Principal Commodity (PC) Classification wise Trade Indices (Export/Import).
    3. Standard International Trade Classification-wise (SITC) Trade Indices.
    4. Broad economic categories-wise (BEC) Trade Indices.
    5. Bilateral and Region-wise Trade Indices of Top 20 Export and Import partner nations of India.
    6. Terms of Trade (Gross terms of trade, Net terms of trade and Income terms of trade).

Rationale for Revision

Over the past decade, India’s trade basket has undergone substantial changes due to emergence of new commodities, technological advancements, Global supply chain restructuring and changes in relative price structures.

The earlier base year (FY 2012–13) no longer adequately reflected the prevailing trade structure. The revision ensures improved relevance, reliability, and analytical usefulness of the Merchandise Trade Indices for policymakers, researchers, and other stakeholders.

Use of the Revised Series

Merchandise Trade Indices compiled by the Directorate General of Commercial Intelligence and Statistics (DGCI&S) are extensively used by key government institutions for economic analysis and policy formulation. The National Accounts Division (NAD) of the Ministry of Statistics and Programme Implementation uses the Export and Import Unit Value Indices as deflators for estimating real exports and imports in GDP compilation. The Reserve Bank of India (RBI) relies on these indices for external sector assessment, balance of payments analysis, and evaluation of price competitiveness. Various Ministries and Government agencies also use them to frame and review trade-related policies and to assess movements in international prices. In addition, academic institutions, research organizations, and economic analysts utilize Merchandise Trade Indices for empirical research, modelling, and analysis of trade dynamics and terms of trade trendson and economic research.

Availability of Data

The revised Merchandise Trade Indices (Base: FY 2022–23) will be released on the official website of DGCI&S. Detailed methodological documentation is available in the Report of the Committee on Revision of Base Year for Merchandise Trade Indices.

Comparison of the new revised Indices (Base Year: 2022-23) with the already released Indices (Base Year : 2012-13) for 2022-23 and 2023-24 is given below.
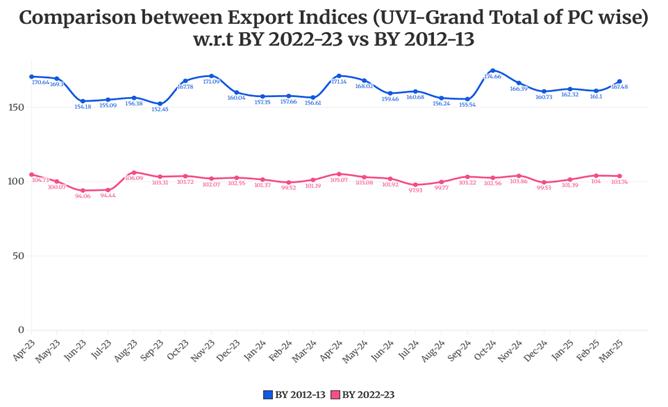
#BY means Base Year.
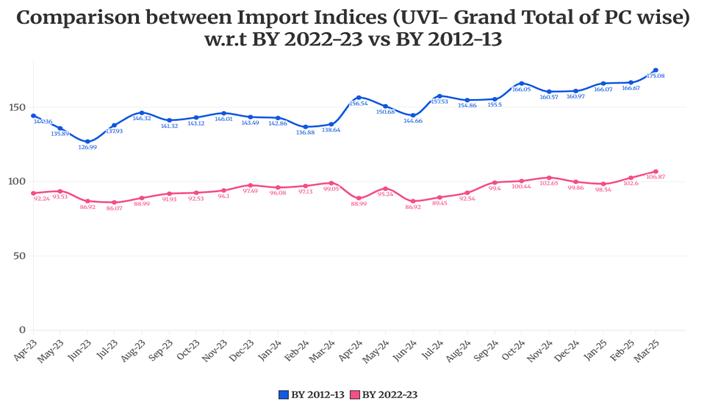
 

#BY means Base Year.

Table: Unit Value Index (UVI) and Quantity Index (QI) during FY 2025-26(Apr-Nov) using FY 2022-23 as base year


Month

Apr_25

May_25

Jun_25

1st Qtr 25-26

Jul_25

Aug_25

Sep_25

2nd Qtr 25-26

Oct_25

Nov_25

Unit Value Index

Export

105.31

99.73

96.31

100.33

99.31

100.55

104.08

101.23

103.78

105.32

Import

92.33

97.97

91.74

94.08

96.34

100.81

108.69

101.93

110.17

106.59

Quantity Index

Export

107.85

104.76

93.88

101.91

103.41

102.64

111.04

105.57

116.19

113.06

Import

138.16

126.61

112.58

125.17

122.47

124.06

126.45

124.32

137.04

121.75

Qtr  means Quarter.

Meaning and interpretation of the Indices

The Unit Value Indices and the Quantity Indices may be interpreted along the following lines.

The Unit Value Index answers the question: What is the growth in the average Unit Value of the items1 traded in the current month with respect to the same month in the Base Year?

So, an Unit Value Index of, say, 120 means that if the items that have been traded in the current month had been traded in the same month of the base year, and if the average price (or unit value) of those items had been Rs.100 in that month of the base year, then the average price (or unit value) of these items in the current month is Rs.120. Or that, there is a 20% increase in the average Unit Value, with respect to the Base Year, of the items that have been traded in the Current Month.

For example, let us suppose 30 items, 10 items each from 3 different Principal Commodities, have been traded in the current month. If these 30 items had been traded in the corresponding month of the base year at an average price of Rs.100, then the average price of these items in the current year is Rs.120.

It is to be noted that there are two successive steps of averaging done here. The first averaging is done over all the items (or ITCHS) of a PC group to arrive at the Index of that PC group. And the second averaging is done over all the PC groups to arrive at the Index at the Grand Total level for all commodities (which is the overall Index for India for a month). In both the stages, a weighted average is taken where the weights are proportional to the importance of the items and the PC groups respectively, and the Laspeyres Formula is used for averaging.

Quantity Indices, say, 200 means that if in the base year on an average 100 units were traded in India in the base year, then in the current year on an average 200 units were traded. However, it must be remembered that averaging quantities are different from averaging prices, since quantities in different units cannot be added directly.

So, the Quantity Indices are calculated by dividing the Value Indices by the Unit Value Indices. For example, if there is an increase in the Value of Export from Rs. 10,000 to Rs. 24,000, then the Value Index is 24000/10000 × 100 = 240. If the Unit Value Index is 120, then the Quantity Index comes to 240/120 × 100 = 200. So, loosely it can be said that, if the value of export has increased 2.4 times and the price of the commodities has increased 1.2 times, then the quantity must have doubled.

However, it may be noted that a very high or low Quantity Index may indicate the presence of Base Effect.

The Interpretation of the Bilateral and Regional Indices can be seen as an extension of the above.

A Unit Value Index of 120 with respect to a country, say Bangladesh, means that if all the items that have been traded with Bangladesh in the current month had been traded in the same month of the base year with the same country, and if the average price (or unit value) of those items had been Rs.100 in that month of the base year, then the average price (or unit value) of these items in the current month is Rs.120.

Similarly, a Quantity Index of 200 with respect to a country, say Bangladesh, means that if in the base year on an average 100 units were traded in India in the base year, then in the current year on an average 200 units were traded.

Comparability of the Indices across time

It is to be noted that the weights in the Index Number formula are fixed across time and there are twelve sets of weights for the twelve months. Hence, comparability of Indices is meaningful only when Indices of same month are compared across years. Different months may attach different weights to the same item, and hence comparing indices of two different months becomes vague and may have little applicability.

Further, the weights of the items that are not present in the trade basket of the current month are distributed to all the items that have been traded in the current month. This distribution is done in proportion to the weights of those items.

For example, let us suppose there are only 3 commodities for trade, say A, B and C. In month May of the Base year, let us suppose that the trade value of A was Rs. 50, B was Rs. 100 and C was Rs. 50. Then the weights assigned to A, B and C in the month of May of the following years would be in the ratio 50 :100 :50. However, in case, C is not traded in the current month, then the weight of C would be distributed proportionately among A and B, again in the ratio 1:2 (since in May the weights of A and B are in the ratio of 50 : 100, i.e., 1 : 2). So, in the current month the weights of A and B would be 3313  and 6623 .

As a result, the weights in any two given months are dependent on exactly the number of items (ITCHS codes) traded in those months. If the items traded are widely different, inference drawn from the comparison of the Indices may be done accordingly. On the other hand, more the similarity in the number of items traded more is the comparability of the two indices.

Net Terms of Trade:

Net Terms of Trade also called commodity Terms of Trade is defined as a ratio of export prices to import prices.

Let say 2022-23 be the base year and 2023-24 be the final year. We express both export and import prices in 2022-23 as 100. Now, suppose that at the end of 2023-24, it is found that the index of export prices decreased to 90 and index of import prices roses to 150. Then the Net Terms of Trade has changed to 90100150100=35 . Then terms of trade as index=35*100=60 . It implies that terms of trade of the country have decreased by about 40% in 2023-24 as compared with 2022-23. It thus shows a deterioration or a worsening of the terms of trade of the country.

If the index of export prices has risen to 150 and that of import prices had risen to 120, then the net terms of trade would have changed to 150120*100=125 . This implies an improvement in the net terms of trade of the country by 25% in 2023-24 over 2022-23.

Gross Terms of Trade:

Gross Terms of Trade is the ratio of physicalquantity of import to physical quantity of export.

Let say 2022-23 be the base year. In that year, the quantities export and import are denoted by 100. Now, suppose that in the year 2023-24, the index of quantity of import was 150 and that of quantity of export was 120. Then the gross terms of trade is given by 150100120100=54,  in terms of percentage =54*100=125 . This implies that there was an improvement of gross terms of trade by 25% in 2023-24 compared to 2022-23.

Income Terms of Trade: Income Terms of Trade is defined as- Net Terms of Trade multiplied by quantity of export.

Topics

Acts Income Tax