

Loading...

⚠ ✕
❮ Top
☎ Help
☰
×

By creating an account you can:

Logo TaxTMI
Call Us / Help / Feedback✕

Contact Us At :

✉ E-mail: [email protected]

✆ To Call / Whatsapp, Check Contact Us

FAQs :

To know Frequently Asked Questions, Check FAQs

Most Asked Video Tutorials :

For more tutorials, Check Video Tutorials

Submit Feedback/Suggestion :

Email :
Please provide your email address so we can follow up on your feedback.
Category :
Description :
Min 15 characters 0/2000
Make Most of Text Search ✕
  1. Checkout this video tutorial: How to search effectively on TaxTMI.
  2. Put words in double quotes for exact word search, eg: "income tax"
  3. Avoid noise words such as : 'and, of, the, a'
  4. Sort by Relevance to get the most relevant document.
  5. Press Enter to add multiple terms/multiple phrases, and then click on Search to Search.
  6. Text Search
  7. The system will try to fetch results that contains ALL your words.
  8. Once you add keywords, you'll see a new 'Search In' filter that makes your results even more precise.
  9. Text Search
╳
Add to...
You have not created any category. Kindly create one to bookmark this item!
✕
Create New Category
Hide
Title :
Description :
❮❮ Hide
❮ Default View
Expand ❯❯
Close ✕
🔎 Filters / Advanced Search ❯
TEXT

Press 'Enter' to add multiple search terms. Rules for Better Search

Search In
Main Text + AI Text ❯
  • Main Text
  • Main Text + AI Text
  • AI Text
Category: ?
Categorized by AI
---- All Categories ---- ❯
  • ---- All Categories ----
  • Income Tax
  • GST
  • Customs, DGFT & SEZ
  • FEMA & RBI
  • Corp. Laws, SEBI & IBC
  • PMLA, Black Money & ED
  • Budget
  • News and Press Release
  • PTI News
Month:
---- All Months ---- ❯
  • ---- All Months ----
  • January
  • February
  • March
  • April
  • May
  • June
  • July
  • August
  • September
  • October
  • November
  • December
Year:
---- All Years ---- ❯
  • ---- All Years ----
  • 2026
  • 2025
  • 2024
  • 2023
  • 2022
  • 2021
  • 2020
  • 2019
  • 2018
  • 2017
  • 2016
  • 2015
  • 2014
  • 2013
  • 2012
  • 2011
Sort By: ?
In Sort By 'Default', exact matches for text search are shown at the top, followed by the remaining results in their regular order.
Relevance Default Date
☰   Show Results ❯
    DRI seizes more than 9 kg methamphetamine in intensified crackdown on synthetic drug trafficking in Bhopal; One held
    Growth with Responsibility: The Next Balance Sheet - Special Address by Shri Swaminathan J, Deputy Governor, Reserve Bank of India at the FE Modern BF...
    India–New Zealand FTA to Come into Force on 20th October 2026 on Vijay Dashmi, Opening New Opportunities for Indian Exporters
    DRI foils major ganja trafficking attempt; seizes 591 kg cannabis smuggled from Nepal
    DRI seizes more than 43 lakh foreign-origin smuggled cigarettes worth Rs. 8.64 crore in Mizoram; one arrested
    Saturation Campaign of Financial Inclusion (FI) Schemes to Run from 21st October 2026 to 31st December 2026
    DRI detects 13 kg foreign-origin gold worth around Rs. 19.41 crore and dismantles a gold smuggling syndicate in Gujarat; three arrested
    India and New Zealand sign Memorandum of Cooperation (MoC) on Electronic Origin Data Exchange to Facilitate Bilateral Trade Under the India-New Zealan...
    DRI seizes over seven kg amphetamine and three kg cocaine as it intensifies crackdown on drug trafficking in country; three arrested
    DRI seizes 13 kg foreign-origin gold worth around Rs. 19.41 crore and dismantles a gold smuggling syndicate in Gujarat; three arrested
    Department of Commerce Organises “Leveraging FTAs” Outreach Programme in Jaipur to Strengthen Export Opportunities
    Central Bureau of Narcotics (CBN) organises five drug awareness programmes for MP youth Mission Yuva Raksha
    DRI seizes massive 137 kg consignment of crystal meth; busts coastal drug trafficking network; 4 arrested in Tamil Nadu
    Optimization of Statutory Branch Auditors (SBAs) Costs and Acceleration of Centralized Audit Frameworks
    Clarification on Legislative Developments concerning Government’s shareholding in IDBI
    Introduction of e-Invoicing Facility for Recipient Generated Self Invoices under Reverse Charge Mechanism for Domestic Supplies from Unregistered Pers...
    DFS Organises Workshop on Reservation Policy for Public Sector Banks, Public Sector Insurance Companies and Public Financial Institutions
    APEDA Facilitates Export of 1.755 MT of Organic Palmyra Jaggery Powder from Tamil Nadu to Bulgaria
    Union Commerce and Industry Minister Shri Piyush Goyal Launches National Strategic Trade Command Centre at Vanijya Bhawan
    Union Minister for Finance & Corporate Affairs Smt. Nirmala Sitharaman participates in the 114th meeting of the Development Committee Plenary of the W...
❮
❯
❯❯
Maximize Maximize Maximize
0 / 200
Expand Note
Add to Folder

No Folders have been created

+

Are you sure you want to delete "My most important" ?

NOTE:

News
Showing Results for :
Reset Filters
Results Found:
Show All Summaries Hide All Summaries
October 22, 2026
Show AI Summary
Synthetic drug trafficking enforcement led to methamphetamine seizure and arrest following intelligence-based interception at an inter-city bus terminal.
Intelligence-led enforcement against synthetic drug trafficking resulted in the seizure of 9.139 kg of crystalline methamphetamine and the arrest of a bus passenger following interception at an inter-city bus terminal. The substance was concealed in clothing packets within trolley bags, field-tested and seized under the Narcotic Drugs and Psychotropic Substances Act, 1985. Synthetic narcotics trafficking is identified as using inter-city transport networks, cross-border routes and coastal corridors.
October 21, 2026
Show AI Summary
Growth with sound controls requires regulated institutions to retain accountability, protect trust, and respond rapidly to digital risks.
Financial-sector growth in an increasingly digital and interconnected system must be accompanied by a control environment commensurate with the pace and nature of growth. Digital onboarding, AI-led underwriting and autonomous workflows may lower costs, improve customer experience and widen access, but not every process friction is inefficiency. Technology cannot eliminate underlying risk. Before a manual check is automated or removed, institutions should identify the risk it controlled and determine where that control will reside. Process outsourcing through fintechs, external platforms or third-party models does not transfer responsibility associated with the regulated institution's licence.
October 21, 2026
Show AI Summary
Duty-free market access under the India-New Zealand Free Trade Agreement expands exports, services mobility, agricultural cooperation, and trade safeguards.
New Zealand eliminates customs duties on all tariff lines for Indian exports, providing 100% duty-free access for sectors including textiles, leather, engineering goods, automobiles, chemicals, pharmaceuticals, agricultural products and processed foods. Sensitive products, including dairy, sugar, edible oils and key agricultural commodities, remain excluded from concessions. Rules of origin, bilateral safeguard measures and anti-circumvention provisions are intended to ensure that preferential benefits reach genuine Indian exporters and to protect vulnerable agricultural and rural interests. Tariff Rate Quotas for apples, kiwifruit and Ma nuka honey are linked to delivery of Agricultural Productivity Partnership Action Plans.
October 21, 2026
Show AI Summary
Cross-border cannabis trafficking enforcement targets truck-based concealment methods, with narcotics and transport vehicle seized under NDPS law.
Intelligence-led narcotics enforcement resulted in the seizure of 591.3 kg of ganja concealed in specially fabricated compartments of a truck suspected to have carried contraband from Nepal into Uttar Pradesh. Surveillance based on specific intelligence led to interception of the vehicle, from which 81 packets were recovered from cavities above the hood and behind the driver's seat. The ganja consignment and the transport vehicle were seized under the Narcotic Drugs and Psychotropic Substances Act, 1985.
October 21, 2026
Show AI Summary
Cross-border cigarette smuggling triggers customs seizure where foreign-origin packs lack mandatory pictorial health warnings and are transported illicitly.
Cross-border cigarette smuggling was detected through intelligence-led surveillance on the Champhai-Aizawl Road in Mizoram. A truck was intercepted at Tuirial village, resulting in recovery of 432 cases containing 43,20,000 sticks of foreign-origin "Patron" cigarettes. The packets lacked mandatory pictorial and health warnings under the Cigarettes and Other Tobacco Products Act, 2003. The cigarettes and truck were seized under the Customs Act, 1962, and the driver was arrested.
October 21, 2026
Show AI Summary
Financial inclusion saturation campaign organises bank camps for insurance, pension, account access, KYC, fraud awareness, and agricultural credit enrolment.
The financial inclusion saturation campaign will operate through bank camps providing enrolment in insurance and pension schemes, opening of basic bank accounts, Aadhaar seeding, re-KYC, central KYC identifier generation, and nomination updates. Camps will also conduct awareness sessions on financial-inclusion schemes, digital fraud and unclaimed financial assets, source agricultural credit applications for eligible farmer-beneficiaries, and facilitate crop-insurance enrolment for the upcoming Rabi season.
October 21, 2026
Show AI Summary
Gold smuggling enforcement targets airport concealment, illegal melting and jewellery-market disposal within organised customs-law networks.
Customs enforcement action concerned an organised gold-smuggling syndicate that allegedly imported foreign-origin gold through airports by concealing it as rhodium-coated wires, within trolley-bag linings and as gold paste. The distribution chain allegedly involved handlers, intermediaries, an illegal melting facility and cash sales through a jewellery outlet. Searches uncovered gold, evidence of illegally melted gold, undocumented bars, and records of smuggled-gold dealings, while identifying a financier and other network participants.
October 21, 2026
Show AI Summary
Electronic origin data exchange supports customs cooperation, trade facilitation, and efficient use of bilateral trade preferences.
Electronic origin data exchange for trade in goods is established through a Memorandum of Cooperation between the Indian and New Zealand customs administrations under the India-New Zealand Free Trade Agreement. The arrangement provides for advance electronic sharing of origin data, strengthening bilateral customs cooperation and supporting implementation of trade-facilitation measures. The mechanism supports effective use of FTA trade preferences and facilitates delivery of negotiated benefits to eligible businesses in both countries.
October 19, 2026
Show AI Summary
Narcotics trafficking enforcement led to airport and road interceptions, baggage concealment detection, seizures, and arrests under the NDPS framework.
Narcotics trafficking enforcement under the Narcotic Drugs and Psychotropic Substances Act, 1985, involved intelligence-led interceptions at Bengaluru and Delhi airports and near Nagpur. Passenger baggage and a backpack were examined, leading to the seizure of amphetamine and cocaine and the arrest of three passengers. The recoveries included amphetamine concealed in baggage, a ladies' suit and a backpack lining, and cocaine contained in transparent packets within baggage.
October 19, 2026
Show AI Summary
Gold smuggling syndicate enforcement traces concealed imports through airport handlers, illicit melting, and jewellery-market disposal under customs law.
Directorate of Revenue Intelligence enforcement action identified an organised gold-smuggling syndicate importing foreign-origin gold through Ahmedabad and Surat airports, followed by handover to handlers, intermediary routing, illegal melting, and cash-based supply through an Ahmedabad jewellery outlet. Further searches recovered undocumented foreign-origin gold bars and records concerning smuggled gold linked to a Dubai-based financier. The investigation identified interconnected roles across the movement, processing, and disposal of smuggled gold; three persons were arrested under the Customs Act, 1962.
October 19, 2026
Show AI Summary
Free trade agreement utilisation requires origin compliance, product standards, and documentation to secure preferential export market access.
Effective FTA utilisation requires businesses to identify eligible products and markets, assess tariff preferences and rules of origin, and meet applicable quality, certification, documentation and importing-country requirements. Preferential access under agreements with the UAE, Australia, EFTA countries and the United Kingdom remains subject to each agreement's provisions and implementation status. Tariff preferences may improve price competitiveness and facilitate participation in international supply chains where product- and partner-specific conditions are satisfied.
October 19, 2026
Show AI Summary
Drug prevention awareness initiatives engage students through health education, interactive activities and pledges supporting a drug-free society.
Mission Yuva Raksha advances preventive drug awareness and demand-reduction efforts among students through programmes at educational institutions in Madhya Pradesh. Sessions addressed the harmful effects of substance abuse on physical and mental health, education, family life and careers, supported by interactive learning activities. Participants were encouraged to avoid drugs, adopt healthy lifestyles, take pledges and support awareness initiatives in their schools, families and communities. Preventive education and youth engagement complement enforcement-oriented work through informed choices and community-based resistance to substance abuse.
October 19, 2026
Show AI Summary
Coastal narcotics trafficking enforcement addresses suspected maritime methamphetamine smuggling through seizure, asset recovery, and arrests under drug-control law.
Intelligence-led narcotics enforcement addressed suspected coastal storage and maritime transfer of methamphetamine to Sri Lanka. Searches recovered crystal methamphetamine concealed in foil packets within duffel bags, which was seized under the Narcotic Drugs and Psychotropic Substances Act, 1985. Searches also recovered suspected drug-sale proceeds and vehicles allegedly used in transportation. Persons allegedly involved in organising coastal export, transport, storage and logistics were arrested and remanded to judicial custody.
October 17, 2026
Show AI Summary
Centralised audit framework targets lower physical branch audit coverage while preserving regulatory oversight and maintaining remuneration.
For FY 2026-27, audit remuneration is to remain at existing levels. Member banks are advised to accelerate a centralised audit framework to improve cost efficiency while retaining comprehensive risk oversight. Physical statutory branch audit coverage should be reduced to cover 50% of total business, apart from centralised treasury audits. Audit coverage must align with SEBI listing and disclosure requirements and RBI guidelines, supported by a Board-approved policy for the centralised audit roadmap.
October 17, 2026
Show AI Summary
Promissory estoppel cannot prevent Government shareholding dilution where enacted legislation imposes no restriction on strategic disinvestment.
Government shareholding in IDBI may be reduced or divested because the IDBI (Repeal) Act, 2003 contains no restriction on dilution of the Government's stake. A proposed amendment to limit dilution was rejected and not incorporated into the enacted law. Parliamentary statements cannot override statutory text, and promissory estoppel cannot be invoked on the basis of legislative debate statements to prevent dilution of Government shareholding. Successive Union Budget speeches also reflected a policy of transformation and strategic disinvestment of IDBI Bank.
October 16, 2026
Show AI Summary
Recipient-generated e-invoicing under reverse charge enables eligible taxpayers to obtain IRNs for domestic unregistered supplies and imported services.
Eligible active registered recipients meeting the applicable aggregate annual turnover threshold may report recipient-generated self-invoices for specified reverse-charge domestic supplies from unregistered persons and imports of services. RCMDOM and RCMIMP must be selected as the relevant e-invoice supply types when reporting through an authorised Invoice Registration Portal. Submission and validation of prescribed invoice particulars would generate an Invoice Reference Number, subject to applicable GST provisions, notifications and e-invoice specifications.
October 16, 2026
Show AI Summary
Reservation Policy Implementation in public financial institutions was examined through capacity building, practical deliberations, and measures for consistent application.
Implementation of the Government of India's Reservation Policy across public sector banks, public sector insurance companies, sectoral regulators and public financial institutions was addressed through capacity building to support uniform and effective application. Deliberations considered practical implementation issues, operational challenges and actionable measures for consistent policy application, alongside related welfare measures and interactive discussion of implementation questions.
October 16, 2026
Show AI Summary
Organic agricultural export certification supports overseas market access for Palmyra Jaggery Powder through export-oriented producer linkages.
APEDA facilitated the maiden sea export of NPOP- and EU-certified organic Palmyra Jaggery Powder from Tamil Nadu to Bulgaria. The initiative seeks to diversify India's organic export basket, create market linkages for traditional Palmyra-based products, and improve producer access through export-oriented value chains. It covers organic cultivation and reports improved price realisation for participating farmers and the manufacturer compared with the domestic market. APEDA supports certified organic and value-added agricultural exports through market development, quality compliance, and overseas buyer linkages.
October 16, 2026
Show AI Summary
Data-driven trade governance enables integrated monitoring, application analysis and evidence-based policy inputs through the National Strategic Trade Command Centre.
The National Strategic Trade Command Centre provides an integrated analytics and visualisation platform consolidating trade data to monitor trade indicators, scheme performance, application pendency, processing timelines, regional trends and compliance-related parameters. It enables analysis across national trade performance, Regional Authorities, schemes, products, destination markets and individual applications, subject to role-based access permissions. Initial dashboards cover key trade-facilitation and regulatory processes, including SCOMET, export promotion schemes, certificates of origin, importer-exporter registration and restricted imports and exports.
October 16, 2026
Show AI Summary
Private capital mobilisation should use competitive financing, guarantees and risk mitigation to expand productive employment and productivity.
Private capital mobilisation is treated as essential to employment generation and productivity growth. Private enterprises, MSMEs and startups should remain central to job creation, with financing assessed by employment and productivity outcomes rather than volume. Guarantees, risk-mitigation instruments, local-currency financing and lower transaction costs are identified as means to expand affordable and predictable access to capital. Methodologies underlying governance indicators should be transparent, objective, evidence-based and responsive to diverse development experiences.

News

Back

All News

Showing Results for :
Reset Filters
No Records Found

News

Back

All News

Recommendations of the 55th Meeting of the GST Council

December 21, 2024

Contents
Notifications
Circulars
Forms
Acts
Rules & Regulations
Plus +
Summary
Note

Note

-

Bookmark

Print

Print

GST Council recommends reduction in GST rate on Fortified Rice Kernel (FRK), classifiable under 1904, to 5%

GST council also recommends to fully exempt GST on gene therapy

GST Council recommends exemption of GST on contributions by general insurance companies from third-party motor vehicle premiums for Motor Vehicle Accident Fund

GST Council recommends no GST on transaction of vouchers as they are neither supply of goods nor supply of services. The provisions related to vouchers is also being simplified.

GST Council clarifies that no GST is payable on ‘penal charges’ levied and collected by banks and NBFCs from borrowers for non-compliance with loan terms

GST Council recommends reduction of payment of pre-deposit for filing an appeal before the Appellate Authority in respect of an order passed which involves only penalty amount

Jaisalmer, Rajasthan, 21 st December 2024

The 55th GST Council met under the Chairpersonship of Union Minister for Finance & Corporate Affairs Smt. Nirmala Sitharaman in Jaisalmer, Rajasthan, today.
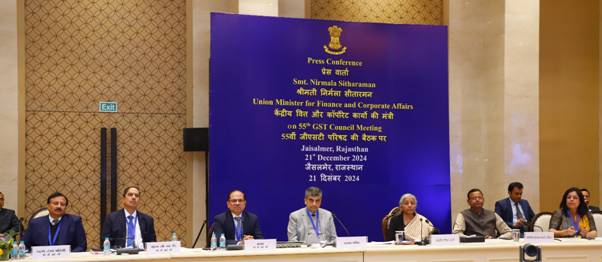
The meeting was also attended by Union Minister of State for Finance Shri Pankaj Chaudhary, Chief Ministers of Goa, Haryana, Jammu and Kashmir, Meghalaya and Odisha; Deputy Chief Ministers of Arunachal Pradesh, Bihar, Madhya Pradesh, and Telangana; besides Finance Ministers of States & UTs (with legislature) and senior officers of the Ministry of Finance & States/ UTs.
The GST Council inter-alia made the following recommendations relating to changes in GST tax rates, provide relief to individuals,measures for facilitation of trade and measures for streamlining compliances in GST.

A. Changes in GST rates of goods

GOODS

  1. To reduce the GST rate on Fortified Rice Kernel (FRK), classifiable under 1904, to 5%.
  2. To exempt GST on gene therapy.
  3. To extend IGST exemption to systems, sub-systems, equipment, parts, sub-parts, tools, test equipment, software meant assembly/manufacture of LRSAM system under Notification 19/2019-Customs.
  4. To reduce the rate of Compensation Cess to 0.1% on supplies to merchant exporters at par with GST rate on such supplies.
  5. To exempt from IGST imports of all equipment and consumable samples by Inspection Team of the International Atomic Energy Agency (IAEA) subject to specified conditions.
  6. To extend the concessional 5% GST rate on food inputs of food preparations under HSN 19 or 21 that are supplied for food preparations intended for free distribution to economically weaker sections under a government program subject to the existing conditions.

SERVICES

  1. To bring supply of the sponsorship services provided by the body corporates under Forward Charge Mechanism.
  2. To exempt GST on the contributions made by general insurance companies from the third-party motor vehicle premiums collected by them to the Motor Vehicle Accident Fund, constituted under section 164B of the Motor Vehicles Act, 1988. This fund is constituted for providing compensation/ cashless treatment to the victims of road accidents including hit and run cases.
  3. To omit the definition of declared tariff and suitably amend the definition of specified premises (from the services rate and exemption notifications) to link it with actual value of supply of any unit of accommodation provided by the hotel and to make the rate of GST applicable on restaurant services in such hotels, for a given financial year, dependent upon the ‘value of supply’ of units of accommodation made in the preceding financial year, i.e. 18% with ITC if the ‘value of supply’ exceeded Rs. 7,500 for any unit of accommodation in the preceding financial year, and 5% without ITC otherwise. Further, to give an option to pay tax on restaurant service in hotels at the rate of 18% with ITC, if the hotel so chooses, by giving a declaration to that effect on or before the beginning of the financial year or on obtaining registration. The above changes to be made effective from 01.04.2025 to avoid any transition difficulties.
  4. To exclude taxpayers registered under composition levy scheme from the entry at Sr. No. 5AB introduced vide Notification No. 09/2024-CTR dated 08.10.2024 vide which renting of any commercial/ immovable property (other than residential dwelling) by unregistered person to registered person was brought under reverse charge mechanism. Further, to regularize the period from the date when the notification No. 09/2024-CTR dated 08.10.2024, became effective i.e. from 10.10.2024 till the date of issuance of the proposed notification on “as is where is” basis.

Other changes relating to goods and services

  1. To increase the GST rate from 12% to 18 % on sale of all old and used vehicles, including EVs other than those specified at 18% -Sale of old and used petrol vehicles of engine capacity of 1200 cc or more & of length of 4000 mm or more; diesel vehicles of engine capacity of 1500 cc or more & of length of 4000 mm and SUVs.[Note: GST is applicable only on the Value that represents Margin of the Supplier, that is, the difference between the Purchase price and Selling price (depreciated value if depreciation is claimed) and not on the value of the vehicle. Also, it is not applicable in case of unregistered persons.]
  2. To clarify that Autoclaved Aerated Concrete (ACC) blocks containing more than 50% fly ash content will fall under HS 6815 and attract 12% GST.
  3. To clarify that pepper whether fresh green or dried pepper and raisins when supplied by an agriculturist is not liable to GST.
  4. To amend the definition of ‘pre-packaged and labelled’ to cover all commodities that are intended for retail sale and containing not more than 25 kg or 25 litre, which are ‘pre-packed’ as defined under the Legal Metrology Act, or a label affixed thereto is required to bear the declarations under the provisions of the Act and rules.
  5. To clarify that ready to eat popcorn which is mixed with salt and spices are classifiable under HS 2106 90 99 and attracts 5% GST if supplied as other than pre-packaged and labelled and 12% GST if supplied as pre-packaged and labelled. However, when popcorn is mixed with sugar thereby changing its character to sugar confectionary (eg caramel popcorn), it would be classifiable under HS 1704 90 90 and attract 18% GST. It has been decided to regularise the issues for the past on “as is where is” basis.(Note: There is no new imposition of any tax in this regard and is merely a clarification as certain field units were demanding different tax rates on the same. Therefore, it is a clarification being recommended by the GST Council to settle the disputes arising out of interpretation.)
  6. To clarify that the Explanation in Sl. No. 52B in notification No. 1/2017- Compensation Cess (Rate) dated 28.6.2017 regarding ground clearance is applicable with effect from 26.07.2023.
  7. To clarify that RBI regulated Payment Aggregators are eligible for the exemption under entry at Sl. No. 34 of notification No. 12/2017-CT(R) dated 28.06.2017 since they fall within the ambit of ‘acquiring bank’ as defined in the said entry.  To also clarify that this exemption does not cover payment gateway (PG) and other fintech services which do not involve settlement of funds.
  8. To clarify that no GST is payable on the ‘penal charges’ levied and collected by banks and NBFCs from borrowers for non-compliance with loan terms.

B.  MEASURES FOR FACILITATION OF TRADE

1.   Amendment in Schedule III of CGST Act, 2017

  • To insertclause (aa) in paragraph 8 of Schedule III of the CGST Act, 2017 w.e.f.01.07.2017, to explicitly provide that supply of goods warehoused in a Special Economic Zone (SEZ) or Free Trade Warehousing Zone (FTWZ) to any person before clearance of such goods for exports or to the Domestic Tariff Area, shall be treated neither as supply of goods nor as supply of services.
  • This brings transactions relating to supply of goods warehoused in SEZ/FTWZ at par with the existing provision in GST for transactions in Customs bonded warehouse.

2.  Issues pertaining to taxability of Vouchers

In a significant move to address long-standing concerns regarding the taxability of vouchers under GST, the GST Council made the following recommendations:

  1. To omit sections 12(4) and 13(4) from CGST Act, 2017 and rule 32(6) from CGST Rules, 2017 to resolve ambiguities in the treatment of vouchers.
  2. To issue clarification on the following issues:

(a) Transactions in vouchers shall be treated neither as a supply of goods nor as a supply of services.

(b) Distribution of vouchers on principal-to-principal basis shall not be subject to GST. However, where vouchers are distributed on principal-to-agent basis, the commission/fee or any other amount charged by the agent for such distribution is taxable under GST.

(c) Additional services such as advertisement, co-branding, marketing and promotion, customization and technology support, customer support etc. related to vouchers would be leviable to GST on the amount paid for these services.

(d) Unredeemed vouchers (breakage) would not be considered as supply under GST and no GST is payable on income booked in the accounts in respect of breakage.

3. Issuance of clarifications through the circulars to remove ambiguity and legal disputes in certain issues.

  • To issue circulars to provide clarity in the following issues due to varied interpretations by the field formations:

(i) Clarification regarding requirement of reversal of Input Tax Credit by electronic commerce operators in respect of supplies made under section 9(5) of CGST Act, 2017: The GST Council recommended that no proportional reversal of ITC under section 17 (1) or section 17 (2) of CGST Act, 2017 is required to be made by the ECO in respect of supplies for which they are required to pay tax under section 9(5) of CGST Act, 2017.

(ii) Clarification on availability of Input Tax Credit as per section 16(2)(b) of CGST Act, 2017 in respect of goods which have been delivered by the supplier at his (supplier’s) place of business : The GST Council recommended to clarify that in an Ex-Works contract, where goods are delivered by the supplier to the recipient or a transporter at the supplier's place of business, and the property in goods transfers to the recipient at that point, the goods are considered to be "received" by the recipient under section 16(2)(b) of CGST Act, 2017 and the recipient may claim Input Tax Credit (ITC) on such goods, subject to the conditions outlined in Sections 16 and 17 of the CGST Act, 2017.

(iii) Clarification regarding applicability of late fee for delay in furnishing of FORM GSTR-9C and providing waiver of late fee on delayed furnishing of FORM GSTR-9C for the period from 2017-18 to 2022-23:

(a) The GST Council recommended to clarify through a circular that the late fee under Section 47(2) of the CGST Act, 2017 is leviable for the delay in filing the complete annual return under Section 44 of the CGST Act, 2017, which includes both FORM GSTR-9 (Annual Return) and FORM GSTR-9C (Reconciliation Statement), where applicable.

(b) For the annual returns pertaining to the period 2017-18 to 2022-23, the GST Council also recommended to issue notification under section 128 of CGST Act, 2017 for waiver of the amount of late fee for delayed filing of FORM GSTR-9C, which is in excess of the amount of late fee payable till the date of filing of FORM GSTR-9 for the said financial years, provided the said FORM GSTR-9C is filed on or before 31st March 2025.

C.  MEASURES FOR STREAMLINING COMPLIANCES IN GST

1.   Insertion of new provision for Track and Trace Mechanism

  • To insert an enabling provision in CGST Act, 2017 through Section 148A so as to empower the Government to enforce the Track and Trace Mechanism for specifiedevasion prone commodities.
  • The system shall be based on a Unique Identification Marking which shall be affixed on the said goods or the packages thereof. This will provide a legal framework for developing such a system and will help in implementation of mechanism for tracing specified commodities throughout the supply chain.

2.  Clarification regarding recording of correct details of name of the State of the un-registered recipient as well as correct declaration of place of supply in respect of supply of 'Online Services’

  • To clarify that in respect of supply of ‘Online Services’ such as supply of online money gaming, OIDAR services, etc. to unregistered recipients, the supplier is required to mandatorily record the name of the State of the unregistered recipient on the tax invoice and such name of State of recipient shall bedeemed to be the address on record of the recipient for the purpose of section 12(2)(b) of IGST Act, 2017 read with proviso to rule 46(f) of CGST Rules, 2017

D.  OTHER MEASURES PERTAINING TO LAW & PROCEDURE

1.   Amendment in section 17(5)(d) of CGST Act, 2017

2.   Amendment in section 107 and section 112 of CGST Act, 2017 to provide for payment of pre-deposit for filing an appeal in respect of an order passed which involves only penalty amount.

  • To amend the proviso to section 107(6) of CGST Act, 2017 providing for payment of pre-deposit at 10% instead of 25 %for filing appeals before Appellate Authority in cases involving only demand of penalty without involving the demand of tax.
  • To insert a new proviso to section 112(8) of CGST Act, 2017 providing for payment of pre-deposit at 10% for filing appeals before Appellate Tribunal in cases involving only demand of penalty without involving the demand of tax.

3. Amendment in section 2(69) of CGST Act, 2017 to insert an Explanation regarding definitions of Local Fund and Municipal Fund: To amend clause (c) of section 2(69) of CGST Act, 2017 and to insert an Explanation under the same to provide for definitions of the terms ‘Local Fund’ and ‘Municipal Fund’ used in the said clause.            

4. Amendment in provisions pertaining to Input Services Distributor (ISD) mechanism under CGST Act, 2017 and CGST Rules, 2017

5.   Provision for grant of Temporary Identification Number by Tax Officers to persons, not liable to be registered otherwise

6.  Amendment in the field ‘category of registered person’ for taxpayers who opted for composition levy through FORM CMP-02

7. Amendment in CGST Act, 2017 and CGST Rules, 2017 in respect of functionality of Invoice Management System (IMS)

  • The GST Council recommended inter-alia-

(i) To amend section 38 of CGST Act, 2017 and rule 60 of CGST Rules, 2017 to provide a legal framework in respect of generation of FORM GSTR-2B based on the action taken by the taxpayers on the Invoice Management System (IMS).

(ii) To amend section 34(2) of CGST Act, 2017, to specifically provide for requirement of reversal of input tax credit as is attributable to a credit note, by the recipient, to enable the reduction of output tax liability of the supplier.

(iii) To insert a new rule 67B in CGST Rules, 2017, to prescribe the manner in which the output tax liability of the supplier shall be adjusted against the credit note issued by him.

(iv) To amend section 39 (1) of CGST Act, 2017 and rule 61 of CGST Rules, 2017 to provide that FORM GSTR-3B of a tax period shall be allowed to be filed only after FORM GSTR-2B of the said tax period is made available on the portal.

E. OTHER MEASURES:

  • The GST Council approved the recommendation of the committee of officers suggesting measures for the various issues raised by the States in respect of issues pertaining to IGST settlement and asked the committee to conclude the desired changes by March, 2025.
  • The GST Council took note of the procedural rules proposed for the internal functioning of the GSTAT, which would be notified after examination by the Law Committee. This would help in operationalization of the GSTAT.
  • The Council also decided to extend the time frame for the Group of Ministers on the restructuring of the GST Compensation till 30th June, 2025.
  • On the request of State of Andhra Pradesh the Council recommended that a Group of Ministers be constituted to examine the legal and structural issues, and recommend a uniform policy on imposition of levy in case of a natural disaster/calamity in the State.

The issue of whether charges collected by municipalities for granting FSI including additional FSI, chargeable to GST on reverse charge basis was brought up in the Council. The matter was deferred for further examination on the behest of the Central Government on the ground that this amount relates to Municipalities or local authority.

Note: The recommendations of the GST Council have been presented in this release containing major item of decisions in simple language for information of the stakeholders. The same would be given effect through the relevant circulars/ notifications/ law amendments which alone shall have the force of law.

-----

Archive: GST Council Meetings 


Topics

Acts Income Tax