Accredited investor eligibility expands through securities-market exposure, while alternative investment fund disputes require prescribed resolution a...
Customs Assessment Portal centralises classification and valuation guidance to support consistent, transparent and informed compliance across stakehol...
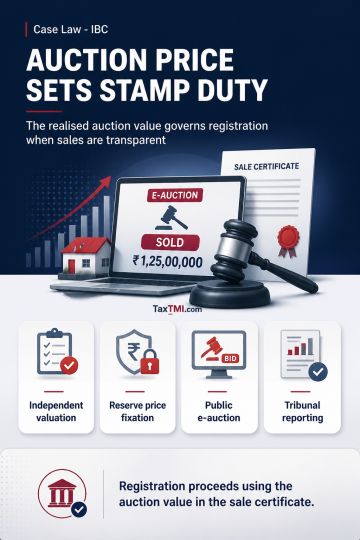
Stamp duty on a sale certificate issued following an insolvency liquidation e-auction is determined by the auction value where the process establishes the assets' true market value. The expression "Civil Court" in Article 16 extends to an auction conducted by a liquidator appointed under the insolvency framework, following independent valuation, reserve-price fixation, public e-auction and reporting to the Tribunal. An ASR-based valuation cannot displace the realised auction value without a valid basis to find intentional suppression or reduction of value to evade stamp duty. Registration is consequently to proceed on the auction value recorded in the liquidator's sale certificate.
Stamp duty on a sale certificate issued following an insolvency liquidation e-auction is determined by the auction value where the process establishes the assets' true market value. The expression "Civil Court" in Article 16 extends to an auction conducted by a liquidator appointed under the insolvency framework, following independent valuation, reserve-price fixation, public e-auction and reporting to the Tribunal. An ASR-based valuation cannot displace the realised auction value without a valid basis to find intentional suppression or reduction of value to evade stamp duty. Registration is consequently to proceed on the auction value recorded in the liquidator's sale certificate.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI