Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
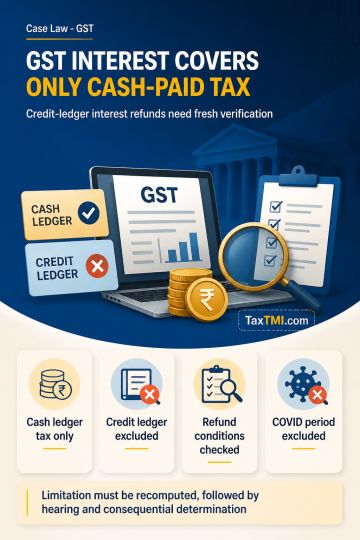
Retrospective operation of the substituted proviso to section 50(1) confines GST interest on delayed tax payment to the tax discharged through the electronic cash ledger, excluding the component paid by utilising input tax credit. Refund claims for interest paid on the credit-ledger component require verification of statutory conditions, payment and eligible quantum. Refund limitation cannot be introduced as a decisive appellate ground without notice and an effective opportunity to address the relevant date, computation and applicable exclusions. Limitation must be recomputed under section 54 after applying the notified exclusion of the specified COVID-19 period, followed by a hearing and consequential determination.
Retrospective operation of the substituted proviso to section 50(1) confines GST interest on delayed tax payment to the tax discharged through the electronic cash ledger, excluding the component paid by utilising input tax credit. Refund claims for interest paid on the credit-ledger component require verification of statutory conditions, payment and eligible quantum. Refund limitation cannot be introduced as a decisive appellate ground without notice and an effective opportunity to address the relevant date, computation and applicable exclusions. Limitation must be recomputed under section 54 after applying the notified exclusion of the specified COVID-19 period, followed by a hearing and consequential determination.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4916