Cross-segment derivatives manipulation: integrated order patterns can support interim restraints, while director liability requires responsibility, co...
Power bank definition limits the customs-duty exclusion, preserving concessional treatment for stationary, grid-scale and industrial battery storage s...
Packing-material input credits support inverted-duty refunds for packaged tea, while rate-reduction and concessional-supply circulars remain inapplica...
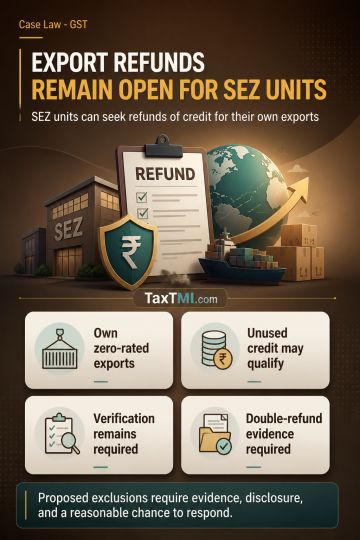
SEZ units may seek refund of eligible unutilised input tax credit distributed through an Input Service Distributor where the credit is attributable to their own zero-rated exports without payment of integrated tax. The supplier-specific procedure for direct SEZ supplies does not automatically bar such claims. Refund eligibility remains subject to verification, statutory conditions and quantification. A proposed exclusion for alleged prior supplier refund requires cogent documentary evidence, disclosure to the claimant and a reasonable opportunity to respond; supplier applications or unexplained back-office records alone do not establish double refund.
SEZ units may seek refund of eligible unutilised input tax credit distributed through an Input Service Distributor where the credit is attributable to their own zero-rated exports without payment of integrated tax. The supplier-specific procedure for direct SEZ supplies does not automatically bar such claims. Refund eligibility remains subject to verification, statutory conditions and quantification. A proposed exclusion for alleged prior supplier refund requires cogent documentary evidence, disclosure to the claimant and a reasonable opportunity to respond; supplier applications or unexplained back-office records alone do not establish double refund.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4918