Head Office cost allocation requires prescribed transfer-pricing methods; treaty ceilings bar surcharge and cess, while duplicate taxation is excluded...
Cost-to-cost reimbursement of seconded employees is not service consideration; transfer-pricing markup was deleted and amalgamation amortisation allow...
Crystallisation of liability supports prior-period expense deduction, while functionally distinct divisions require separate transfer-pricing benchmar...
Functional comparability under TNMM requires transaction-specific FAR analysis before benchmarking business-support services provided to associated en...
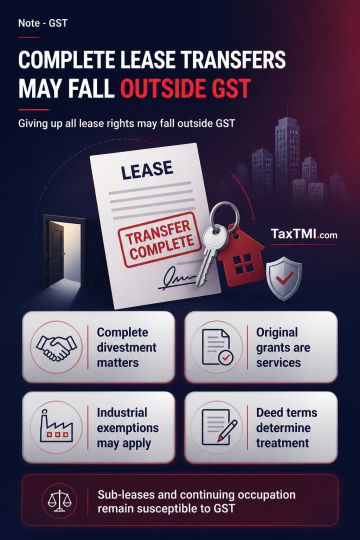
GST treatment of leasehold transfers depends on whether the transaction is an original grant, sub-lease, or complete assignment. An original grant of a lease, tenancy, easement or licence to occupy land is classified as a supply of services; qualifying long-term industrial leases may receive the stated exemption for upfront amounts. A complete assignment, where the outgoing lessee transfers the whole residual term, possession, building and associated benefits and retains no reversionary or possessory interest, may constitute transfer of an immovable-property interest rather than a taxable service. Consideration labels are not decisive; the deed, lessor consent, assignee substitution and future rent obligations determine characterisation. Sub-leases or continuing occupation arrangements remain susceptible to GST.
GST treatment of leasehold transfers depends on whether the transaction is an original grant, sub-lease, or complete assignment. An original grant of a lease, tenancy, easement or licence to occupy land is classified as a supply of services; qualifying long-term industrial leases may receive the stated exemption for upfront amounts. A complete assignment, where the outgoing lessee transfers the whole residual term, possession, building and associated benefits and retains no reversionary or possessory interest, may constitute transfer of an immovable-property interest rather than a taxable service. Consideration labels are not decisive; the deed, lessor consent, assignee substitution and future rent obligations determine characterisation. Sub-leases or continuing occupation arrangements remain susceptible to GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915