Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Agricultural-land reinvestment qualifies when transfer consideration precedes replacement purchase, while unexamined claims may be reassessed on escap...
Bona fide public fixed-deposit explanations prevent concealment penalties where unexplained-credit additions lack independent evidence of undisclosed ...
Page of 4915
Press 'Enter' after typing page number.
221 to 240 of 98288 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
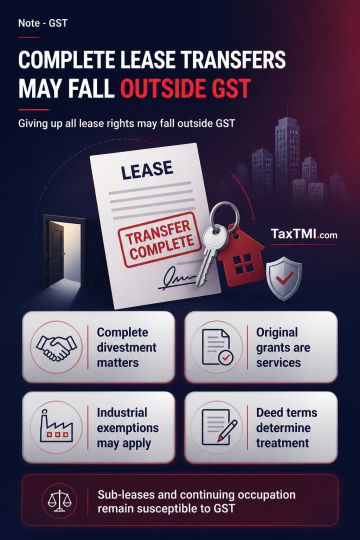
GST treatment of leasehold transfers depends on whether the transaction is an original grant, sub-lease, or complete assignment. An original grant of a lease, tenancy, easement or licence to occupy land is classified as a supply of services; qualifying long-term industrial leases may receive the stated exemption for upfront amounts. A complete assignment, where the outgoing lessee transfers the whole residual term, possession, building and associated benefits and retains no reversionary or possessory interest, may constitute transfer of an immovable-property interest rather than a taxable service. Consideration labels are not decisive; the deed, lessor consent, assignee substitution and future rent obligations determine characterisation. Sub-leases or continuing occupation arrangements remain susceptible to GST.
GST treatment of leasehold transfers depends on whether the transaction is an original grant, sub-lease, or complete assignment. An original grant of a lease, tenancy, easement or licence to occupy land is classified as a supply of services; qualifying long-term industrial leases may receive the stated exemption for upfront amounts. A complete assignment, where the outgoing lessee transfers the whole residual term, possession, building and associated benefits and retains no reversionary or possessory interest, may constitute transfer of an immovable-property interest rather than a taxable service. Consideration labels are not decisive; the deed, lessor consent, assignee substitution and future rent obligations determine characterisation. Sub-leases or continuing occupation arrangements remain susceptible to GST.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915