Advance pricing agreement methodology can guide benchmarking for non-covered years when functions, assets, risks and activities remain materially unch...
Tax-audit exemption for substantially State-funded educational universities prevents audit-failure penalties where income qualifies for statutory exem...
Functional, asset and risk analysis excludes diversified technology companies from captive software development comparables under cost-plus arrangemen...
Mobile-phone electronic evidence failed to establish customs undervaluation, while duty survived on non-authentic origin certificates without importer...
Automotive radio classification treats integrated infotainment features as supplementary, placing complete and qualifying unassembled units under the ...
Separate corporate personality prevents directors from being personally liable for company deposits without a guarantee or independent legal undertaki...
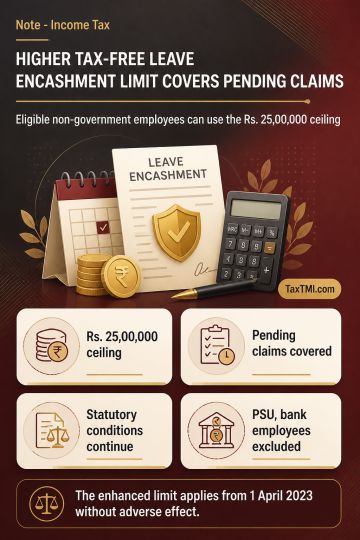
Section 10(10AA)(ii) governs retirement leave encashment received by employees other than Central or State Government employees. Exemption remains subject to the ten-month earned-leave limit, average-salary calculation, thirty-days-per-year leave entitlement restriction, aggregate limits for multiple employers, and adjustment for earlier exempt receipts. Notification No. 31/2023 raises the notified ceiling to Rs. 25,00,000 and states retrospective effect from 1 April 2023 without adverse effect. Tribunal authorities discussed apply the enhanced ceiling to eligible pending claims for earlier assessment years, while maintaining that public sector undertaking and bank employees do not qualify as government employees under Section 10(10AA)(i).
Section 10(10AA)(ii) governs retirement leave encashment received by employees other than Central or State Government employees. Exemption remains subject to the ten-month earned-leave limit, average-salary calculation, thirty-days-per-year leave entitlement restriction, aggregate limits for multiple employers, and adjustment for earlier exempt receipts. Notification No. 31/2023 raises the notified ceiling to Rs. 25,00,000 and states retrospective effect from 1 April 2023 without adverse effect. Tribunal authorities discussed apply the enhanced ceiling to eligible pending claims for earlier assessment years, while maintaining that public sector undertaking and bank employees do not qualify as government employees under Section 10(10AA)(i).
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915