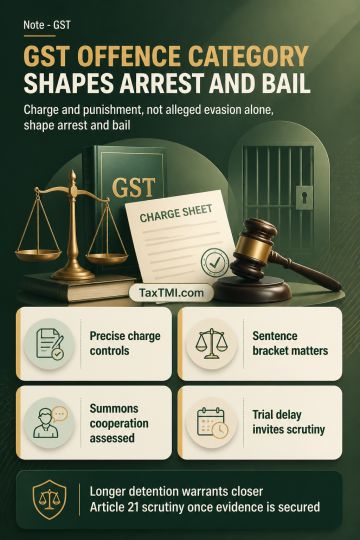
GST offence classification determines whether arrest and bail restrictions apply, while continued custody requires an individualised necessity assessm...
Delayed judgment pronouncement alone does not invalidate Tribunal orders, while rectification cannot reopen evidence or negate confiscation-related pe...
Page of 4920
Press 'Enter' after typing page number.
321 to 340 of 98394 Results
❮
❯
❯❯
0 / 200
Expand Note
Add to Folder
No Folders have been created
+
Are you sure you want to delete "My most important" ?
Profit on payments for subcontracted civil work cannot be separately estimated where the underlying contract receipts and profit have already been recorded, as this would duplicate disclosed profit; the related addition was deleted. A donation deduction remains disallowable where banking entries are unsupported by receipts. For delayed provident fund remittances, compensatory interest is deductible, whereas statutory damages for breach of payment obligations are penal and disallowable. The payment requires bifurcation between interest and damages, with the allowable interest component to be verified and permitted.
Profit on payments for subcontracted civil work cannot be separately estimated where the underlying contract receipts and profit have already been recorded, as this would duplicate disclosed profit; the related addition was deleted. A donation deduction remains disallowable where banking entries are unsupported by receipts. For delayed provident fund remittances, compensatory interest is deductible, whereas statutory damages for breach of payment obligations are penal and disallowable. The payment requires bifurcation between interest and damages, with the allowable interest component to be verified and permitted.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4920