Suspension of insolvency professional registration prevents continued Resolution Professional appointments and restricts interim stays that effectivel...
Original works exemption for railway contracts depends on actual integrated construction scope, while accessible tax data defeats suppression allegati...
Survey surrender characterisation determines whether mixed excess stock and business-linked cash face normal taxation or special deemed-income taxatio...
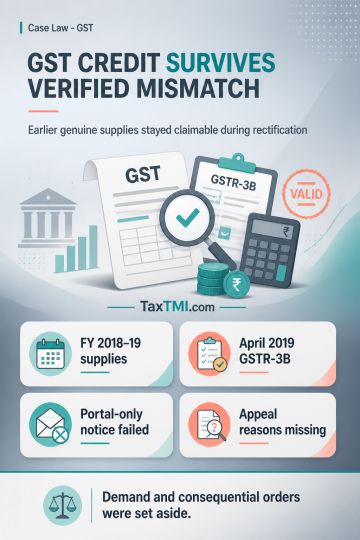
Input tax credit for genuine inward supplies from FY 2018-19, inadvertently omitted from corresponding returns, remained available when claimed in the April 2019 GSTR-3B within the then-permitted rectification period. At that time, GSTR-2A was facilitative; therefore, a GSTR-2A/GSTR-3B mismatch alone could not support reversal once the underlying supplies and credit were verified. Effective notice and a personal hearing were mandatory before an adverse GST decision. Notices placed only in a secondary portal tab, without hearing particulars, and orders issued on uncommunicated dates breached natural justice. Failure to consider appeal grounds and evidence or give reasons also invalidated the appellate decision. The demand and consequential orders were set aside.
Input tax credit for genuine inward supplies from FY 2018-19, inadvertently omitted from corresponding returns, remained available when claimed in the April 2019 GSTR-3B within the then-permitted rectification period. At that time, GSTR-2A was facilitative; therefore, a GSTR-2A/GSTR-3B mismatch alone could not support reversal once the underlying supplies and credit were verified. Effective notice and a personal hearing were mandatory before an adverse GST decision. Notices placed only in a secondary portal tab, without hearing particulars, and orders issued on uncommunicated dates breached natural justice. Failure to consider appeal grounds and evidence or give reasons also invalidated the appellate decision. The demand and consequential orders were set aside.
Note: It is a system-generated summary and is for quick reference only.
 TaxTMI
 TaxTMI

 of 4915